

What the furore over ‘lower-value human capital’ reveals about AI and the future of banking
Lenders are learning that the artificial intelligence transition requires more than charting productivity gains
AS BANKS around the world wax lyrical about the transformative potential of artificial intelligence, most executives have been careful to frame workforce reductions as part of broader efficiency drives, even as they pour billions of dollars into automation and AI.
But read between the lines and it becomes clear that even if AI is not the main driver of job cuts, it has certainly given banks the means to trim headcount on a scale not seen in years.
More than 10,000 jobs were cut on Wall Street last year – the most since 2016.
Wells Fargo made one of the biggest reductions, with a 5.7 per cent decline in staff strength to about 205,198 employees. Its CEO Charlie Scharf has been candid about AI’s impact.
“Anyone who sits here today and says that they don’t think they’ll have less headcount because of AI either doesn’t know what they’re talking about or is just not being totally honest about it,” he said in a media interview in November 2025.
Then came the comment that laid bare the industry’s simmering anxieties.
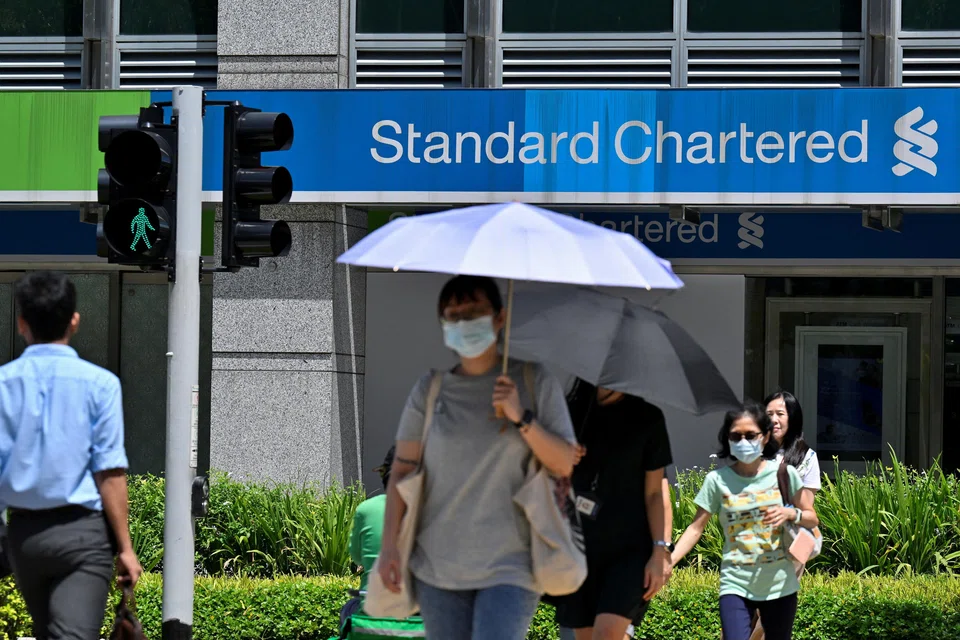
On Tuesday (May 19), London-headquartered Standard Chartered (StanChart) became one of the first major global banks to explicitly link planned job cuts to AI adoption, saying it would reduce 15 per cent of its corporate function roles by 2030.
There is certainly no easy way to announce job cuts. But it was long-time CEO Bill Winters’ description that triggered the backlash. The bank, he said, was “replacing in some cases lower-value human capital with the financial capital and the investment capital we’re putting in”.
Whether the remark was planned or not, the outrage was immediate, with even Singapore’s former president Halimah Yacob weighing in.
In an internal memo to staff later seen by The Business Times, Winters wrote that it “may be unsettling when reduced to simple headlines or a quote out of context”.
“Some roles will reduce in number, some will change, and new opportunities will emerge,” he wrote. “Where changes do happen, we will handle them with thought and care.”
The phrase “lower-value human capital” has since become meme fodder, with even the Financial Times joining in, selling merchandise emblazoned with the line on caps and T-shirts.
A trust problem emerges
The episode exposed the balancing act that banks face in managing the AI transition.
While AI is transforming finance and the productivity gains are real, how leaders communicate that change matters just as much as the technology itself.
This is especially so because employees harbour a lingering fear that the AI agents and systems that they are training may replace them one day. This creates a paradox: Staff are being expected to embrace tools that could well make parts of their roles redundant.
Just a day after the StanChart gaffe, Georges Elhedery, CEO of rival HSBC, stuck to a more familiar script used by bank chiefs for years: AI would destroy and create certain jobs in the financial industry, and this change requires large-scale retraining.
This was echoed by JPMorgan chief Jamie Dimon shortly after, suggesting that the bank will likely be hiring more for AI and fewer traditional bankers in certain functions.
Against this backdrop, employees need more than assurances that disruption is inevitable. They need a credible path forward – one that focuses less on what they may lose and more on the opportunities that could emerge.
A single clumsy phrase can undo all the possibilities that AI offers.
This means banks must go beyond rhetoric by identifying vulnerable workforce segments early, investing in reskilling and equipping them for the transition.
Singapore banks have not been immune to workforce reductions either. In 2025, DBS, OCBC and UOB shed nearly 3,000 jobs amid restructuring and productivity efforts. None directly attributed this to AI.
But DBS caused a stir in early 2025 when then CEO Piyush Gupta announced that the bank would reduce headcount of 4,000 contract and temporary staff over the next three years as AI increasingly takes over certain tasks.
He was one of the first banking chiefs to openly discuss how AI would affect jobs. The bank had since clarified that this would come from natural attrition.
Since then, Singapore’s major banks have largely positioned AI as a tool to augment workers, even as some roles evolve or disappear.
At DBS’ first-quarter results briefing, CEO Tan Su Shan said that the bank sees AI as an overall “net positive”.
In separate interviews, she spoke about the need to transform its workforce through training and encouraging a culture change from the rank-and-file to the board, emphasising a hands-on “learning by doing” approach to AI.
More importantly, she reiterated that the bank aims to “protect workers, not jobs” – a refrain consistently echoed by the government.
That distinction goes to the heart of the debate. If banks believe that AI will reshape work rather than simply eliminate jobs, they must back that with meaningful investments in training and redeployment.
Of course, the onus is on workers to stay relevant, be it in keeping up to date with the latest technologies that could affect their work, or even experimenting with new tools in their own time. Curiosity and flexibility are fast becoming career necessities.
The entry-level squeeze
Still, one group that banks need to pay attention to is those yet to join the workforce.
Entry-level jobs are slowly disappearing as AI automates routine work in banks and elsewhere. This means fewer of these newer hires get exposure to core foundational work, potentially weakening the industry’s future talent pipeline.
Singapore is trying to get ahead of this shift.
On Tuesday, Deputy Prime Minister and Minister for Trade and Industry Gan Kim Yong said that Singapore is working with the financial industry to expand internships and traineeships for graduates, providing structured training, exposure to leading financial institutions and a “meaningful stepping stone” to permanent employment.
It is still early days, but it sends an important signal that Singapore’s approach to AI transformation is not meant to be one of jobless growth.
Not every worker will keep their job through this transition. But staff deserve clarity about what lies ahead and should be given the support to prepare for it, with dignity and respect.
Banking is, after all, a high-trust industry. That trust should start internally.






