Mergers and acquisitions expected to rise in South-east Asia in 2025
Market watchers notice a flurry of activity among sovereign wealth funds and that capital is waiting to be funnelled into M&As
MERGERS and acquisitions (M&As) in South-east Asia are expected to rise in 2025, driven by, for example, the rising participation of sovereign wealth funds and raised private capital waiting to be deployed.
Abbas Rangwala, who heads M&As for South-east Asia and India at Natixis Corporate and Investment Banking, described 2024 as a “sluggish” year, noting that total deal values fell 54 per cent from 2023 levels.
The yearly activity was based on announced deals more than US$50 million in value, but which excluded financing and primary capital raising transactions, recapitalisation, restructuring, and special purpose acquisition company (Spac) mergers.
But he sees several key buyer trends that support his forecast of a rise in M&A activity this year.
One of them is the expanding number of and presence of sovereign wealth funds with a mandate to develop local businesses and critical industries.
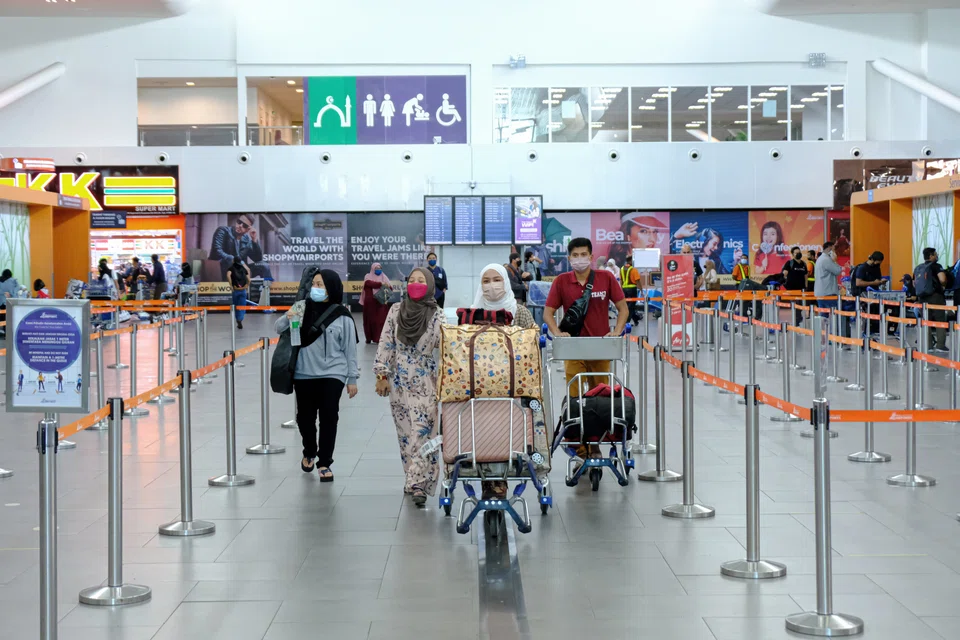
For example, Malaysian sovereign wealth fund Khazanah Nasional led a consortium last November to make a formal acquisition offer to take the listed Malaysia Airports Holdings private for RM11 a share.

Meanwhile, the numbers tracked by Bank of America have pointed to the volume of transactions being up 51 per cent in 2024 from the year before, fuelling bullishness about better days ahead.
Head of M&A for South-east Asia at the bank, John Lin, noted that the data, particularly for the second half of 2024, showed that confidence had returned to the market. “We believe there could be a strong rush for M&A opportunities to come to the market in the first half of 2025.”
He noted that the amount of private capital raised for alternative investors has remained very high. “We are seeing some deployment already, and we expect this to accelerate,” he added.
Rangwala agreed, saying that there was a growing pressure to deploy stockpiled dry powder, now that the pandemic has largely blown over. The rate-cut cycle is also expected to be a key tailwind in driving greater transaction volumes in the coming year amid an improvement in market conditions.
Also, South-east Asia continues to benefit from being geopolitically stable; its strong underlying macroeconomic tailwinds, added to Singapore being a magnet for foreign direct investment, are favourable factors for more M&A activity in the region.
Natixis has also noted significant interest from global multinational corporations, and Japanese and Chinese strategic investors and sponsors in setting up shop in Singapore. The region remains attractive as it has relatively lower market valuations; tourism has also normalised, and exports are expected to rise.
Bank of America continues to be optimistic about potential China funds flowing into the Asean region, coinciding with Beijing’s move to implement a comprehensive set of policies to reinvigorate domestic demand.
Lin said: “Furthermore, as the US continues to put up potential regulatory barriers to foreign ownership, we believe Chinese and Japanese buyer interest will increasingly allocate more time to South-east Asia to deploy their capital.”

Meanwhile, valuation gaps between buyers and sellers continue to narrow, particularly among sponsor-held portfolio companies facing a greater urgency to come to market.
PitchBook Data, a private equity-focused intelligence provider, said in a report that a highest-valued cohort of venture capital-backed companies in the region is expected to take the lead in expanding cross-border business and generating liquidity.
The median age at exit for South-east Asia-headquartered, venture capital-backed startups rose from about 5.5 years in 2015 to 7.5 years as at Nov 26, 2024 – the highest level in Pitchbook’s dataset.
The overall maturity of this cohort indicates that most of them should strategise and exit within the next few years, said PitchBook.
Asked about the sectors to watch, Natixis’ Rangwala listed sustainability and clean energy, logistics and supply-chain resilience and education platforms; these are in addition to 2024’s active sectors, namely healthcare, technology, media and telecommunications, industrials, and financials.
Bank of America has noted significant activity in the healthcare and financial-services arenas, on the back of Asean’s rising middle class and improving economic prospects.
Lin said: “We also continue to believe digital infrastructure will be a driver of activity, and expect it to enter a more mature market structure, with potential room for consolidation.”