

Citi sees Asian clients seeking more trade finance, risk support amid Middle East war
Firms and governments in Asia are reassessing their reliance on the Middle East for oil and energy supplies
[SINGAPORE] Asian companies are turning to banks for trade finance, liquidity support and risk-mitigation tools as the Middle East conflict strains energy supply chains, pushes up costs and forces some buyers to look beyond long-standing suppliers.
The conflict, which started in late February, has disrupted flows through the Strait of Hormuz – a key conduit for oil and gas shipments – sharpening energy-security concerns for Asia’s import-dependent economies.
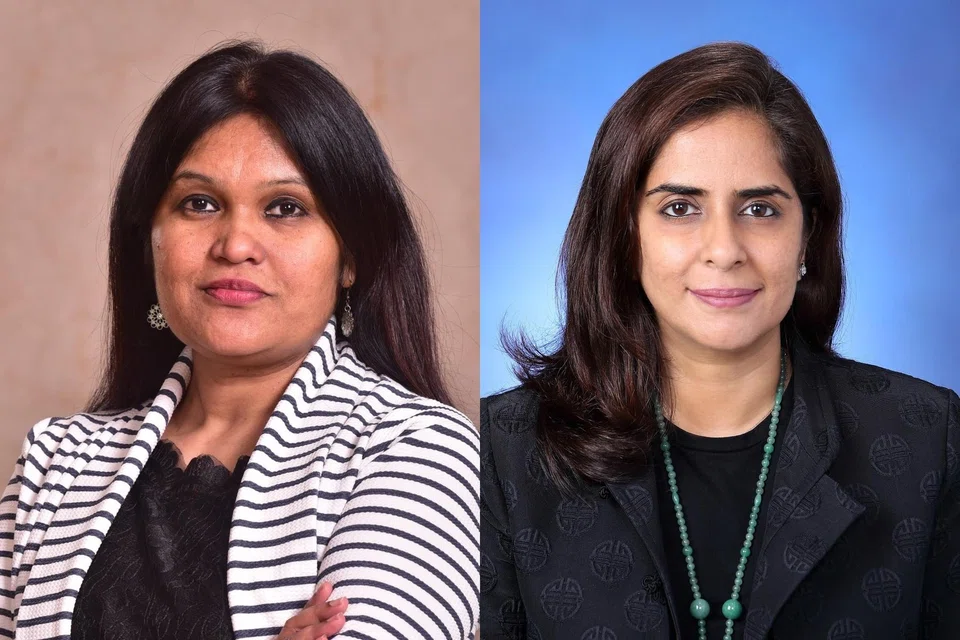
While many clients had initially expected the war to end quickly, that wait-and-see approach has started to shift as the conflict shows signs of becoming more prolonged, said Mridula Iyer, head of services for Asia South at Citi.
“In the first month or so, we did not see any major reaction from any of our clients because everybody expected the war to end pretty quickly,” Iyer told The Business Times in a recent interview.
But since April, companies and governments across Asia have begun reassessing their reliance on the Middle East for oil and energy supplies.
Countries have started taking measures such as curtailing usage or looking for alternative sources of energy, while companies are increasingly exploring new suppliers.
“We are increasingly seeing America (and) Venezuela emerging as geographies where clients have started seeing whether they can source more from,” Iyer said.
For banks, the opportunity is clearest in helping clients manage the risks and financing needs that come with such shifts.
Kanika Thakur, Citi’s head of services for Japan, Australia and Asia North, said at the same interview that this can be grouped into three areas: risk mitigation; financing and liquidity management; and helping companies keep businesses going amid uncertainty.
“Number one is risk mitigation,” Thakur said. “Risk mitigation could be diversifying sources of supply; in which case, if you have new suppliers, you may need guarantees, letters of credit, et cetera.”
“Number two is financing and liquidity management,” she continued. “Clients may need more money – (for instance), the cost of the total dollar value of one cargo of oil is much higher than it used to be.”
The third area, she said, is helping clients manage uncertainty and plan for future demand. This includes taking into account whether companies accelerate or slow shipments, how they reconfigure supply chains, and how consumers respond to higher energy costs.
“This is an uncertain environment; our role becomes even more pivotal with our presence in (more than 90 markets),” she added.
“In some cases, we make more revenue; in some cases we make less, depending on how the clients move. But this definitely gives us a ‘trusted adviser’ capability, which can come with its own opportunities.”
Higher costs, bigger credit needs
The early shift is creating demand for basic banking products such as letters of credit, even before companies commit to more sweeping changes in their supply chains.
Iyer said long-established Middle East supplier relationships had typically operated on existing commercial terms. But as companies pivot to newer supplier relationships, they need fresh support such as letters of credit, guarantees and financing.
The shift, however, is coming at a cost. Logistics, transportation, freight and insurance costs have climbed sharply in the wake of the conflict, even as companies explore new supply arrangements.
The impact is also flowing through to credit lines, as higher costs mean companies may need more headroom from lenders.
“What they could do previously with an ‘X’ credit limit, they now need (a) higher credit appetite because the costing of all the raw materials has gone up,” Iyer said.
Still, the conflict has not yet prompted a wholesale restructuring of supply chains.
In conversations with clients, companies are thinking about nearshoring, reshoring, diversifying supply chains, building inventory buffers and optimising working capital, the bankers said, but visible action remains limited for now.
If the conflict stretches further, however, companies may be forced into more structural responses.
The sectors most immediately exposed include oil and energy-linked industries. But both Iyer and Thakur warned that the impact could broaden if the conflict is prolonged.
Iyer said airlines, logistics and chemicals are among sectors that could come under stress in a longer conflict scenario, while Thakur said the third quarter will be a key point to watch.
“If there is a prolonged scenario, that impact will be felt far more widely,” Thakur said. “If this crisis goes into Q3, I think you will start seeing a lot more downstream impact on different industries.”
These could include shipping, logistics, consumer sentiment, travel and purchasing behaviour, she added.
TRENDING NOW

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
OCBC sheds S$8 billion in value as shares close nearly 6% down; analysts cautious on banks
Deal between tycoon friends sparks scrutiny of Philippine power sector

