

DBS, OCBC, UOB aim to stay competitive as foreign players slash mortgage rates
Foreign banks in Singapore have slashed their home loan rates to as low as 2.45%, lower than that offered by the local banks
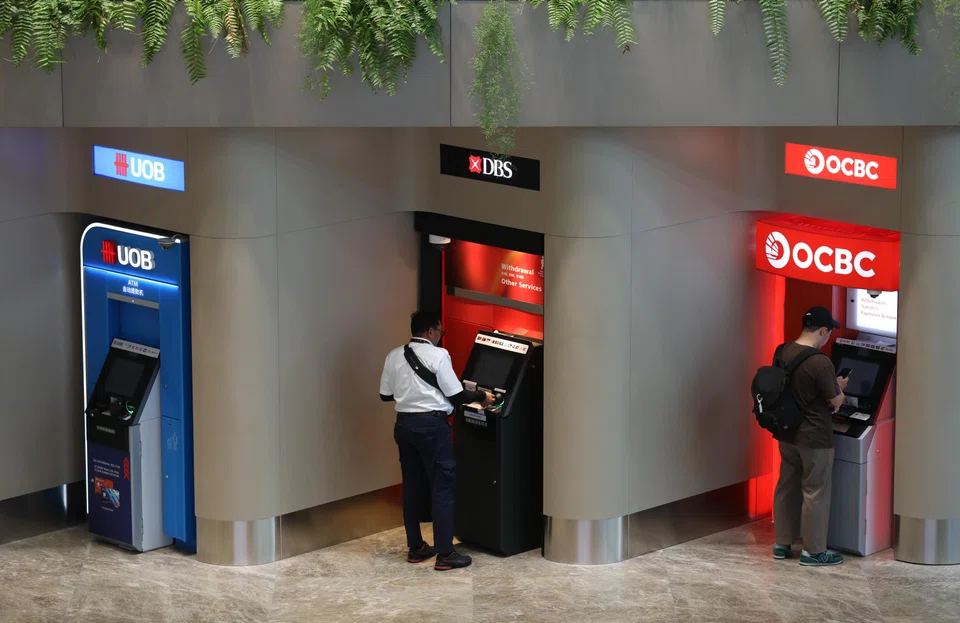
SINGAPORE’S local banking trio will continue to watch interest rate movements to ensure that their mortgage rates stay competitive.
At their respective third-quarter results briefings, management of DBS, UOB and OCBC said they will look at the market and adjust accordingly, but did not explicitly mention plans to cut rates.
This comes as foreign banks in Singapore have slashed their home loan rates to as low as 2.45 per cent, lower than that offered by the local banks.
DBS chief executive Piyush Gupta said the bank will not lead the cut on mortgages, especially after a new outlook on global rates emerged in the wake of Donald Trump’s win in the US presidential elections.
Post-election, the US Federal Reserve lowered its benchmark overnight borrowing rate by a quarter percentage point, or 25 basis points (bps), to a target range of 4.5 to 4.75 per cent.
Markets are expecting more inflationary policies from Trump’s administration, which may result in tighter monetary policies than expected, he said.
However, Gupta noted that some of the mortgage pricing in the market was “not entirely sensible”.
“If you compare the funding costs today, fixed deposits are higher than mortgage pricing – that’s kind of illogical,” he said.
Given that yields and rate expectations are moving up, Gupta said it would be “interesting to see” what the competitive response is.
A check of PropertyGuru Finance’s website shows DBS two-year fixed rate packages starting from 2.7 per cent although rates are dependent on loan amount, property type and tenure among other factors.
Rethink and recalibrate
For UOB, chief financial officer Lee Wai Fai said the market would have to rethink and recalibrate if the interest rate drop is not as aggressive as forecasted.
“Because if the market is aggressive, then technically we don’t mind losing money but hopefully making them later,” he said.
Lee said the lender wants to remain competitive in the market, given that mortgage in Singapore is a bright spot with a good risk adjusted returns profile. The lender’s house rate currently stands around 2.6 per cent.
As for OCBC, group chief executive Helen Wong said the bank is actively looking at repricing and how it manages its book.
“It’s not like if somebody else cuts, we will just cut immediately. It depends on how our pipeline is like, on how our relationship with the customer is like,” Wong said.
The management noted that OCBC has grown its mortgage book very well, while mortgage pricing of the local banks is also generally on a par.
Earlier in November, The Business Times reported that some foreign banks in Singapore have shaved rates by around 50 bps to 2.5 per cent, from the 3 per cent offered earlier.
The lowest offer so far this month, at 2.45 per cent, was from the Bank of China (BOC) with a lock-in period of three years. Standard Chartered and Maybank had 2.5 per cent packages.
Meanwhile, local lenders offered fixed home loans starting from rates of 2.55 per cent to 2.6 per cent.
Redbrick Mortgage Advisory associate director Clive Chng was quoted saying that most banks in Singapore lowered mortgage rates by five to 10 bps, following the US Federal Reserve’s cut in mid-September.
Only BOC is slashing rates by a larger amount in a knee-jerk reaction, as most lenders had already priced in lower rates before the Fed announcement, he added.
In a note in October, Bloomberg Intelligence credit analyst Rena Kwok said Singapore banks may intensify efforts to grow their fixed-rate mortgages with reasonable loan-to-value ratios in the secondary market into 2025, given their favourable risk returns and to bolster net interest income growth amid expected interest rate cuts.
Still, the banks could keep price discipline, as they aim to expand mortgage market share despite stiff competition, she added.






