

Singapore banks court younger customers as more climb wealth ladder
Banks report younger customers are investing sooner, with more progressing into affluent wealth tiers
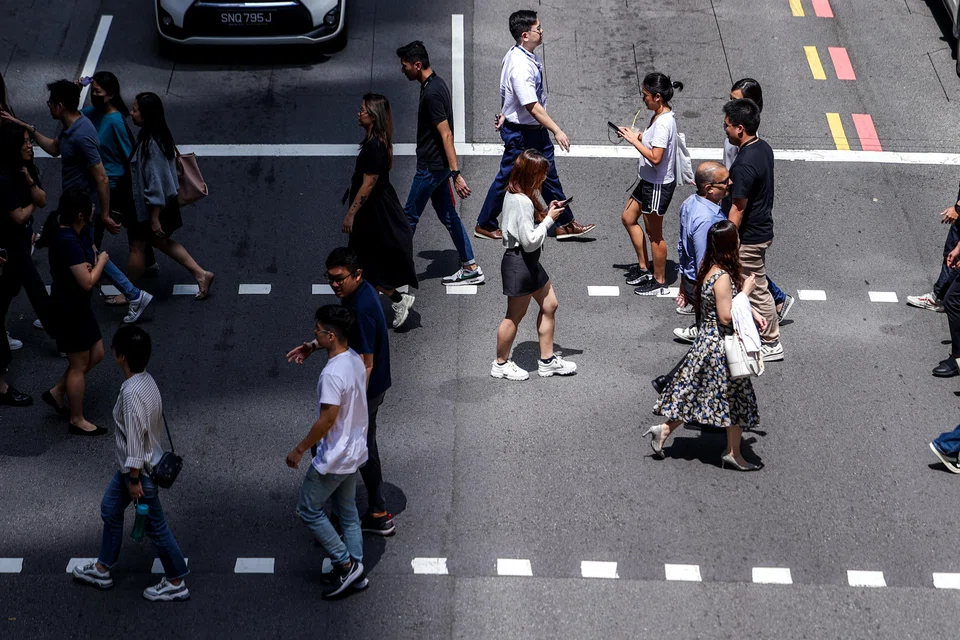
[SINGAPORE] More younger customers are moving up the wealth ladder as they start investing sooner, prompting Singapore banks to court them earlier in their financial journeys.
Greater financial literacy and easier access to investing are driving this shift, with young adults starting financial planning earlier and becoming more deliberate about growing their wealth, banks told The Business Times.
Jeffrey Tan, general manager, affluent coverage, onshore, wealth and retail banking, Singapore at Standard Chartered Bank, said: “Compared with previous generations, millennials are generally more financially engaged and have greater exposure to investment markets.”
“Rising living costs, longer-term retirement needs and a rapidly evolving job market are also reinforcing the importance of financial security, prompting this group to place greater emphasis on creating and preserving wealth.”
The trend is showing up in the number of younger customers moving into the banks’ affluent segments.
DBS said that the number of its millennial retail customers – aged 30 to 42 – who moved to its Treasures segment trebled in the first half of 2026, compared with the same period last year. DBS Treasures are for clients with investible assets worth between S$350,000 and S$1.5 million.
In the same period, HSBC said that the number of its clients, aged 25 to 35, grew double digits for its Premier segment, which requires a minimum assets under management (AUM) of S$200,000.
As for OCBC, the number of customers in their 20s progressing from a personal banking account to a Premier Banking and Premier Private Client banking account rose by almost 50 per cent on year, the highest growth among all age groups.
OCBC’s Premier Banking requires a minimum of S$350,000 in qualifying AUM, while Premier Private Client banking requires S$1.5 million.
Susan Tan, head of group segment at OCBC, said it is notable that many of these customers are not just accumulating wealth through savings, but are also becoming more intentional about growing it.
“More are putting their money to work through investments and doing so digitally,” she said, noting that the value of wealth transactions conducted digitally by those in their 20s increased nearly 120 per cent on year.
DBS is also seeing a similar pattern. The investment balances of clients who moved into DBS Treasures in 2025 have since grown nearly sixfold.
This shows greater awareness among younger clients of the importance of starting their wealth planning earlier, said Andrew Bok, head of DBS Treasures Singapore.
StanChart recorded a similar trend: The total wealth AUM of those aged 30 to 45 grew 70 per cent from December 2024 to June 2026, while average wealth holdings per millennial client nearly doubled over the same period.
Starting earlier, investing more regularly
Apart from starting earlier, young adults are also investing more regularly.
UOB said its regional customers aged 16 to 24, who began investing in the 12 months to April 2026, grew by more than 10 per cent from the previous year.
Among this group, recurring digital unit trust transactions rose by more than 10 per cent.
“Young adults are taking a more balanced approach to their finances,” said Jacquelyn Tan, head of group personal financial services at UOB.
“They are investing for the future by starting their wealth journeys earlier, and on a regular basis rather than waiting till they have accumulated significant assets.”
This may be driven in part by better financial literacy.
Ashmita Acharya, head of international wealth and premier banking at HSBC Singapore, noted that the Republic has a “very savvy younger affluent population” that uses a mix of self-directed and supported journeys to make their investment decisions.
“A few factors are likely driving this shift – greater financial literacy, easier access to market information and investment education, and (the) flexibility of investing using their preferred channels,” she said.
Competition for younger wealth
The shift comes as banks in Singapore seek to grow their wealth management businesses by attracting more AUM and getting customers to invest.
As younger customers start building wealth earlier, lenders are also looking to engage them earlier in their financial journeys and retain them as they move into higher wealth tiers.
Younger clients are “often more proactive in how they research and manage their finances”, StanChart’s Tan noted.
“However, when making important financial and investment decisions, we continue to see clients turn to us for deeper discussions about their financial goals and priorities,” he said.
For this digitally-native segment, the banks noted the need to use both human and digital engagement.
DBS earlier announced plans to hire more than 600 additional relationship managers, front-line advisers and platform engineers by the end of 2028, as well as open 18 new wealth centres and upgrade 36 existing centres across the Asia-Pacific by end-2027.
“While many are demonstrating greater financial savvy and are comfortable investing independently through digital channels, we believe our role is also to help them make informed decisions with confidence,” Bok added.
Meanwhile, UOB’s Tan said that the bank is focused on helping younger adults establish strong financial foundations early, and providing easy access to wealth guidance from the start of their financial journey.
UOB said it makes investment accessible through its app’s digital investment capabilities – for example, young adults can start investing regularly from S$100 a month, and access professionally managed portfolios.
“Ultimately, our goal is to build enduring relationships across the wealth continuum, for different personas, including our (Generation Z) customers, and support them as they progress through the various life stages and as their needs and priorities evolve,” UOB’s Tan added.
Younger affluent customers are also setting higher expectations for how technology and human expertise work together, said HSBC’s Acharya.
The bank noted the need to equip advisers with artificial intelligence-powered capabilities, given that 45 per cent of affluent Gen Z investors in Singapore favour AI-led discovery for investment ideas followed by adviser validation, compared with 38 per cent of their global peers.
Banks are also reaching out to customers from a younger age.
OCBC noted initiatives to engage the younger crowd, such as maintaining a presence on Singapore university campuses, as well as its GENesis programme, which is designed for children of affluent customers.
The bank previously announced plans to hire 600 wealth advisers over the next three years to strengthen its wealth management capabilities.
OCBC’s Tan said: “By starting conversations around wealth early, we are able to build long-term relationships and support them as they progress through different life phases.”
TRENDING NOW

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

OCBC sheds S$8 billion in value as shares close nearly 6% down; analysts cautious on banks
Deal between tycoon friends sparks scrutiny of Philippine power sector

