UI Boustead Reit launches S$1.2 billion IPO at S$0.88 per unit
Following the offering, the trust will have a total market capitalisation of S$1.95 billion
[SINGAPORE] UI Boustead Real Estate Investment Trust (Reit) has launched its initial public offering (IPO) of about 677.2 million units at S$0.88 each, and is expected to start trading on the Singapore Exchange mainboard on Mar 12.
It expects to raise gross proceeds of around S$1.2 billion from the offer and issuance of cornerstone units. Including debt facilities and the sponsor and Boustead Projects contribution, the trust will have just over S$2 billion in proceeds.
The manager has earmarked around S$1.9 billion for the acquisition of properties, S$40.6 million for the payment of refundable consumption tax, S$36.9 million for issue expenses, S$43.4 million for transaction costs, and the remaining S$19.7 million for working capital and cash reserves.
The company registered its prospectus on Thursday (Mar 5), offering a public tranche of 33.9 million units. Some 643.3 million are being offered as placement units.
Cornerstone investors, including Amova Asset Management and Amundi’s Singapore and Malaysia entities, have entered into separate agreements to subscribe to around 429.2 million new units.
Following the offering, UI Boustead Reit will have a total market capitalisation of S$1.95 billion.
Speaking to the media on Thursday, the manager’s chief executive officer Tan Shu Lin said that its immediate priority is to deliver on the IPO forecasts. These include a projected distribution yield of 7.8 per cent in FY2027, its first full year of operation, and organic year-on-year growth of 4.8 per cent in distribution per unit (DPU).
The Reit will hold 23 assets in Singapore and Japan, valued at S$1.9 billion as at end-September. In the near-to-medium term, Tan noted that the portfolio will likely maintain a roughly 70:30 split between Singapore and Japan. “We’re quite comfortable with the (split), and this is what unitholders probably signed up for as well.”
A new five-storey logistics facility in Tuas – completed in February 2025 and valued at S$220 million as at March 2025 – is expected to be acquired from sponsor UIB and injected into the Reit once stabilised.
UIB was formed through Unified Industrial’s acquisition of Boustead Singapore’s fund and property management business in March 2025. Boustead owns a roughly 20 per cent stake in the entity.
Spanning 640,147 sq ft in gross floor area, the facility is currently in the leasing phase. Major tenants include a global apparel brand, and a multinational shipping and logistics solutions provider.
The manager is also eyeing two co-development projects. One is a built-to-suit industrial facility in Singapore for an existing tenant that has already committed to leasing the space once construction completes. The other is a two-storey logistics facility in Osaka, with the majority of space pre-committed to a major anchor tenant.
“We’re actually quite interested to participate in (the two co-development opportunities), simply because there is a very high level of pre-commitment in these developments… (reducing) leasing risk,” explained Tan.
Overall portfolio occupancy is expected to rise from 89 per cent currently to a targeted 93 per cent by March 2026 and 98 per cent by March 2027.
“As we move the occupancy closer to 98 per cent, that is where the uplift in the DPU is going to come from,” said Tan.
Ho Tai Wing, head of the manager’s investment and asset management, noted that the team was “quite confident” in achieving these targets, citing leasing progress across several assets. These include an eight-storey industrial building at 26 Tai Seng and two assets in Japan.
One of the assets in Japan, a logistics facility in Osaka that was completed in May last year, is already 82.5 per cent leased as at March 2026, with more contracts expected soon, said Ho. By March next year, occupancy is expected to be 99.4 per cent. The other is a business space property in Tokyo, which was fully tenanted as at late February.
At 26 Tai Seng, Ho noted that a former food tenant has vacated, but new tenants – including Jumbo Group, which already occupied more than half of the building’s net lettable area – have largely backfilled the space. Jumbo has since opened Jumboree, a 17,997 sq ft food hall on the first floor. The remaining one and a half floors have also received offers from two tenants, which would bring the property back to full occupancy, he added.
These developments put the Reit “pretty much on track” to achieve its 98 per cent target by March 2027.
The trust has a weighted average lease expiry of 5.8 years as at Sep 30, 2025, with almost 15 per cent of leases extending over 10 years.
For FY2027, around 87 per cent of rental income is secured, leaving 13 per cent exposed to potential variability, Tan added. “So it’s a very, very stable portfolio, but there’s very little variability.”
The manager is aiming to deliver stronger rental reversions, which account for 0.3 percentage points of the 4.8 per cent organic growth forecast. “We are hoping to at least deliver more than 0.3 per cent, because I think we were quite conservative in our IPO assumptions,” said Tan.
Market outlook
Ho pointed out that rents across the portfolio remain supported by generally favourable market fundamentals.
The logistics sector continues to perform well, with occupancy remaining at 100 per cent and “very good rental reversions” in the double digits.
Business park and high-spec industrial spaces faced supply pressures previously, he added. The manager’s focus has therefore been on maintaining occupancy above 90 per cent, with rents remaining fairly flat.
With the supply pipeline now easing, Ho expects stronger rental upside.
According to Ho, many general industrial properties remain under-rented due to low entry rents, particularly for sites originally allocated directly by JTC. These assets typically have longer leases, allowing tenants to recoup capital. “These are the cases where (the point of renewal) will give us a very good upside.”
In the nearer term, multi-tenanted buildings in business parks and high-spec spaces are expected to see stronger rental growth. “Once the current stock (is) absorbed towards the second half of this year, that will be the time when we will see more upside,” noted Ho.
On expansion beyond Singapore and Japan, Tan said that the manager will focus on markets where the sponsor has established roots.
“Real estate management is not just having a property, it’s also about managing the tenants,” she added. “We do want to have boots on the ground to really understand the market, help us get the occupancy and rental growth… So we’ll be quite careful in our expansion beyond the geographical reach of our sponsor.”
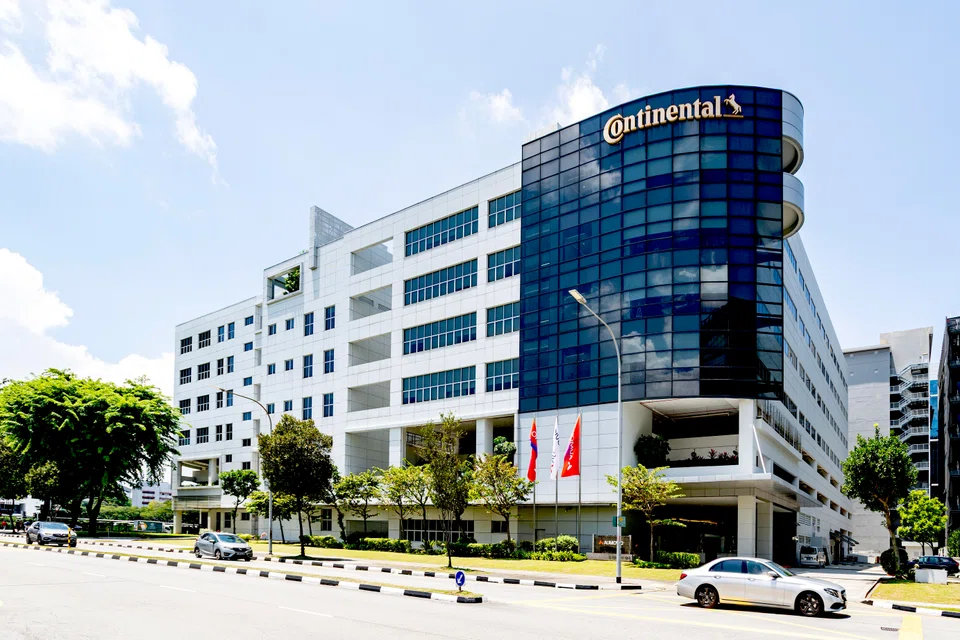
The manager has also budgeted about S$3 million for an asset enhancement initiative (AEI) at the Aumovio Building in Boon Keng, which will start after the property is vacated in May. The AEI will convert the single-tenanted building to a multi-tenanted one.
The manager expects the AEI to take around nine months to complete. Net property income is projected to rise from S$2.3 million to S$3 million.