

No longer ‘doing well by doing good’, ESG investing is about acknowledging trade-offs: Fidelity CSO
DOING well by doing good – that has largely been the mantra fuelling environmental, social and governance (ESG) investing for the last few years.
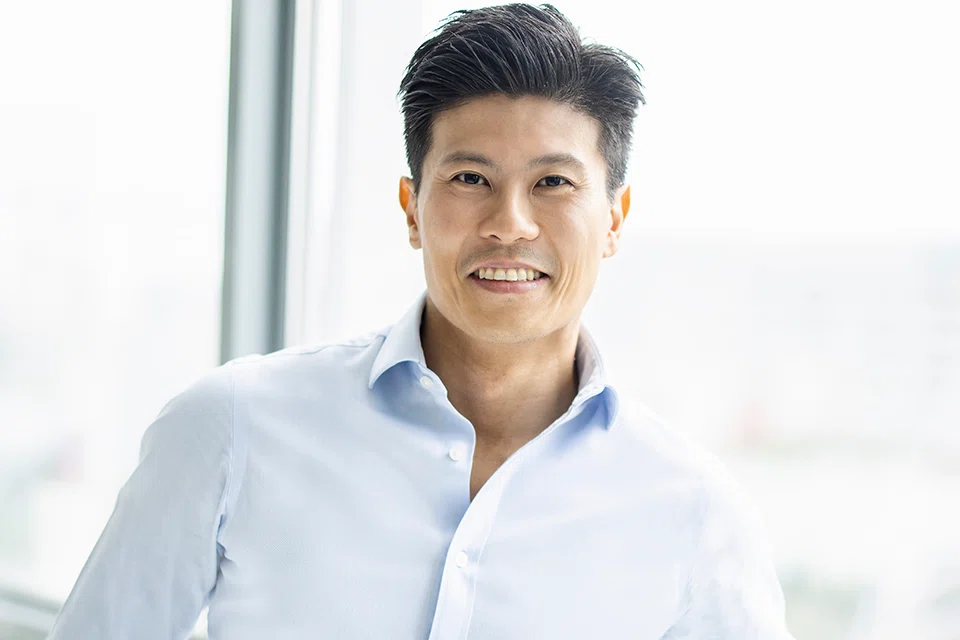
The landscape of ESG investing is entering a new phase, though, where trade-offs have to be acknowledged, said Tan Jenn-hui, chief sustainability officer (CSO) of Fidelity International.
“I think there was a time when ESG was always ‘I make money by doing good’,” said Tan in an interview with The Business Times. “I think you have to be honest about it and say that now, where ESG is coming to, you need to acknowledge what (the) trade-offs are.”
The most pressing of these trade-off discussions is the just transition – how to transition from fossil fuels to renewables in an equitable manner.
“The topic of just transition itself is about trade-offs,” Tan added. “How quickly do you want to decarbonise versus how much do you want to look at other factors?”
From a technical perspective, he noted, the problems of energy transition are already solved. The right tools to develop alternative sources of energy are already available.
The complication is in the application, as countries and companies have varying levels of reliance on fossil fuels as an energy or income source – making them unable or unwilling to decarbonise quickly.
How does Fidelity factor such trade-offs into its investment-making decisions?
As a global asset manager, Tan said, Fidelity’s ability to generate returns over the next 10 or even 20 years depends on the ability to identify companies that would be long-term winners. That also means looking for companies that are able to navigate the just transition.
Besides utilising obvious climate-related metrics such as greenhouse gas emissions, Fidelity also incorporates just transition metrics when assessing the ESG credentials of its investee companies.
These include a company’s approach towards employee management, how it manages the impact of its operations on the community, as well as its contributions to keeping basic goods such as electricity affordable.
Tan said that the just transition is a helpful part of Fidelity’s analytical toolkit, as it helps the manager understand the challenges investee companies face when they undertake their decarbonisation journeys, including the regulatory environments in which they are operating.
Energy transitions that do not take into account the social implications will quickly lose popular support, Tan pointed out.
“You’ll disproportionately impact lower-pay communities, and will disproportionately impact workers. Very quickly, the political support you need for the kinds of policies that incentivise decarbonisation will start to go away.
“So, countries and companies need to be able to balance these impacts when they undertake the kinds of decarbonisation initiatives that contribute to that 1.5 degree Celsius objective.”
How would Fidelity navigate a situation in which its investee company, such as a thermal coal power plant owner, has to make trade-offs during its decarbonisation process?
Tan said that Fidelity evaluates trade-offs with an objective of creating sustainable long-term value.
In the context of coal phase-out, long-term value can come from gradually winding down coal-based operations in accordance with national objectives. Capital can then be returned to shareholders, to be recycled into other projects.
Given the complexities involved in such projects, however, interests may arise that, if accommodated, do not contribute to sustainable long-term value creation.
“The job of finance is not to address the interest of every single stakeholder across every single time period,” Tan explained.
“Where I think we don’t have a mandate, and I’m not particularly interested in going down, is undertaking activities that don’t have any relevance to sustainable long-term value creation. So when I think about the trade-offs that Fidelity needs to make, I’m thinking about what are the right trade-offs that lead to that end outcome.”
How does Fidelity ensure its objectives are met, though, especially as shareholder activism is increasingly polarising?
Earlier this year, ExxonMobil filed a lawsuit against some of its activist investors that had been pushing the oil and gas giant to undertake more ambitious climate action.
Tan said that Fidelity does not believe in using shareholder proposals to influence management strategy. “If we don’t like what management is doing, and we don’t agree with the long-term structure of the company, we’re simply not invested at all. There’s no point in us putting our capital where we don’t have that conviction.”
For Fidelity, voting is not a mechanism to punish companies. Instead, Tan said, it is a complement to constant discussions.
To begin with, he noted, voting as a mechanism of change is limited in Asia as most public companies in the region are controlled by a single shareholder.
It can also be hard to show a relationship of causation between how investors vote and what companies eventually decide to do.
“I don’t ever think it works in that linear way. Companies do things for a lot of different reasons that ultimately align to their long-term objectives,” Tan added.
“They do so to respond to a broader constellation of factors. The most that we can hope for is that we’re part of that conversation and that dialogue.”
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Inside Singapore’s government team that kills its own products
Johor’s investment boom is real, but actual contribution from JS-SEZ unclear
Inside F1: How ‘reactive’ DHL acted quickly to fit Malaysia race just before Singapore’s

