


Malaysian banks post mixed mid-2026 results as record loan growth offsets margin squeeze
H2 outlook hinges on continued strong credit demand; direction of broader non-fee income remains uncertain
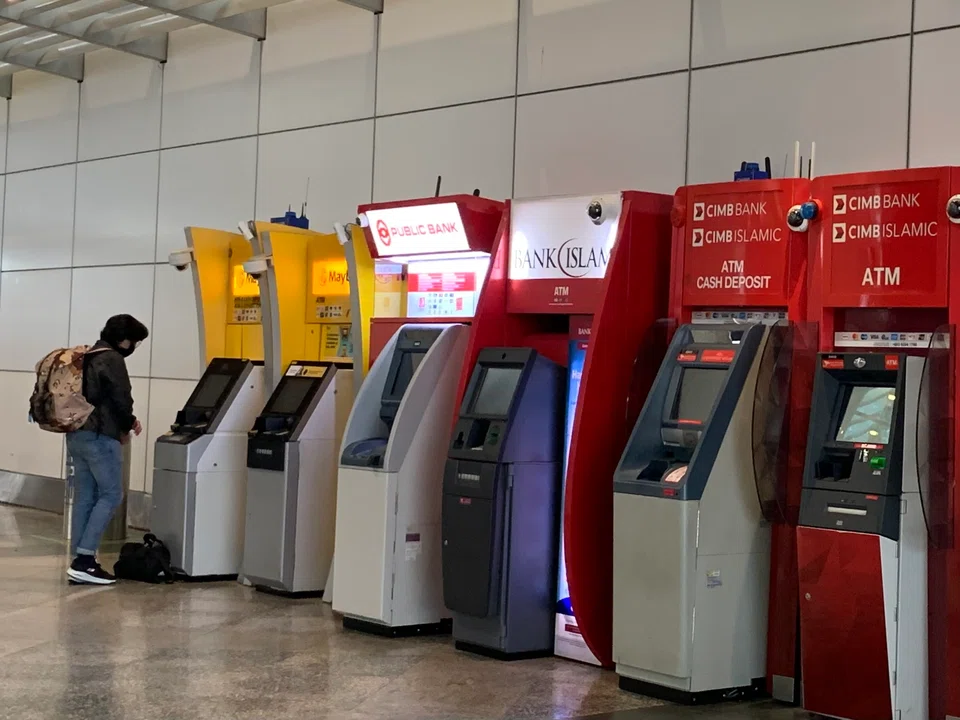
[KUALA LUMPUR] Malaysian banks entered the second half of 2026 with record business-loan growth and a strong lending pipeline. But earnings momentum was mixed as margin compression, volatile non-interest income and higher provisions weighed on several lenders.
Eight of the 10 listed banking groups reviewed by The Business Times posted higher net profit for the April-to-June quarter, according to Bursa Malaysia filings, although the growth was modest. MBSB and Affin Bank recorded declines.
The earnings outlook for H2 is expected to hinge increasingly on whether stronger credit demand can cushion lingering margin pressure, as the effects of last year’s rate cut continue to filter through the sector.
Mid-sized lender Alliance Bank Malaysia led the pack with a 25 per cent year-on-year jump in earnings to RM248.3 million (US$61.4 million) for its first quarter ended June 2026.
This was followed by Hong Leong Bank with a 14.2 per cent rise to RM1.24 billion in the financial quarter, while Bank Islam Malaysia, the country’s largest standalone Islamic bank, posted a 9.8 per cent increase to RM139.1 million.
Malaysia’s top three banking groups by assets – Maybank, CIMB and Public Bank – all posted higher net profit.
Maybank’s earnings expanded 2.4 per cent to RM2.7 billion, CIMB’s climbed 2.6 per cent to RM1.9 billion, while Public Bank recorded a 3.7 per cent increase to RM1.8 billion.
At the other end, financial services group MBSB, which is majority-owned by Malaysia’s state retirement fund, recorded the steepest decline among the lenders reviewed. Its net profit fell 53.7 per cent to RM44.2 million.
Weighed down by higher impairment allowances and a smaller share of associates’ results, mid-sized lender Affin Bank’s profit dropped 11.1 per cent to RM127.5 million.
MBSB Research analyst Samuel Woo described the sector’s performance as a “mixed bag”, identifying net interest margin (NIM) compression as the main drag on earnings.
Higher provisions and weaker non-fee income added to the pressure at some banks, although strong fee income and disciplined spending helped cushion the impact, he noted.
“Loan growth was excellent across the board and was backed by a surge in both deposit and non-deposit funding. Asset-quality issues were confined to smaller banks – larger peers didn’t see much negative impact,” Woo said in a report on Tuesday (Sep 1).
CGS International (CGSI) Securities Malaysia senior analyst Winson Ng said that banking-system loan growth accelerated to 5.6 per cent year on year in July, from 5.5 per cent in June.
Business-loan growth reached a record 7.5 per cent, up from 7.2 per cent in June and 3.9 per cent at end-2025.
According to CGSI, both loan applications and approvals hit record highs in July, reaching RM167.4 billion and RM90.4 billion, respectively – fuelled by a surge in demand for working capital.
Working capital approvals alone jumped 71.7 per cent to RM27.1 billion, marking a third straight month of double-digit expansion and accounting for nearly two-thirds of the year-on-year growth in overall applications and approvals in July.
Ng added that sustained loan growth should help offset any weakening of NIMs in H2, particularly as the downward repricing of fixed deposits has largely run its course following the July 2025 interest-rate cut.
Growing fee income
Woo noted that wealth-management fees were supporting top-line growth, as wealth flows shifted from the Middle East towards South-east Asia.
However, he cautioned that the broader non-fee income outlook remains uncertain after a challenging first half.
RHB Bank’s 0.5 per cent fall in second-quarter net profit to RM807.2 million, partly because of weak non-fee income, disappointed street expectations, noted MBSB Research.
For the first six months of 2026, RHB’s non-interest income declined 30.2 per cent year on year, dragged down by sharp falls in investment and foreign-exchange gains.
Nevertheless, CGSI said that RHB’s underlying earnings remained resilient. Net interest income rose 6.4 per cent year on year, while fee income jumped 22.2 per cent, driven by service charges, commissions and brokerage fees.
Impaired loans contained
Asset quality remained manageable at the system level, noted Ng.
The banking sector’s gross impaired-loan ratio held at 1.43 per cent in July. The increase in impaired loans narrowed to RM56.3 million during the month, compared with increases ranging from RM309 million to RM843.4 million in May and June.
Stress was more visible among some smaller lenders, according to MBSB Research.
The research house identified Affin Bank and Bank Islam as institutions to watch, with their residential mortgages and unsecured consumer lending among the areas of concern.
Bank Islam’s Q2 earnings growth has also masked a softer H2 outlook. Facing higher overheads, heavier provisioning and weak non-fee income, the lender lowered its full-year return-on-equity target to 5.5 per cent from 7 per cent.
Outperformers and outlook
MBSB Research favoured Hong Leong Bank, among the outperformers in the quarter, for its strong asset quality, cost control and regional growth opportunities. It also highlighted Alliance Bank for its improving credit costs and the potential for higher dividend payouts.
Woo described Hong Leong Bank as a resilient growth pick amid market uncertainty, supported by its dividend yield and expanding regional presence.
“While facing short-term headwinds such as margin compression and cost inflation, its regional expansion drives strong potential for rapid loan and fee income growth,” he said.
Alliance Bank’s Q1 earnings exceeded both MBSB Research’s and consensus expectations, accounting for about 29 per cent of their respective full-year forecasts. The stronger performance was driven primarily by corporate recoveries and lower-than-expected provisions.
Hong Leong Investment Bank maintained its “buy” rating on Alliance Bank and raised its FY2027 and FY2028 earnings estimates by 4.3 per cent and 0.9 per cent, respectively. It noted that stronger capital buffers could support a dividend payout above the bank’s target range of 40 to 50 per cent.
CGSI adopted a different forward-looking position, naming Maybank, RHB and Public Bank as its preferred sector picks, based partly on their dividend yields, capital-management prospects and potential earnings recovery.
It reiterated its “add” rating on Maybank, supported by a projected FY2026 dividend yield of 6.1 per cent. Potential rerating catalysts included margin expansion and earnings accretion from Maybank’s proposed acquisition of the remaining stake in insurance associate Maybank Ageas.
Maybank set aside an additional RM300 million in management overlays in H1, raising its total buffer to RM2.6 billion to cover risks associated with elevated oil prices.
The additional provision contributed to a 0.9 per cent year-on-year decline in Maybank’s H1 net profit. Excluding the overlay, underlying profit would have grown by 3.5 per cent, CGSI estimated.
If credit risks ease and Maybank releases part of the reserves, every 10 per cent write-back could lift its FY2026 and FY2027 net profit by between 1.6 and 1.8 per cent, said the research house.
For Public Bank, although its H1 results fell short of expectations, CGSI said that its push into fee income was bearing fruit. The lender’s Q2 fee revenue jumped 25.6 per cent year on year, driven by a 53.6 per cent increase in asset-management income.
CGSI reiterated its “add” rating on Public Bank, citing its capital-management initiatives, strengthening fee-income momentum and prospects for higher returns on equity through to FY2028.


