


Ringgit’s winning streak masks Asia’s currency weakness
Philippine peso and dong breach record lows; rupiah, won and yen continue slide
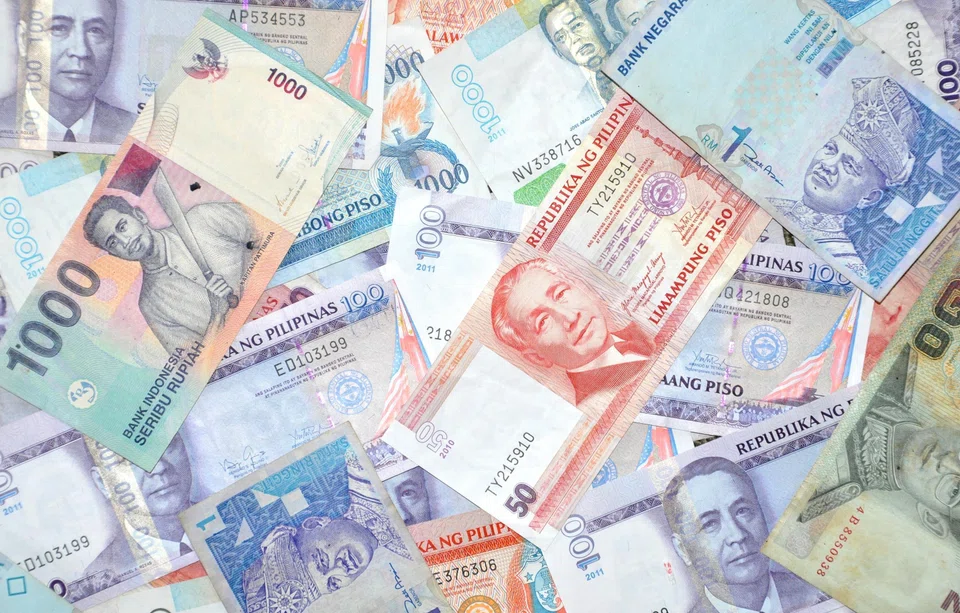
THE ringgit, crowned the worst performer in emerging Asia two years ago, is now giving its Asian counterparts a run for their money as its winning streak against the greenback inches towards a four-year record.
Behind the Malaysian currency’s outperformance lies a more muted regional showing: The Philippine peso is charting a fresh nadir against the US dollar; the dong deepens its decline, repeatedly breaching record lows; and the battered rupiah persists down a volatile slide.
The East Asian currencies fared rosier in their year-to-date performance against the US dollar – until the won and yen entered the final quarter on a downtrend that is threatening their slim gains for the year.
Asean’s underachievers
The worst performers across South-east Asia in the year to date are the rupiah and the dong.
After breaching a record low in April, the Indonesian currency recouped most of its losses with the help of intervention from its central bank. But it continues facing downward pressure that sees it hovering around 16,700 to the US dollar, versus 16,100 at the start of the year.
UOB Kay Hian analyst Suryaputra Wijaksana expects persistent near-term pressure on the rupiah and additional weakening next year.
“The rupiah is expected to remain under moderate pressure until the end of 2025, driven by a narrowing trade balance, continued foreign capital outflows, and a growing monetary policy divergence with a less dovish US Federal Reserve,” he wrote in a Monday (Nov 10) report.
The forecast into next year remains bleak.
Accelerating broad money growth, low interest rate differentials with the Fed and a worsening current account deficit on rising imports will all put additional weakening pressure on the Indonesian currency, said the analyst.
But the silver lining is that potential government policies could partially offset such depreciation pressures, he concluded.
Examples he raised include revised measures to increase the time deposits of exporters, new instruments designed to attract foreign capital and a potential increase in foreign direct investment spurred by anticipated political stability in 2026.
The Vietnamese currency fared no better.
The beleaguered dong breached its record low several times this year, sinking more than 3 per cent against the greenback since the beginning of the year – even as its American counterpart weakened 8.2 per cent in the same period.
But even if the soft US dollar backdrop were to continue, any rally in the dong will be tempered by the need to rebuild foreign exchange reserves, said Fitch Solutions’ BMI in a Nov 4 report.
Its analysts expect the State Bank of Vietnam to keep its policy rate unchanged till end-2026 and instead rely on moral persuasion and credit-boosting policies, noting that the weak dong will remain a constraint on further easing.
Meanwhile, the Philippine peso reversed all its gains for the year in a dramatic turnabout and is now charting a record low that breached the 59.2-per US dollar level.
When it first sank past the all-time-low on Oct 28, Bangko Sentral ng Pilipinas (BSP) released a statement stating that the recent peso depreciation may reflect market concerns over a potential moderation in economic growth, due in part to the infrastructure spending controversy.
BSP also attributed the peso’s decline to expectations of additional monetary policy easing. For its past four consecutive meetings in April, June, August and October, the central bank doled out a quarter-point cut each. Its next monetary board meeting is scheduled for Dec 11.

East Asia (barely) holds on
Also at risk of reversing their fortunes are the yen and won, which – despite having held onto their year-to-date gains – entered the final quarter of the year on a downtrend against the greenback.
The Korean currency is the weakest across Asia in the past three months and its underperformance has been a year-to-date problem, said Bank of America (BofA) Global Research analysts in a Nov 9 note titled A tsunami of outflows.
The won is charting a gain of less than 0.4 per cent against the greenback at around 1,467 to the US dollar since the start of the year, reversing its broad first-half uptrend.
Its sharp underperformance was attributed to the continuation of a year-to-date trend of strong portfolio outflows by all major investor groups in South Korea.
The BofA analysts added that the country’s large-scale overseas investment commitments and slowing semiconductor exports further weighed on investor confidence.
The house expects strong portfolio outflows seen in this year to continue into 2026, causing the won to remain weak despite its projection of a weaker US dollar next year.
Meanwhile, the yen is now trading near the 155 level against the greenback – still an appreciation from the 157-per-US dollar threshold at the start of the year but a sharp decline from a year’s high of around 140.
Maybank analysts noted in a Wednesday report that the main driving force of the US dollar against the yen this week was speculation of an ending US government shutdown, which buoyed risk sentiment and the currency pair.
But the house maintained that it leans on the downside for the pair, highlighting the possibility of some decline in US rates amid the risk of more softness showing up in the American economy.
Swissquote senior analyst Ipek Ozkardeskaya cautioned in a Tuesday report that it is wise to hedge against further yen depreciation, going as far as to say that the currency pair – if left alone – could see the yen weaken to 160 per US dollar.
Standout plays
Recall that the ringgit is currently charting a 13-month-high, now measuring at around 4.13 per US dollar versus 4.47 at the start of the year – and the rally still has juice.
The ringgit’s outperformance widened of late, noted Maybank analysts in a Wednesday report, while the US dollar is largely still bound within its previous range.
“While the broader US dollar index continued to eke out gains in the absence of significant US data releases during the shutdown and a more hawkish (Fed chair Jerome Powell), the ringgit was extremely resilient,” they said.
The house added that optimism for the Malaysian currency is well grounded in fundamentals, highlighting the country’s efforts in fiscal prudence and towards future economic development, such as the Johor-Singapore Special Economic Zone.
Apart from the ringgit, the only other South-east Asian majors tracking gains against the US dollar are the Singapore dollar and the baht.
The Singdollar put up a strong showing in 2025, spending most of this year below the key 1.3 threshold against its US peer. Some economists even speculated that the safe-haven currency could reach parity with the greenback within 15 years from now.
The baht held its own this year, notching a more than 5 per cent gain against the greenback to date and is trending at around 32.5 per US dollar versus 34.3 at the start of the year.
But excessive currency gains are likely to be capped, said DBS Group Research’s senior economist Chua Han Teng in an earlier Oct 9 report, noting the Bank of Thailand’s dovish tone and its vigilance over the baht’s appreciatory moves.






