


Thailand’s energy shock may force long-delayed reforms
A prolonged Middle East conflict could weigh on country’s growth by driving up costs in an economy heavily reliant on imported gas
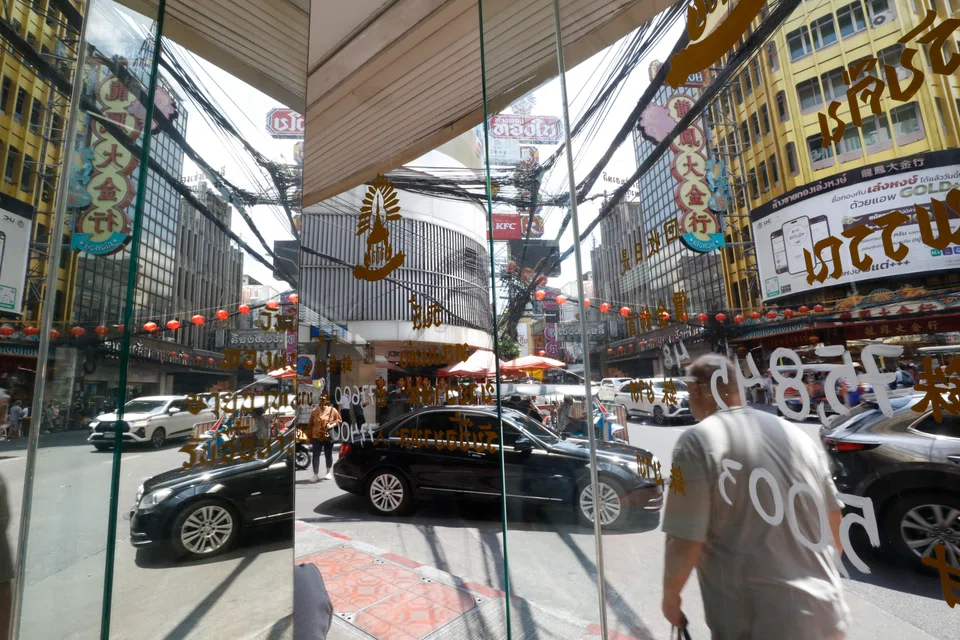
[BANGKOK] Rising oil and gas prices from the Middle East conflict are set to weigh on Thailand’s export and tourism-dependent economy, while also sharpening pressure on the next government to push through long-delayed structural reforms.
One area likely to come under renewed focus is direct power purchase agreements, or DPPAs, which are seen as critical to supporting investment in data centres and other industries seeking access to renewable energy.
Thailand approved a pilot scheme in 2024 allowing eligible data centres to source up to 2,000 megawatts of renewable electricity directly from private producers, but implementation has been slow.
The delay reflects government changes – at least three prime ministers in three years – and disagreements over the electricity prices, said Dr Areeporn Asawinpongphan, energy policy research fellow at the Thailand Development Research Institute.
“I think it should be a top priority for the next government because the DPPA directly impacts investment in the economy, not just for data centres, but (also) for the whole industrial sector.”
The delays over the DPPA are part of a broader problem.
Investors – both domestic and foreign – have long complained that outdated rules and slow-moving legislation are holding back investment in sectors that Thailand hopes will drive future growth, including green manufacturing, digital services and wellness.
Thailand’s next government, which should be formed by around May at the earliest, will face mounting pressure from the private sector to push through structural reforms and find new growth engines for an economy that was forecast to expand by 1.5 to 2.5 per cent this year, before the latest Middle East conflict drove up energy risks.
If the war is protracted with a prolonged closure of the Strait of Hormuz, oil prices could rise to US$115 to US$124 per barrel, slashing Thailand’s gross domestic product growth rate this year to 1.3 per cent, the Office of the National Economic and Social Development Council now estimates.
Thailand is particularly exposed through energy imports. The country imports about 11 million to 12 million tonnes of liquefied natural gas a year, much of it from Qatar, and gas accounts for about 60 per cent of its electricity generation.
A prolonged conflict would also raise freight costs and disrupt trade flows to the Middle East and Europe, adding to pressure on an economy already struggling to find new growth engines.
Rising calls for reforms
That has reinforced longstanding calls from economists and business groups for reforms to liberalise sectors such as energy, services and digital infrastructure.
Exports, which reached about US$339 billion in 2025, up 12.9 per cent, remain a vital engine of growth for the Thai economy.
“We have been talking about the regulatory guillotine for a long time, but we haven’t really sharpened the blade,” said Burin Adulwattana, chief economist at the Kasikorn Research Center. “I think we have over 200,000 laws and regulations. That is mind-boggling.”
Anutin Charnvirakul, the current acting and expected future prime minister after his Bhumjaithai Party won the most seats in the Feb 8 election, has appointed technocrats to head the finance and commerce ministries.
While his technocratic team may be eager to push for reforms in their separate ministries, it is unclear if Anutin wants to champion a broad reform agenda that would largely facilitate foreign investment, while weakening bureaucracies and challenging local business conglomerates.
Yet, the pressure to act is growing as Thailand tries to position itself as a regional digital and innovation hub. The country attracted 36 data-centre project applications worth more than US$23 billion in 2025, according to the Thailand Board of Investment, underscoring investor appetite.
If the government is serious about promoting the kingdom as a hub for the digital/artificial intelligence economy, fintech and innovation, it will need to make it easier for foreign investors and skilled professionals to navigate the system.
Chonladet Khemarattana, president of the Thai Fintech Association, noted: “Thailand must be the fintech hub for South-east Asia, and we can do that by offering tax incentives, like a dedicated fast track for fintech.”
He added that the country’s personal income tax rates can be a deterrent in attracting foreign fintech talent, especially when compared with those in lower-tax jurisdictions such as Singapore and Hong Kong.
Some of the irritants are mundane.
Foreign executives have long complained about the 90-day reporting requirement for visa holders, which requires them to regularly confirm their presence with the immigration authorities. This was further acknowledged by Acting Finance Minister Ekniti Nitithanprapas at a recent seminar.
Ekniti, slated to be Thailand’s next finance minister, has proposed passing an omnibus law to remove such regulations and other bottlenecks to investment, although the details remain unclear.
Trade negotiations and international commitments may end up doing some of the work that domestic politics has delayed. These include the proposed trade agreements with the European Union and Thailand’s push to join the Organisation for Economic Co-operation and Development (OECD).
Dr Pavida Pananond, professor of international business at Thammasat Business School, Thammasat University, said: “The next generation of trade agreements that Thailand is actively pursuing – most notably the EU-Thailand free trade agreement and OECD membership – go well beyond traditional market access.
“They place considerable emphasis on how things are done: public procurement standards, green and sustainable manufacturing, and levelling the domestic playing field for competition. In this sense, these agreements could serve as a powerful back-door mechanism for injecting the reforms that Thailand needs but has been reluctant to confront on its own terms.”
TRENDING NOW

LTA proposes combining car COE categories, adding rebate-surcharge system
StarHub to acquire MyRepublic’s mobile business amid ongoing telco consolidation

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

