

Can China’s ‘slow bull’ market succeed?
Beijing wants to build a hybrid capital market that boosts tech self-sufficiency, financial autonomy
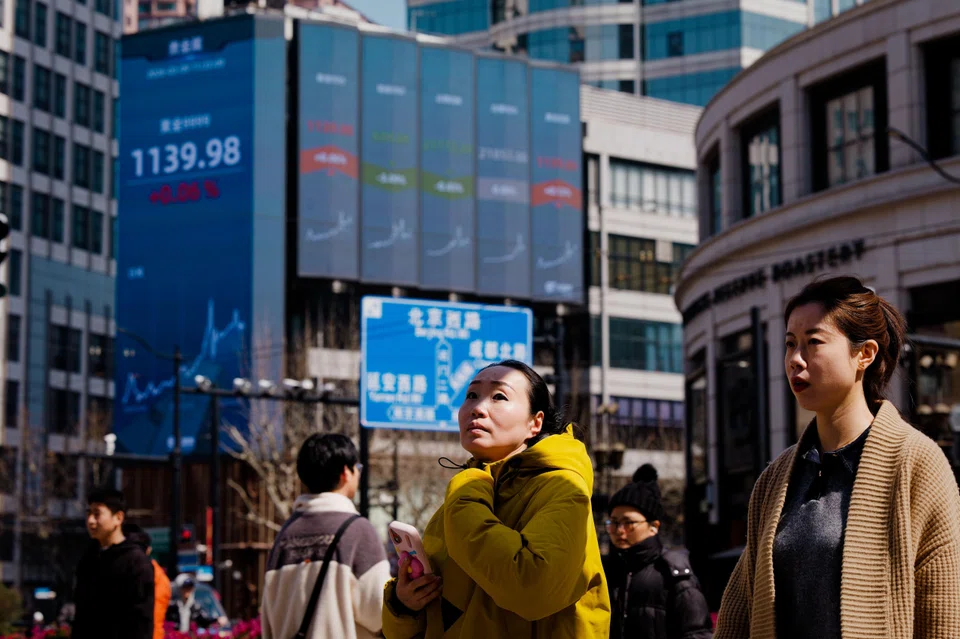
CHINA is attempting one of the most unusual experiments in modern finance: building a large capital market that serves national development goals while still delivering credible returns to investors.
Unlike the United States, where stock markets evolved primarily to maximise shareholder value and allocate capital efficiently through decentralised market forces, China’s equity market has historically functioned as a state-directed financing platform designed to support industrial policy, reform state-owned enterprises and maintain macroeconomic stability.
Beijing is now trying to transform that system into something more sophisticated – a hybrid capital market capable of generating long-term household wealth, funding technological self-sufficiency and strengthening China’s geopolitical financial autonomy.
This transformation reflects a broader strategic objective articulated by Chinese policymakers in recent years: the ambition to turn China into a “financial powerhouse”.
In this vision, capital markets are not merely mechanisms for trading securities, but also critical instruments of national power. They are expected to mobilise domestic savings; reduce dependence on Western financial systems; finance technological innovation in areas such as artificial intelligence and semiconductors; and provide households with an alternative store of wealth as the property sector weakens.
From boom-bust to “slow bull”
China’s stock market has historically been volatile. Since the 1990s, Chinese equities have experienced several dramatic boom-bust cycles that eroded investor confidence. The 2015 market bubble, for example, wiped out roughly US$5 trillion in market value within months. After 2020, markets struggled amid regulatory tightening and economic slowdown.
In response, regulators have increasingly promoted the concept of a “slow bull” market. Rather than rapid speculative surges, Beijing wants equities to rise gradually over time, generating stable dividend income and encouraging long-term investment behaviour.
To achieve this, Chinese regulators have introduced several structural reforms designed to reshape market behaviour.
One major initiative is encouraging companies to increase dividends and share buybacks. In 2025, Chinese listed firms distributed a record 2.68 trillion yuan (S$498 billion) in dividends and conducted approximately 140 billion yuan in share buybacks. By emphasising regular shareholder payouts, regulators hope to transform equities into income-generating assets rather than purely speculative vehicles.
The authorities are also tightening initial public offering (IPO) approvals. In earlier decades, Chinese exchanges frequently served as financing channels for state-owned enterprises, resulting in large waves of new listings that diluted market returns. The China Securities Regulatory Commission now exercises greater control over listing approvals.
Another priority is improving corporate governance. Regulators are strengthening disclosure standards, cracking down on insider manipulation, and enhancing protections for minority shareholders.
China is also consolidating brokerage firms to create larger financial institutions capable of competing with global investment banks.
Hong Kong as a gateway and fallback
Despite the expansion of mainland capital markets, Hong Kong remains central to China’s financial strategy. The territory functions as the primary offshore gateway linking Chinese companies with global investors.
Hong Kong offers several advantages that mainland markets cannot fully replicate: freely convertible currency financing, strong legal protections, and access to international capital pools. In 2025, the city regained its position as the world’s largest IPO market, hosting 114 new listings that raised US$37.2 billion.
Despite recent progress, China’s stock market still faces several structural challenges.
One major issue is the dominance of retail investors. Individual traders account for roughly one-third of market participation, while foreign investors represent less than 4 per cent. Retail-driven markets tend to exhibit higher volatility and more speculative trading behaviour, which undermines long-term stability.
Another problem is weak long-term performance. Between 2000 and 2025, the S&P 500 delivered total returns of roughly 418 per cent, while the Shanghai Composite rose only about 91 per cent. This performance gap reflects deeper institutional differences between the two systems.
Composition also matters. Many of China’s most dynamic private-sector firms -– particularly Internet companies -– are listed offshore in Hong Kong or the US rather than on mainland exchanges. As a result, domestic indices are often dominated by banks, industrial firms and state-owned enterprises, rather than high-growth technology companies.
Governance concerns also persist. Historically, weaker disclosure standards, related-party transactions and insider advantages created scepticism among institutional investors.
China has been trying, in a fairly deliberate way, to pull major “China concept stocks” that are listed in the US into Hong Kong as a second home market – usually through secondary listings first and, in some cases, later dual primary listings.
The goal is not necessarily to force an immediate exit from New York, but to create a Hong Kong fallback, deepen trading in a Chinese-controlled market, and reconnect those companies to mainland capital via Stock Connect.
By 2025, it is estimated that more than 75 per cent of US-listed Chinese firms by market value had either a secondary or dual primary listing in Hong Kong.
The rebalancing act
China’s capital-market reforms are closely linked to broader macroeconomic challenges.
For decades, the country’s property sector served as the primary store of household wealth. As the real estate market slows, policymakers are searching for alternative channels through which citizens can accumulate financial assets.
Equities are increasingly seen as part of the solution. Chinese households hold approximately 165 trillion yuan in savings, representing a vast potential pool of capital that could flow into stock markets if investor confidence improves.
Encouraging this shift is crucial for China’s economic rebalancing strategy. A stronger equity market could finance technological development, support consumption, diversify household wealth and reduce dependence on property-driven growth.
China’s capital-market reforms also have a geopolitical dimension. Policymakers increasingly worry about financial decoupling and potential sanctions in a more fragmented global order. Developing deeper domestic capital markets reduces reliance on Western financial systems and strengthens China’s ability to fund strategic industries independently.
The ultimate question is whether China can break its historical cycle of speculation and crashes while maintaining strong state oversight. Achieving this goal requires several structural shifts: greater institutional investor participation, improved corporate governance, deeper foreign involvement and credible regulatory stability.
If these reforms succeed, China could create a hybrid capital market combining state guidance with global investment participation.
Yet the experiment remains uncertain. Investors must be convinced that shareholder interests will not be subordinated to shifting political priorities. Without that confidence, Chinese equities may continue to trade at a persistent discount relative to Western markets.
The writer is emeritus professor of economics at Nanyang Technological University, and chairman (China) of APS Asset Management. He is former chief economist of the Singapore government, and former senior economist at the World Bank’s office in Beijing.
TRENDING NOW

LTA proposes combining car COE categories, adding rebate-surcharge system
StarHub to acquire MyRepublic’s mobile business amid ongoing telco consolidation

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

