

Schooling, Noble and financial market regulation
Comparing the Joseph Schooling drug case with the recently concluded investigation into Noble Group holds lessons for market regulators
DURING my growing-up years, I was warned I might become a drug addict if I kept bad company, listened to the wrong kind of music, let my hair grow too long, or failed to do my homework.
Singapore took a very hard line against narcotics in the 1970s and 1980s, and – for better or worse – it shaped the attitudes and mores of a generation.
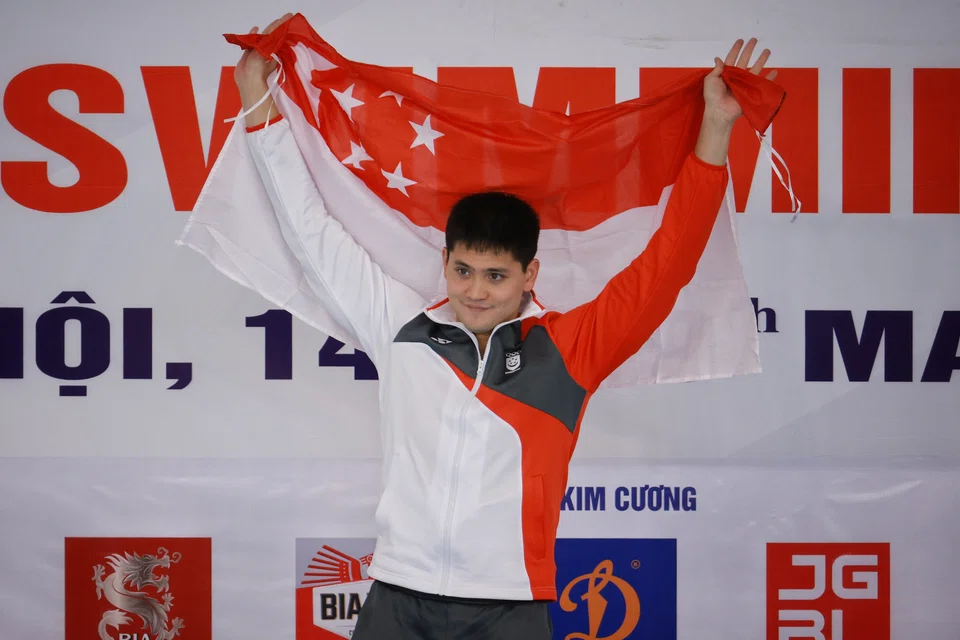
This past week, many people expressed support for Joseph Schooling after startling revelations that he had been investigated by the Central Narcotics Bureau and confessed to consuming cannabis while overseas.
Schooling is easy to forgive, of course. The Olympic gold medallist bears no resemblance to the traditional caricature of a drug abuser: sloven and wretched.
He also owned up to what he had done in a suitably contrite statement last week, and promised to make amends.
Meanwhile, cannabis use is being decriminalised around the world. And Singapore, while not following this trend, has been updating its approach to dealing with drug abuse.
Drug traffickers still face harsh penalties, including death sentences. But drug abusers are treated as people in need of help and rehabilitation rather than punishment.
In the case of Schooling, even though he confessed to consuming cannabis, he did not test positive for it. The Ministry of Defence has said he will no longer be given time off from national service to train and compete. He will also be subjected to supervised urine tests for 6 months.
The manner in which the authorities looked into Schooling’s possible drug abuse might have some investors wishing local market regulators would take a leaf from their book.
In particular, comparing the Schooling case to the recently concluded investigation into Noble Group by the Monetary Authority of Singapore (MAS), the Accounting and Corporate Regulatory Authority (Acra) and Commercial Affairs Department could hold some useful lessons.
Act decisively
Going by news reports over the past week, alarm bells went off when Schooling’s fellow national swimmer Amanda Lim was discovered to be in possession of a “weed grinder” at Changi Airport in August as she returned from the Commonwealth Games.
The authorities – quite sensibly – began questioning other national swimmers and testing them for drugs. This led to Schooling confessing that he had consumed cannabis in May while in Vietnam for the SEA Games.
The takeaway here is that market regulators should act decisively at the first sign of trouble, and not assume that a company’s board or external auditors are behaving as they should.
In the Noble case, investigations only started in late 2018 – which was more than 3 years after Iceberg Research began raising concerns about the company’s financial statements. Singapore’s regulators also did not stop Noble from tapping investors for cash in 2016.
My understanding is that the regulators did not act more quickly because Noble’s auditors had signed off on its books. This was clearly a mistake. Singapore’s market regulators should instead have assumed from the outset that Noble’s auditors were a key enabler of the financial hanky-panky that was unfolding.
Target the wrongdoers
While many Singaporeans will, understandably, be proud of Schooling and Lim, and will want to continue supporting them, the investigations into their possible drug abuse might have permanently stigmatised them.
It also seems unlikely that Schooling will be able to compete again until he completes his national service.
This might seem unfair, as both Schooling and Lim have worked hard on their swimming careers and neither of them has actually tested positive for cannabis use.
Yet, the responsibility that Schooling and Lim have taken for their own actions is admirable – and holds lessons for financial market regulators about targeting the right parties with penalties and sanctions.
In the Noble case, the authorities found that the group had applied “an incorrect accounting treatment” to long-term marketing agreements with mine owners and coal producers. This had the effect of inflating Noble’s reported earnings and net assets.
MAS has imposed a civil penalty of S$12.6 million on Noble for publishing misleading information in its financial statements.
Acra has also issued “stern warnings” to 2 former directors of a unit of Noble, while the Public Accountants Oversight Committee (PAOC) has “issued orders” against unnamed auditors from Ernst & Young.
Yet, these moves neither penalise the responsible parties nor compensate investors who might have lost money.
The S$12.6 million imposed on Noble is nothing compared with the billions of dollars investors lost as the company imploded. It will also ultimately be borne by Noble’s current owners.
On the other hand, the “stern warnings” from Acra and the “orders” issued by the PAOC really amount to a slap on the wrist to the people involved.
It would have made more sense for penalties and sanctions to be structured in a manner that targeted the responsible parties directly. For instance, MAS should have found a way to impose civil penalties on the individuals who caused Noble to apply the wrong accounting treatment to its marketing contracts.
Tough approach needed
More than anything else, Singapore’s market regulators should perhaps emulate the tough approach the country has taken to curb drug abuse.
Sitting at the crossroads of global trade flows, Singapore’s leaders have long understood the need for strict laws and aggressive law enforcement to keep drugs off its streets and its people safe from crimes linked to the drug trade.
As a global financial centre, the city-state needs a similarly robust regulatory environment that emphasises the importance of accurate and truthful market disclosures in order to maintain the confidence of investors.
If the day ever comes when even schoolboys have a sense of the public opprobrium that might befall someone who causes a company to publish misleading information in its financial statements, Singapore’s financial market regulators will know they are succeeding.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
The line between public servants and private property

