

Could Paragon soon change hands?
Selling properties and then winding down Paragon Reit returns cash to the Cuscaden Peak consortium
WHEN a consortium wins a tough takeover battle to buy a bunch of property assets, the spoils of victory can be shared by selling the assets for a profit and returning cash to the consortium partners.
In 2022, investment vehicle Cuscaden Peak – owned by a consortium comprising Hotel Properties Limited (HPL) and Temasek’s Mapletree Investments and CLA Real Estate Holdings – acquired the then listed Singapore Press Holdings (SPH), which was largely a property business after spinning off its media assets. SPH was renamed Cuscaden Peak Investments following its privatisation in May 2022, and is now wholly owned by Cuscaden Peak.
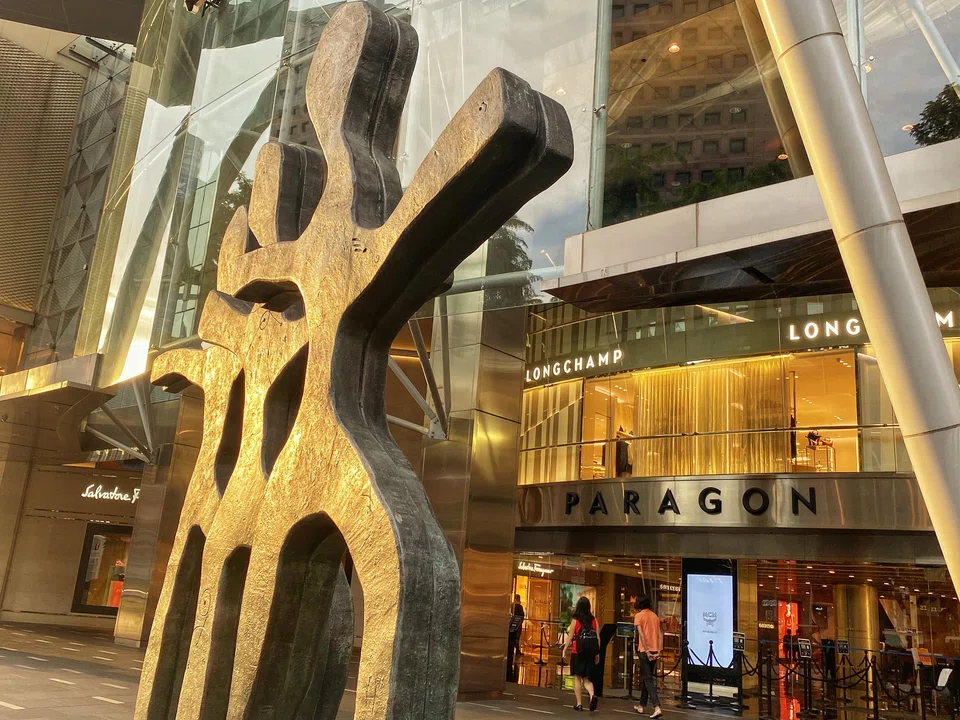
Cuscaden Peak also owns about 61 per cent of Paragon Real Estate Investment Trust (Reit) –previously known as SPH Reit – which focuses on retail properties. Cuscaden Peak Investments and Paragon Reit have since been divesting properties, while remaining inactive on the acquisitions front. Perhaps, Paragon Reit will soon sell all its properties – including crown jewel Paragon – and be wound down. This can be positive for Cuscaden Peak and the trust’s unitholders.
Actively divesting
Last year, Cuscaden Peak Investments sold three Nassim Road bungalows for a total of S$207 million. Earlier this year, Cuscaden Peak Investments and United Engineers divested Seletar Mall to Allgreen Properties for S$550 million.
Cuscaden Peak Investments also sold purpose-built student housing assets – some 8,192 beds across 19 cities in the United Kingdom and Germany – to Mapletree for £1 billion (S$1.7 billion) this year.
In July, The Business Times reported that Cuscaden Peak Investments and Kajima Development put The Woodleigh Mall up for sale at about S$800 million.
In August, Paragon Reit’s manager announced the completion of the sale of The Rail Mall in Upper Bukit Timah for S$78.5 million – 27 per cent above its end-2023 valuation. Some of the net proceeds from the sale were used to pare down debt, with the remainder distributed to unitholders via a special distribution of 1.85 Singapore cents per unit.
In November, Paragon Reit’s manager announced the proposed sale of Figtree Grove Shopping Centre in New South Wales, Australia, for A$192 million (S$168 million) or a 5 per cent premium to the property’s end-October valuation. Some of the net proceeds from divesting Paragon Reit’s 85 per cent interest in the property of around S$142 million might be distributed to unitholders.
Paragon Reit’s possible future
After the expected completion of Figtree Grove’s sale in the first quarter of 2025, Paragon Reit’s portfolio will comprise Singapore assets Paragon and The Clementi Mall plus Westfield Marion Shopping Centre in South Australia.
Sure, Cuscaden Peak loses earning high-quality management fee income from owning Paragon Reit’s manager should the trust shrink its portfolio and be wound up eventually.
However, Cuscaden Peak’s shareholders may be keen to recycle funds invested in Cuscaden Peak Investments and Paragon Reit into other opportunities. For example, HPL, which is linked to tycoon Ong Beng Seng, might want to raise funds for the possible redevelopment of its assets in the Orchard Road area – Forum, voco Orchard Singapore and HPL House.
As interest rates fall, investor appetite for investment properties could perk up; this could help Paragon Reit divest its assets at good prices.
As at end-June, Westfield Marion was valued at A$580 million, based on a capitalisation rate of 6.25 per cent. The Clementi Mall was valued at S$630 million, using a capitalisation rate of 4.5 per cent. Crown jewel Paragon was valued at S$2.83 billion, using capitalisation rates of 4.5 per cent for the retail space and 3.75 per cent for the office space and medical suites.
In the income capitalisation method, a property’s value is derived by dividing an assumed net property income by the capitalisation rate. The property’s value and the capitalisation rate used have an inverse relationship.
Should capitalisation rates stabilise and even decline, Paragon Reit could possibly sell Westfield Marion at above valuation, given its high occupancy rate and year-on-year improvement in tenant sales in the first nine months.
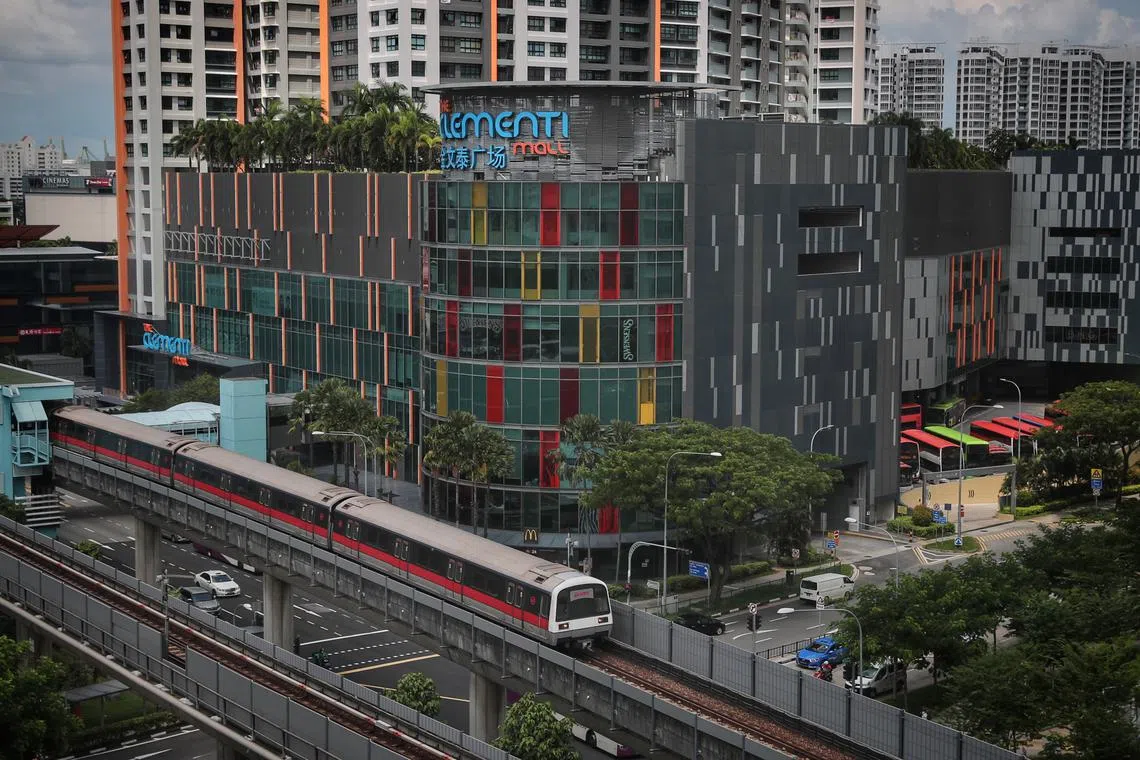
Suburban malls located in the heart of major residential towns here such as The Clementi Mall are highly sought-after. Expect this property to draw strong investor interest if it is up for sale.
While the capitalisation rates used to value Paragon are skinny, the asset might fetch a frothy price due to its premium quality and scarcity value. The mall component is arguably among the most successful retail assets on Orchard Road, where major assets are tightly held, and rejuvenation efforts could add vibrancy to the prime shopping belt.
Strong support for CICT
CapitaLand Integrated Commercial Trust received strong support when it recently bought half of Ion Orchard and the connecting underpass based on 50 per cent of the agreed property value that amounts to S$1.85 billion.
Separately, Paragon’s office space and medical suites, which are close to the popular Mount Elizabeth Hospital and Medical Centre, should be highly sought-after. Recently, Parkway Hospitals Singapore bought a strata office floor at Tong Building, located near Paragon, which is approved for medical use, for S$31.3 million or about S$4,562 per square foot.
In a crowded Reit market, Paragon Reit, which debuted on the local bourse in 2013, probably lacks the scale to compete with market leaders. And scaling up by acquisition is tricky.
Paragon Reit’s unitholders should not fear the trust possibly becoming non-existent in the near future and should instead welcome such a prospect, provided the trust achieves rich prices from asset sales. Indeed, numerous listed property trusts that struggle to gain traction with investors can consider selling assets and returning cash to unitholders.
Meanwhile, deep-pocketed parties eyeing a prized Orchard Road asset should get ready to fight over Paragon.
The writer owns units in Paragon Reit
TRENDING NOW

LTA proposes combining car COE categories, adding rebate-surcharge system
StarHub to acquire MyRepublic’s mobile business amid ongoing telco consolidation

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

