

Digital banking should not leave older customers behind
Technology should expand our choices, not reduce them
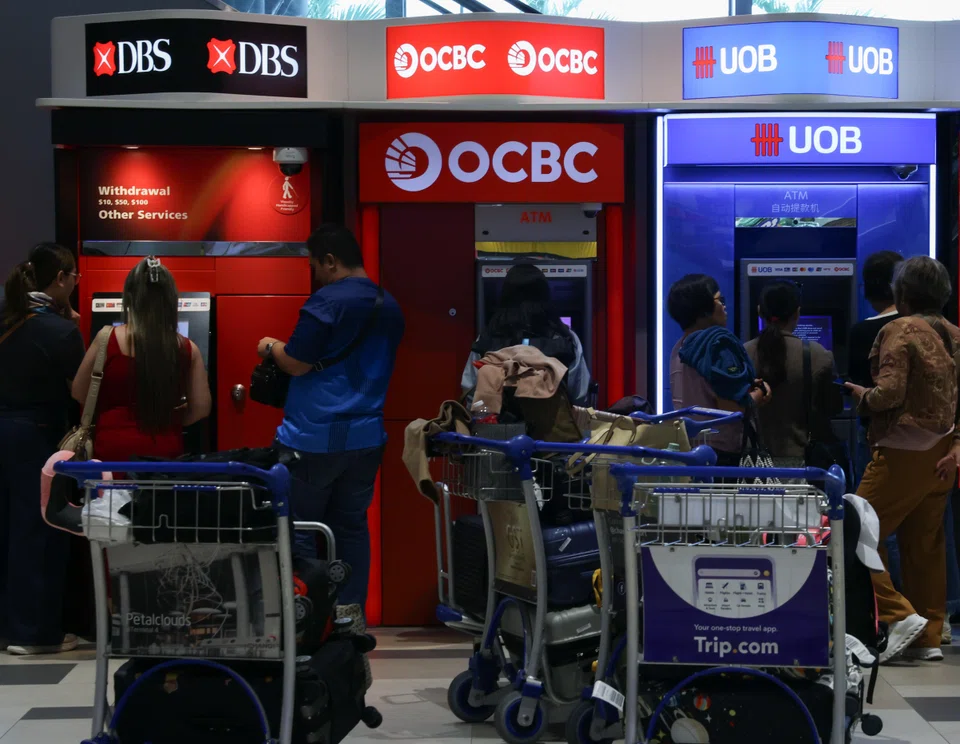
I READ with interest The Business Times report titled, “DBS, OCBC, UOB, Nets to expand ATM, cash access network after years of rationalisation” (Jun 25, 2026). I welcome this move, particularly the effort to ensure that customers who need more assistance with banking services are not left behind.
As a retiree, I have noticed how much everyday banking has changed. Many transactions that once required a visit to a bank counter can now be completed within minutes on a smartphone.
For those who are comfortable with technology, this is undoubtedly convenient. But convenience is not the same for everyone.
Some older customers may use smartphones comfortably for messaging or reading the news, but find banking apps more demanding or challenging to navigate.
Passwords, one-time passwords, two-factor authentication, QR codes and constantly changing interfaces can turn a simple transaction into a stressful experience.
There is also a practical issue that is sometimes overlooked. As people grow older, they may become less confident about making important financial transactions on their own.
Some may prefer to speak to a bank employee when dealing with a large transfer, a complicated account matter or a problem they do not fully understand.
This does not mean banks should reverse digitalisation. Banks need to improve efficiency and manage operating costs, while customers should also be encouraged and supported to become more digitally confident.
Ultimately, digitalisation should expand our choices, not reduce them.

For routine transactions, digital banking may be the best option. For more complex or sensitive matters, however, there should still be a reasonable avenue for face-to-face assistance.
This is especially important for older customers who may not have family members who can readily help them.
A truly inclusive banking system should therefore measure success not only by how many transactions can be completed digitally, but also by whether customers who struggle with technology can still access help with dignity.
In our rush towards a smarter and more efficient society, I hope we do not forget a simple principle: Technology should serve people, not force everyone to adapt at the same pace.
Digital banking can make life faster. Human assistance can make it less intimidating. Singapore needs both.
Chua Soon Keong
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

OCBC sheds S$8 billion in value as shares close nearly 6% down; analysts cautious on banks
Deal between tycoon friends sparks scrutiny of Philippine power sector

