

If the US economy is robust, why is the yield curve still inverted?
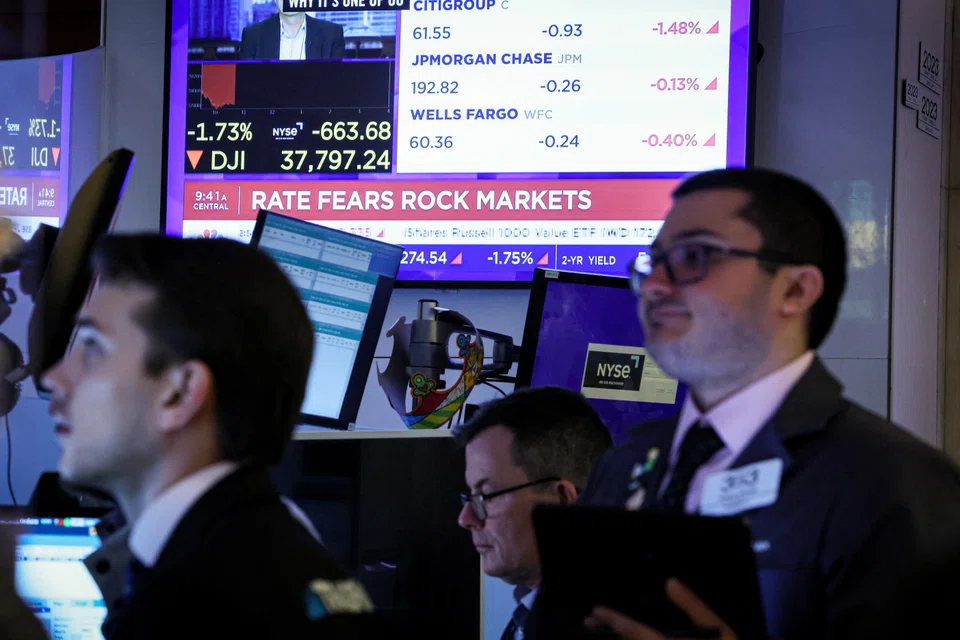
BY MOST accounts, the US economy is chugging along nicely and has, at the very least, avoided falling into a recession. If so, then why has the US Treasury yield curve been inverted for almost two years, a phenomenon that has several times in the past proven to be the precursor to an economic slowdown?
In a March research note, Deutsche Bank noted that since early July 2022, the part of the Treasury yield curve that plots two-year and 10-year yields has been continuously inverted, meaning that short-term bonds yield more than longer ones. That exceeded a record 624-day inversion in 1978, said Deutsche Bank.
Currently, the two-year Treasury bond yields are close to 5 per cent while the 10-year bond yields are at about 4.66 per cent. In other words, a month after the release of that report, the US yield curve is still inverted, with the difference being about 34 basis points.
This is seen as abnormal because investors normally demand higher yields when they invest their money for longer periods, as more time means more risk. A normal yield curve is therefore one where yields rise along the curve as bond maturities lengthen.
History suggests that when the opposite occurs – that is, when short-term bonds yield more than longer-term bonds, as is the case now – this is a warning signal for the economy, even potentially heralding a recession.
Inversion usually results when the Federal Reserve tightens the availability of credit, which it has been doing since 2022 to combat rising inflation. As companies find it more expensive to maintain inventories, they cut back on production and lay off workers, while manufacturers reduce their orders for raw materials. If the Fed over-tightens, a recession results.
Another line of reasoning is that inversion shows that investors are moving their money away from short-term bonds and into longer-term ones. This suggests that the market as a whole is becoming more pessimistic about the economic prospects for the near future.
However, far from facing a recession, the US economy’s current outlook is the exact reverse, with expansion being possibly too robust – at least according to the International Monetary Fund, which in April raised its 2024 US growth forecast by 0.6 percentage point to 2.7 per cent, while describing the economy as in danger of becoming “overheated”.
One reason for the economy’s strength is that, during the Covid-19 pandemic, there was a significant amount of fiscal stimulus in the form of government payments to individuals and businesses. This has helped boost the economy.
On the consumer side, steady spending, buoyed by the strength of the labour market, has helped to keep the economy on a growth trajectory. On the corporate side, government aid has meant that most companies have been operating with reasonably strong balance sheets and so have not had to issue new debt at the current elevated levels.
According to Deutsche Bank, another factor behind the economy’s strength is high consumer savings as the economy exited the Covid-19 pandemic, which provided a buffer against rising borrowing costs.
“However, an inverted yield curve should ultimately be a significant headwind for an economy, as capitalism works best when there is a positive return for taking more risk with lending and investments further out the curve,” said Deutsche Bank.
An inverted yield curve has accurately foreshadowed all 10 recessions since 1955, according to data from the Federal Reserve Bank of San Francisco, with only one false positive in the mid-1960s. It remains to be seen whether this will still be the case this time round.
TRENDING NOW
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion
Cliff Tan has 7 million followers and a 4-month waitlist. Why won’t he expand his business?

Could stablecoins be the future of money?
From finance aspirant to Asean CEO: TUV SUD’s Jonas Strahberger on finding people who believe in you

