Inflation is the lesser evil
As hard as higher prices are to swallow for many households, rising unemployment is the greater risk in the US
A RECORD-BUSTING stock market has done little for the prospects of most middle and working-class Americans, who are falling behind as the labour market stalls and prices rise for the essentials. The way out of the hiring rut is significantly lower borrowing costs for businesses and consumers, but these have the potential to stoke painful inflation once again.
“We have a situation where we have two-sided risks, and that means there’s no risk-free path,” chair Jerome Powell conceded after the Federal Reserve lowered its benchmark interest rate last week.
As hard as higher prices would be to swallow for many households, rising unemployment would be worse. This difficult reality threatens to widen the gap between families already struggling to make ends meet, and wealthy Americans who benefit most from buoyant stocks.
One useful barometer that policymakers have to judge the path of inflation is the rate-sensitive housing market. Its current malaise means that inflation is unlikely to quickly run away from the Fed, outside of tariff-induced pressures that the central bank should look through. The return of unhealthy increases in house prices would be an early warning that it is time to halt policy easing.
It is no secret that the labour market slowed in 2025. The economy added an average of just 27,000 jobs a month over the past four months, and the overall unemployment rate crept up to 4.3 per cent from 4 per cent in January.
There is debate about how much of this slowdown is due to reduced immigration, so it is worth noting that the percentage of workers experiencing zero wage growth has been ticking higher over the past two years.
In September, 13.6 per cent of workers got no wage increase, according to the Federal Reserve Bank of Atlanta, a rate similar to what we saw in 2019. But in 2019, the Fed’s preferred measure of inflation was running at 1.5 per cent compared with 2.9 per cent today – flat wages are more painful now while inflation is running hotter. Wage gains for those on the lowest incomes now lag all other cohorts.
Inflation has been hovering between 2.5 per cent and 3 per cent for the past year, but the composition of where the pressures are coming from has changed.
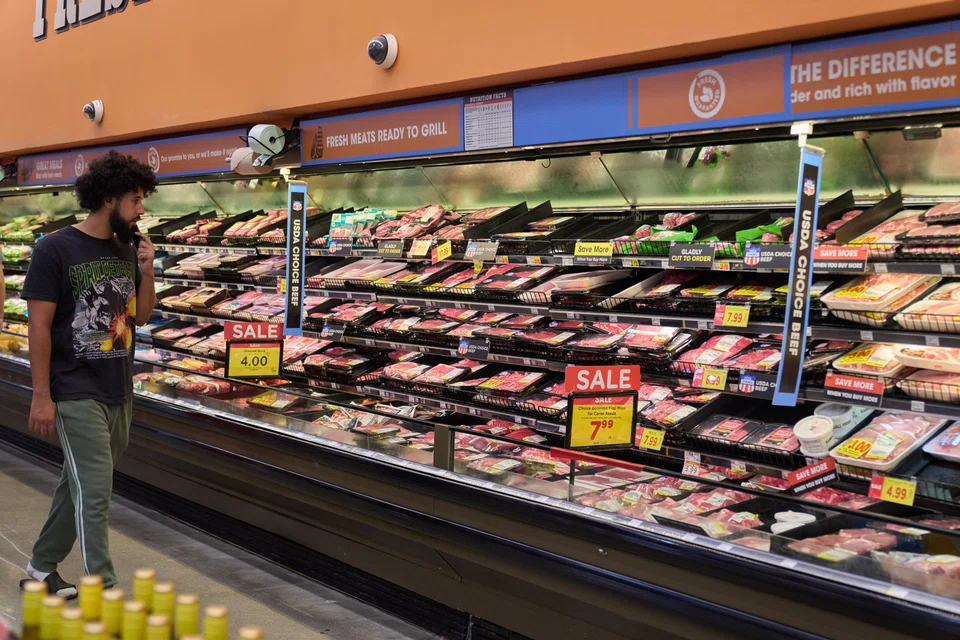
Food inflation is on the rise again; after bottoming a year ago, the food component of the consumer price index has climbed 3.2 per cent over the past year. Tariff-impacted beef and coffee inflation are rising by double digits.
And while petrol prices have been stable, electricity prices have been surging as demands from artificial intelligence strain the energy grid. In many parts of the country, there have also been painful increases in home insurance costs.
For middle-class homeowners, these pressures are compounded by falling home values in many regions and an inhospitable market for those looking to sell. Conversely, this sluggishness implies that the Fed has some room to manoeuvre.
Nationally, home prices have fallen for four consecutive months, according to the S&P Case-Shiller US National Home Price Index. In June, the most recent month for which data is available, home prices declined on a seasonally adjusted basis in 17 of the 20 metro areas tracked by the Case-Shiller indexes.
As home values decline for a growing number of families, would-be purchasers still do not have the kind of affordability that would make buying attractive.
Consumption growth, on the other hand, has remained resilient, as evidenced by August retail sales data that beat analyst expectations. The bifurcation between a cooling labour market and resilient consumption speaks to the ever-growing importance of high-income consumers keeping the economy on track.
Analysis from Moody’s Analytics showed that the share of consumption from the top 10 per cent of the income distribution rose to its highest level since at least 1989 in the second quarter of the year. For consumers without financial assets, the surge in “buy now, pay later” lending may speak to households using non-traditional forms of borrowing to stay afloat.
Even with a softening labour market, sticky inflation and a dysfunctional housing market, the wealthiest Americans still have growing financial portfolios to keep them spending. Recent data from the Fed showed that the net worth of American households increased by US$10 trillion between Q2 2024 and Q2 2025.
Of that, US$8 trillion, or 80 per cent, was attributable to corporate equities, mutual fund shares and “pension entitlements”, which include accounts such as individual retirement accounts – in other words, the increase in financial markets. Those assets are largely held by the wealthiest Americans and do not do much for the working and middle classes.
The best hope for American workers is lower Fed rates. Cheaper credit to buy homes, autos and service consumer debt would relieve some of the financial pressure on consumers, and give the labour market a much-needed boost.
The trick for the Fed will be finding some magic level of interest rates that provide relief without reigniting the kind of inflation policymakers spent the past several years getting under control. BLOOMBERG