

Navigating Iran war complexity: Asia businesses lose big in worst-case scenario
Four different plausible futures could pan out, with the worst being a ‘regional firestorm’
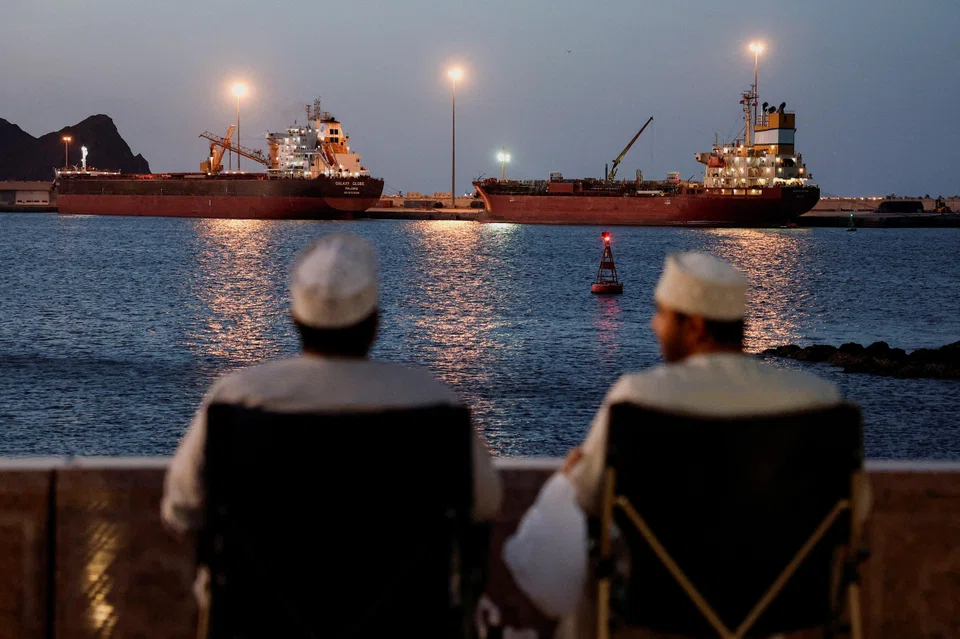
AT THE start of the US and Israeli military campaign, it was widely expected that the bombing might last only days. Those initial assumptions have changed to at least weeks, with the conflict’s tragic and increasing death toll.
A recent key development that may extend the conflict is the decision of Iran’s Assembly of Experts to anoint Mojtaba Khamenei, son of the late Ayatollah Ali Khamenei, as the nation’s next supreme leader.
This signals that regime hardliners in Teheran are probably still firmly in charge, for now at least, with reformists still frozen out. US President Donald Trump declared himself “not happy” with the decision.
Given the huge uncertainty surrounding the US and Israeli military action, a growing number of firms in Asia and beyond are employing scenario planning to think through the campaign’s plausible outcomes and implications. The goal is to build corporate preparedness and resilience for what might be even more unpredictable times ahead.
There could be huge economic volatility. On Monday (Mar 9) for instance, Brent crude prices whipsawed, first exceeding US$119 a barrel, but later sliding below US$90.
In this economic and political tumult, a key question firms are asking is how long the campaign will last. Trump has sent mixed signals, including his Monday comments that the war is “very complete”, despite previously saying it would last some four to five weeks, and that he was considering ground troops.
There are wider uncertainties, too. Will the instability continue to be – largely – contained to Iran or potentially extend much more broadly to the Gulf states?
To be sure, Iran has been hitting the Gulf states from the start of hostilities and blocking the Strait of Hormuz, seeking to maximise international pressure on Israel and the US to stop the bombing. But none of the Gulf states have retaliated in a major way to date.
Key scenarios
Uncertainties over the length and geographical footprint of the war give rise to at least four scenarios, which have significantly different implications for the global business environment. The Middle East “regional firestorm” scenario represents the most serious “stress test” for many firms to contemplate.
The next few weeks may well combine some features of all four scenarios. However, each scenario represents a plausible future, providing guiding posts for corporations in Asia and beyond navigating the huge complexity on the horizon, even if the situation does not unfold exactly as outlined.
1. Regime in ruins: This is centred on a war ending in weeks, perhaps even before the end of March. A much weakened form of the regime remains in place, decaying into the future. Its grip on power may be precarious with limited military capabilities, and without widespread domestic public legitimacy, it may eventually collapse from the inside.
2. Regime change: In a multi-month war where the conflict remains largely confined to Iran, the Iranian regime ultimately collapses relatively benignly. The change of regime, under a transitional leadership, would probably be very bumpy, but has the potential to be broadly welcomed.
3. Regional firestorm: In many ways the worst case scenario, especially economically, a longer war triggers the collapse of the regime in a chain of events that destabilises not only Iran, but also the wider region. This brings about more significant instability in Gulf Arab states and potentially beyond.
4. Resilient regime: In the final scenario, the regime survives after a short war, remaining strong enough to be a significant irritant to the US and Western allies in coming years. Ultimately, this may seem a deja vu of the wars in 1991 and 2003 in Iraq, with further military action led by the US and/or Israel in the future.
While all scenarios are possible, the two that appear most likely at the time of writing are “regime in ruins” and “regime change”.
Although Iran has significant scope for further retaliation in the Gulf region and beyond, which could yet change the landscape, its missile and wider drone attacks have so far been limited with no game-changing disruption to the Gulf states, despite the tragic loss of life.
The business impact of the conflict could still be hugely significant, especially if the US and Israel extend the campaign for a longer rather than shorter time. While many people are focused on the often-erratic public declarations of Trump, Israel – a significant independent operator with vast military assets – remains part of the operation.
The military campaign is relatively unpopular with the US public but many in Israel deem it necessary. There is an outside possibility that, even if the US decides to pause or end its operations, Israel could continue for at least a short time.
Israeli Prime Minister Benjamin Netanyahu’s Likud Party has been rising in the polls, and the next legislative elections must take place no later than this October.
Economic impact growing, with Asia a big loser
Some forecasters indicated only limited impact at the start of the war. On Mar 1, for instance, Oxford Economics forecast that “higher energy prices from a moderate disruption in the Strait of Hormuz would only knock 0.1 per cent off world gross domestic product growth this year”.
However, the scale of the potential impact is growing in forecasts. While the conflict will mostly have downside consequences, there will be some gainers. These include large net energy exporters outside the Middle East, such as Norway, Russia and Canada, whose freedom to sell overseas is largely unaffected by the war.
Asia will be a big loser as a region, alongside Europe, given their vulnerability to an energy shock, including their large amounts of energy imports and geographic proximity to the Middle East. Energy imports account for a large share of GDP for economies such as South Korea, India, Taiwan, Japan, China, France, Germany and the UK.
So it is no coincidence that the Indian rupee recently hit a more-than-half-century low against the US dollar. Meanwhile, the South Korean stock market fell 20 per cent.
In Asean, foreign ministers released a statement on Mar 4 amid growing concern at the crisis. Some of the bloc’s governments are already acting. Thailand has set temporary price caps on diesel. Exporters are being assisted in managing insurance and freight costs.
These new moves build on extensive measures already in place across much of the region. India, for instance, spends more than US$32 billion annually subsidising retail energy prices.
Taken together, the uncertainty from the Iran war is a massive headache for firms in Asia and beyond. While many corporations are hoping for the best, a growing number are also preparing for the worst.
The writer is an associate at LSE Ideas at the London School of Economics
TRENDING NOW
Companies still in search of AI use cases with worthwhile ROI, says Broadcom’s CEO
Beauty World Plaza up for collective sale for S$165 million
Trouble in paradise: Bali runs low on fuel, sparking long lines at pumps
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

