

A new lease of life for Singapore’s legacy tax incentives
Policymakers should consider the value in leveraging and re-purposing some of Singapore’s legacy tax incentives in the coming year.
HELLO World may have been the theme song of the recent Olympics held in Paris, but in the realm of international taxation, another “bonjour le monde” took centre stage in the French capital.
On Sep 19, 2024, the Organisation for Economic Co-operation and Development (OECD) hosted a signing ceremony to facilitate the implementation of the Subject to Tax Rule (STTR). This marked a significant milestone in the Base Erosion and Profit Shifting (BEPS) framework, delivering on the OECD’s objective of reforming international tax rules for a stronger and fairer global tax system.
Overview and mechanics of the STTR
According to the OECD, the STTR is “designed to help developing countries – notably those with lower administrative capacities – to protect their tax base”. It is a key feature that allows participating countries to limit tax treaty benefits or impose withholding tax at source (that is, in the payer’s jurisdiction) where certain items of income are not subject to a minimum tax rate.
The STTR is the last segment of the OECD’s Pillar Two global minimum tax package to be finalised, and has attracted less discussion compared with the Global Anti-Base Erosion (GloBE) Rules and Domestic Top-up Tax (DTT).
However, this does not mean that the future implementation of STTR will not impact Singapore’s tax policies. Interest, royalties and rent for industrial, commercial or scientific equipment are set to become examples of relevant income items for STTR purposes.
When such income is taxed in Singapore at a rate below 9 per cent (the minimum rate currently specified in the rules), the potentially higher source-country withholding tax amount facilitated by STTR could adversely impact Singapore-based recipients of such income.
This could explain the posturing observed from the tax changes announced during the Singapore Budget 2024 speech earlier this year.
Recent tax reversals could pave the way for more
Budget 2024 saw the introduction of additional concessionary tax rate tiers for certain tax incentives, including a 10 per cent tier for the aircraft leasing scheme (ALS).
The rate for the ALS preceding this was based on a single concessionary tax rate of 8 per cent on income derived from the leasing of aircraft or aircraft engines and qualifying ancillary activities. The additional 10 per cent tier means that Singapore has now pivoted back to its earlier approach of having multi-tier concessionary tax rates for the ALS.
This strategic pivot may very well be a masterstroke in helping local-based aircraft lessors mitigate additional tax costs that might otherwise stem from the STTR (higher withholding taxes at source in the lessees’ jurisdictions on account of Singapore’s otherwise 8 per cent ALS tax rate).
A similar approach could be considered beyond the aviation financing space.
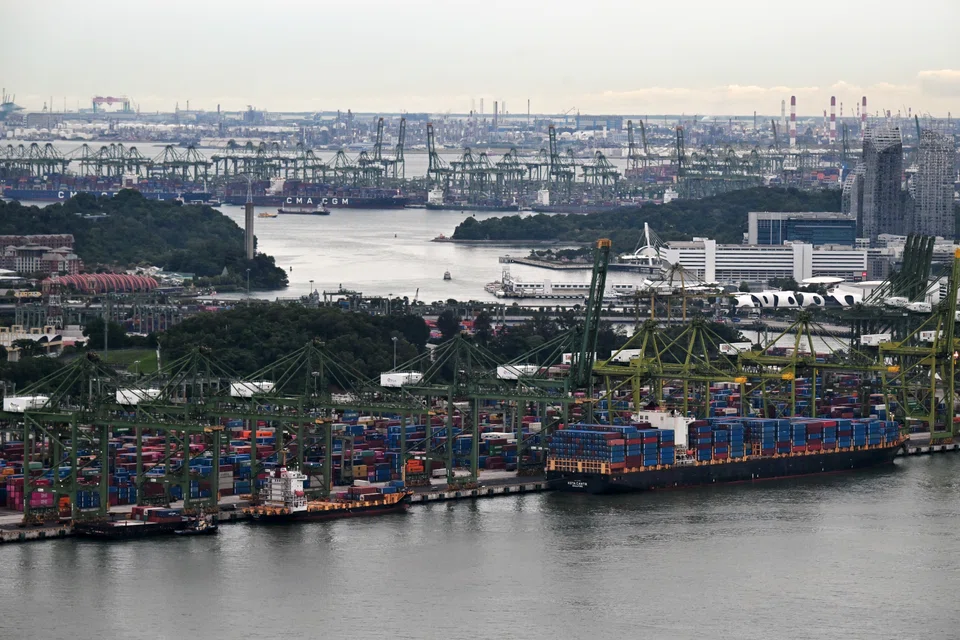
If we look into the field of shipping, it would make sense to allow Maritime Sector Incentive-Maritime Leasing (MSI-ML) taxpayers to opt for a 10 per cent tax rate, even if their income qualifies for the tax exemption or 5 per cent tax rate under the present award parameters. This would enable Singapore to sharpen its edge in the wider shipping ecosystem, including ship financing.
Indeed, tax optionality may be a major buzzword for MSI players in Singapore this year. The introduction of the alternative net tonnage basis of taxation (or “tonnage tax”, which offers a substitute for the current income-based approach to calculating corporate taxes due) could potentially benefit various businesses in the sector, such as MSI-ML taxpayers that lease out qualifying ships, which includes oil or drilling rigs.
Yet, the business case for examining Singapore’s longstanding inventory of tax incentives and re-purposing some of the legacy ones continues to grow – perhaps even more so – for the maritime sector.
A recent piece in The Business Times, “Riding the winds of change: Singapore companies seize offshore wind opportunities in the UK” highlighted how some Singapore-headquartered companies are doubling down on investments in specialised vessels for the offshore wind industry.
Many of the assets used in the offshore sector are very costly and are often leased in. The use of tax incentives could help Singapore-based lessors price their leases at more competitive rates.
Prior to Jan 1, 2016, Singapore’s tax law provided a 10 per cent concessionary tax rate on income derived by a leasing company for offshore leasing of machinery and plants.
Hence, it came as a surprise to some when this asset leasing incentive was withdrawn. Within the marine and offshore sector, those operating in the oilfield services space or renewables or offshore wind markets may benefit from the re-introduction of such an incentive.
For instance, if the assets involved or leased are so highly specialised that they do not fall within the definition of “ships: or “containers” for Singapore tax purposes, or if the lessor has economic substance which is insufficient to meet the required spending commitments under the respective MSI-ML awards, this asset leasing incentive could potentially come into play due to its more broadbased nature.
Possible drawbacks and the way forward
Critics of the idea of re-introducing some legacy tax incentives may say that this runs counter to earlier moves to streamline Singapore’s extensive suite of tax incentives.
Indeed, the authorities did say back in 2015 that withdrawing the asset leasing incentive would “simplify our tax regime”. However, whether this simplification theme remains relevant amid today’s volatile international tax environment is debatable.
A key question to consider is whether this asset leasing incentive can comply with BEPS Action 5 expectations. Can it be classified as “not harmful” during peer reviews that are part of the Forum of Harmful Tax Practices’ ongoing monitoring, which includes checks on financing and leasing schemes?
It may not always be possible to develop new strategies to bolster Singapore’s tax incentive framework.
Therefore, even as we welcome tweaks to tax incentives such as the tonnage tax alternative in 2024, policymakers should consider the value in leveraging and re-purposing some of Singapore’s legacy tax incentives in the coming year.
The writers are from Deloitte Singapore. Daniel Ho is tax and legal leader; Loh Eng Kiat is tax partner.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
New launch or resale unit? Here’s a guide for homebuyers
The lesser-known prospects in the Asian chipmaking supply chain
Cliff Tan has 7 million followers and a 4-month waitlist. Why won’t he expand his business?

