Singapore Airlines faces a tough test over Air India’s record losses
The true test for management will be the gruelling task of convincing its shareholders to bite the bullet
[SINGAPORE] Looking at the latest news emerging from Air India, it is understandable why a growing group of investors might want Singapore Airlines (SIA) to cut its losses, pack its bags and abandon its Indian ambitions.
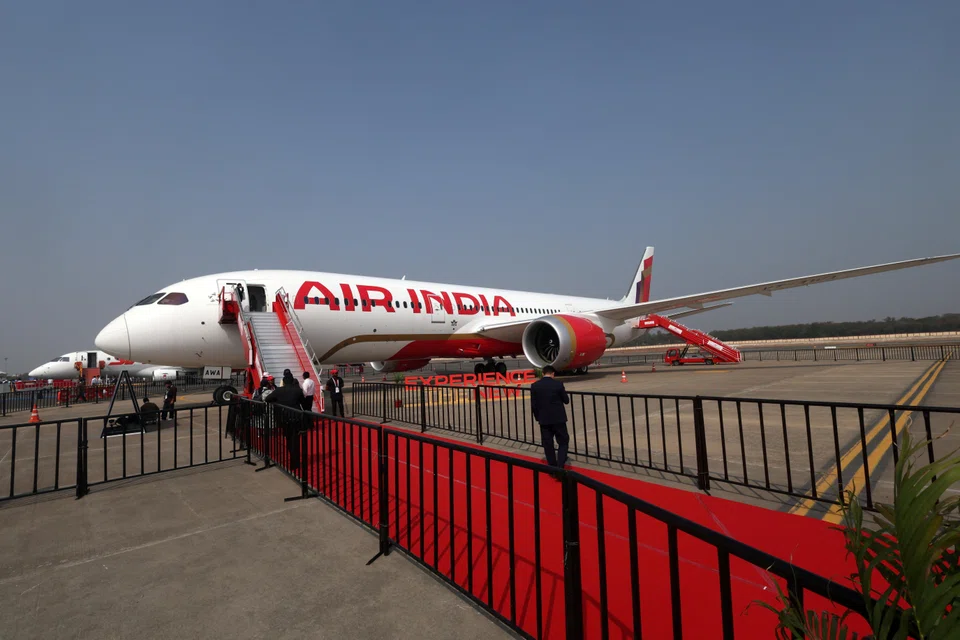
The trigger for this frustration stems from Air India’s bleed of an estimated 220 billion rupees (S$3 billion) for the full year ended March – materially higher than previously expected.
The record loss is said to have prompted the company to seek additional aid from controlling shareholder Tata Group, as well as SIA, which owns 25.1 per cent of the carrier.
For retail investors who hold SIA shares for steady dividend yields, these figures are deeply alarming.
SIA currently trades at a dividend yield of 5.5 per cent. Over the past year, the stock price has declined 3 per cent to close at S$6.39 on Thursday (Apr 23). However, it has managed to eke out a total return – with dividends reinvested – of 2.7 per cent.
When SIA and Tata formally agreed to merge Vistara into Air India, SIA’s ticket to secure a 25.1 per cent stake was priced at a seemingly manageable S$360 million. Today, that initial entry fee looks like a mere down payment on a cash-hungry black hole.
More turbulence ahead?
Air India is caught in a perfect storm of operational mistakes and geopolitical bad luck.
Its network is heavily exposed to the Middle East, a region currently fraught with airspace disruptions.
Compounding this is the fallout from the deadly Boeing 787 Dreamliner crash in June last year, which has affected international capacity.
Add to this a glaring lack of pricing power. Air India cannot pass its soaring fuel and operating costs on to a highly price-sensitive passenger base.
Furthermore, the carrier is attempting to rebuild its fleet right now. The airline has committed to an aggressive fleet renewal programme, boasting an order backlog of 540 new Airbus and Boeing aircraft.
Capital expenditure of this size requires overflowing pockets. The inescapable conclusion is that SIA will face a much larger capital call than anyone in the boardroom initially modelled.
As if the staggering financial losses were not enough to spook investors, Air India is now facing a leadership vacuum as chief executive officer Campbell Wilson submitted his resignation earlier this month – before his five-year term was due to end in 2027.
While he will stay on for a transition period, his sudden exit leaves the carrier rudderless at the worst possible time. Finding a new captain willing to take on deep structural losses and intense regulatory scrutiny will be incredibly tough.
For SIA, this unexpected executive churn adds another layer of deep risk to an already messy venture.
SIA chief executive officer Goh Choon Phong and Tata Group chairman Natarajan Chandrasekaran were reported to have met in Mumbai last week to discuss a funding road map for Air India and the search for a new CEO.
SIA’s own operations out of Changi are running smoothly. But the massive financial drag from Air India threatens to eat into its dividend payout.
For a shareholder base that demands reliable returns, the argument is simple: stop subsidising India’s national carrier, defend the dividend, and focus on the fortress at home.
Strategic surrender?
SIA, though, possesses the clear liquidity to weather an unexpected cash call from the subcontinent without instantly sacrificing its dividend policy.
The airline is sitting on a formidable cash hoard of more than S$8 billion, built up during the post-pandemic travel boom.
The money is there. The real question is whether the board has the courage to deploy it to defend a long-term strategic prize.
Selling off the Air India stake now would represent a massive strategic surrender for SIA. To understand why, one must look past the immediate pain of the S$3 billion loss and acknowledge the brutal geographic reality of the aviation business.
In the global scheme of things, SIA has a limited domestic market that is little more than a rounding error. To achieve any meaningful growth, it requires a second engine.
India, with its exploding middle-class demographic and massive global diaspora, represents an aviation market that SIA cannot afford to ignore.
More crucially, walking away from Air India means handing a strategic victory to SIA’s most formidable adversaries: the Gulf carriers.
Emirates and Qatar Airways are currently preoccupied with the Iran conflict on their doorstep. But when peace resumes, so too would their commanding grip on Indian transit traffic.
It is also worth remembering that SIA is not fighting this battle alone. The capital expenditure for 540 aircraft is a staggering financial burden. However, SIA is only on the hook for a quarter of it. The remaining 74.9 per cent is shouldered by the Tata Group.
Often considered India’s largest and most influential conglomerate, Tata provides the ultimate shield. It possesses the deep pockets, the bureaucratic navigational skills, and the domestic clout that SIA historically lacked when it embarked on its overseas ventures.
The groundwork being laid today – the painful integration and the massive fleet orders – is building a competitive moat for the future. And it would be a pity to abandon a multi-decade turnaround project just as the new aircraft arrive and the hardest integration work is underway.
Indeed, SIA appears to be doubling down on its Air India strategy. Singapore’s flagship carrier is said to have moved some of its employees into Air India, placing its executives in key roles across flight operations, engineering and maintenance in recent months.
These are areas where SIA has long been considered a global benchmark, and the move to a more hands-on presence could help accelerate Air India’s turnaround.
Ultimately, the strategic rationale holds up. The true test for management will be the gruelling task of convincing its shareholders to bite the bullet.
SIA’s leadership will have to use every bit of their influence to make the market see that swallowing this bitter pill today is the only way to secure the airline’s empire for the next decade.