

De-dollarisation and shifting safe havens
Markets are beginning to price in a world of persistent policy risk, stretched fiscal metrics and shifting trade dynamics
[SINGAPORE] Donald Trump’s second term as US president has reasserted America’s economic might with a mix of bombast, brinkmanship, and a brand of economic nationalism that is as familiar as it is destabilising.
The recent passage of expansive tax reform has raised serious questions about US debt sustainability; the Congressional Budget Office projects a deficit of US$1.9 trillion for this fiscal year alone, with federal debt forecast to climb to 118 per cent of gross domestic product by 2035.
Moody’s downgrade of the US credit rating to Aa1 is not just a symbolic fall from grace; it marks the twilight of the era of “risk-free” US Treasuries. Elevated yields at the long end of the yield curve reflect investor anxiety over the sheer scale of US refinancing needs.
Trump’s tariff war aims to fire on two fronts – checking Chinese expansion and plugging a widening US fiscal gap. But here, too, the math is sobering. Even under the most aggressive assumptions – universal tariffs at 20 per cent – the projected revenue gain is a modest US$185.2 billion, barely sufficient to cover annual debt interest payments.
Divergence, de-dollarisation and defensive shifts
As we enter the third quarter of 2025, three themes dominate the investment landscape: pragmatic de-escalation in tariff tensions, divergent equity performance, and fiscal headwinds which are negative for government bonds and the US dollar – but positive for gold.
The abrupt de-escalation of US-China tensions has caught markets off guard. After months of hawkish rhetoric, a US-China trade truce is finally under way. With Republican rifts in his backyard, waning poll numbers, and the need to refinance US$7.8 trillion in debt, Trump’s embrace of progressive policies underlines efforts to reframe Republicans as the working-class party ahead of the 2026 midterms.
Nevertheless, the damage has been done. Despite rising Treasury yields, the dollar tumbled 10.8 per cent in the first six months of 2025, underscoring the growing scepticism about the greenback’s long-term viability as the global reserve currency.
Since “Liberation Day”, gold, long considered a hedge against inflation and uncertainty, has decoupled from its traditional inverse correlation with bond yields. Central bank demand for gold reached 1,045 tonnes in 2024 – 121 per cent above the 2010 to 2021 historical average – signalling a broader de-dollarisation trend that extends beyond geopolitics into fundamental shifts in reserve management.
Our strategic positioning reflects these tectonic shifts. US equities remain slightly underweight, primarily due to overstated earnings expectations (11 per cent versus 7 per cent in other developed markets, or DMs) and the dollar’s structural weakness. Still, pockets of strength remain. Technology, bolstered by the resilient demand for artificial intelligence (AI) and Nvidia’s recent strong guidance, offers a compelling case for selective exposure.
Europe, by contrast, benefits from relative fiscal sustainability and resurgent defence spending. Asia ex-Japan remains a deep-value play, with valuations at a 33 per cent discount to DMs and earnings growth forecast at 12.4 per cent.
In fixed income, stagflation risks and long-end volatility have risen. Spikes in long-duration Treasuries and Japanese government bond yields reflect sticky inflation unlikely to subside given the tariff uncertainties, labour market constraints, and money supply growth.
On both a three-month and 12-month basis, we downgrade DM government bonds to neutral as higher long-term yields and curve steepening are expected. In credit, stay with quality in the A/BBB bucket and adopt a duration barbell approach with two to three-year and seven to 10-year investment-grade exposure.
We like US Treasury inflation-protected securities, capital securities, and short-duration quality credit. Our two to three-year CIO Liquid+ strategy remains well-positioned for stagflationary conditions. We remain less convinced on high yield, given the spread-widening risks.
In private assets, seek opportunities in middle-market buyouts and growth private equity. Middle-market companies possess lower purchase multiples, providing room for larger future value expansion. Besides, the requirement for lower leverage in middle-market deals augers well for their outlook in a high interest rate environment.
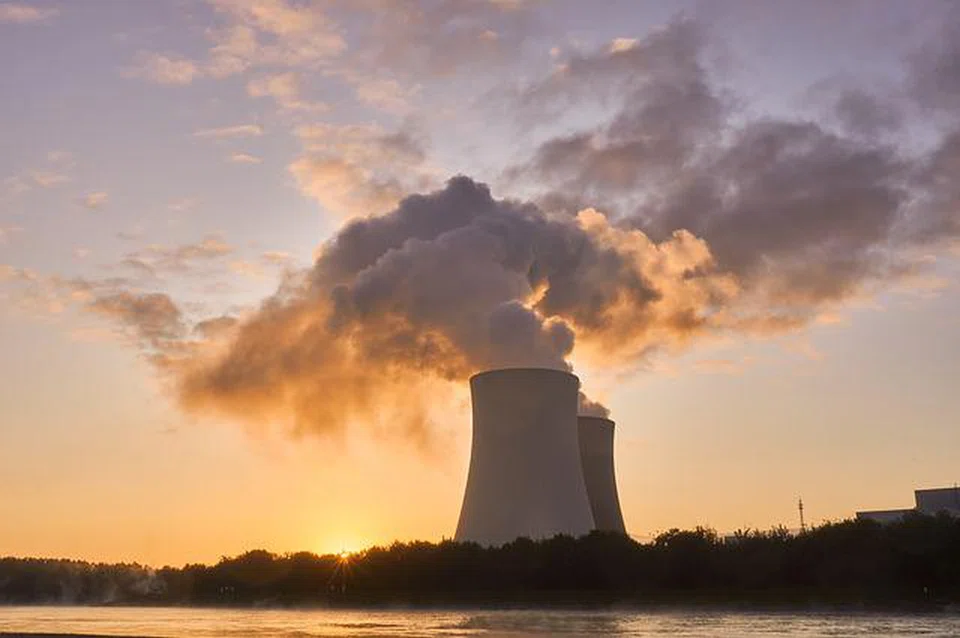
Nuclear energy: Igniting Prometheus’ atomic flame
If the first half of the 21st century has taught investors anything, it is that the future often looks unthinkable – until it happens. Nowhere is this more evident than in nuclear energy. Once a byword for risk and controversy, nuclear power is quietly re-emerging as a compelling investment thematic, driven by a perfect storm of geopolitical, environmental, and technological tailwinds.
First, let us consider the state of energy security. With ongoing conflict in the Middle East, tensions in Europe, and the weaponisation of trade routes, dependence on fossil fuels has become a strategic liability. Supply chains built on the whims of energy cartels or vulnerable choke points are no longer tenable. While the nuclear supply chain remains imperfect, it offers a viable avenue for energy diversification.
Second, climate imperatives are accelerating policy momentum. Carbon taxation will eventually hit the bottom lines of companies, shifting energy demand towards more sustainable forms of power generation. Nuclear power is uniquely placed to deliver consistent, zero-emission energy at scale. For policymakers seeking to hit net-zero targets without sacrificing industrial productivity, nuclear is becoming not just acceptable, but essential.
Third, AI and the growing need for processing power will accelerate energy demand at an exponential scale. With commodity trade increasingly encumbered by protectionism, one way to mitigate the inflationary consequence of such demand would be to introduce feasible substitutes such as nuclear power.
Fourth, technological innovation is breaking down old barriers. Small modular reactors (SMRs) represent a leap forward, offering lower startup costs and the option to be developed in locations previously deemed unsuitable for larger nuclear power plants.
For investors, the implications are clear. The nuclear theme is no longer niche – it is investable. Opportunities span the full value chain: physical uranium as a commodity play; miners who supply it; utilities with substantial nuclear in their energy mix; and manufacturers of next-generation reactor technologies such as SMRs.
Much like gold, nuclear represents a long-term hedge – not against inflation, but against energy insecurity, climate inaction, and geopolitical unpredictability. In a world beset by volatility, the atom may yet prove to be a surprisingly stable investment opportunity.
Trump’s economic strategy has made waves – some intentional, many collateral. While markets are beginning to price in a world of persistent policy risk, stretched fiscal metrics and shifting trade dynamics, this moment also invites a rethink of long-term portfolio construction and the discipline to heed the timeless adage: Time in the market beats timing the market.
The writer is chief investment officer, DBS Bank
TRENDING NOW
Singapore tech stocks plunge as Nasdaq bloodbath spills into region

S$3 billion money laundering case: Rare Pateks and Rolexes, diamond-covered Hermes and more head to auction

OCBC Q3 profit rises 3% to S$2.04 billion, slightly above expectations

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures

