

Look to sustainable investing to mitigate systemic risks
The focus is shifting away from ethical positioning and towards strengthening resilience
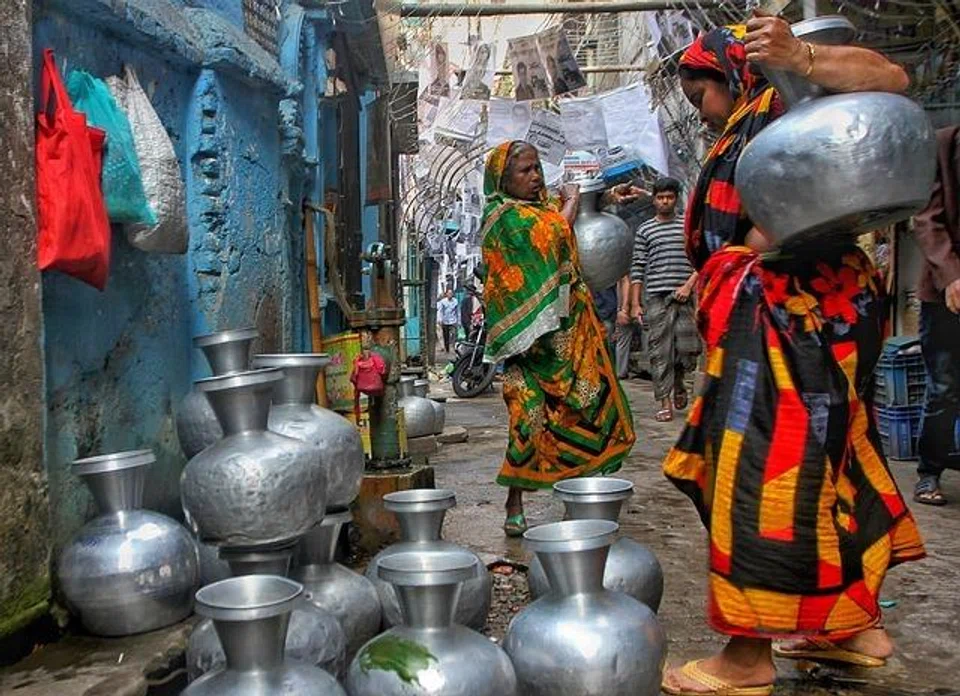
SUSTAINABILITY faces headwinds.
Global sustainable open-ended and exchange-traded funds recorded net outflows of about US$84 billion in 2025, as investors reassessed exposures amid geopolitical and regulatory uncertainty, shifting ESG focus and uneven short-term performance.
Yet, framing this as a retreat overlooks the broader reconfiguration of capital flows.
Capital allocation continues through bespoke sustainability mandates, private market opportunities and labelled sustainable bonds, where proceeds are increasingly funding the energy transition, infrastructure and resilience-related assets.
The global economy continues to face increasingly frequent and severe weather events such as floods, droughts and heat stress.
Geopolitical tensions, global trade fragmentation and rapid artificial intelligence-driven infrastructure expansion have further complicated the balance between climate ambition, energy and food security, and industrial competitiveness.
Policy responses have unsurprisingly tilted towards fossil fuels to secure supply, alongside subsidies and export restrictions aimed at stabilising food prices, which have distorted resource-efficient production in some cases.
These measures address immediate pressures, but the underlying volatility signals a broader shift: Sustainability is progressively less about ethical positioning and more about resilience across energy, transport, food, water, healthcare and supply chains.
Shockwaves beyond energy
Around one-fifth of global oil and gas supply passes through the Strait of Hormuz, with most flows directed towards Asia, particularly China, India, Japan and South Korea.
Recent disruption quickly lifted energy prices and shipping costs, which fed through interlinked essential systems. For example:
- Industrial value chain: Increased petrochemical feedstock costs have driven up virgin plastic resin prices, which may trigger regressive substitution towards more carbon-intensive or less recyclable materials that are used in many areas, from packaging to electronics. Disruption to sulphur exports have added costs to nickel and copper processing for battery materials and electrification infrastructure, fuelling green inflation.
- Food system: Constraints on ammonia and urea exports from the Gulf, which are critical to global nitrogen fertiliser supply, have raised food prices for consumers while increasing input costs and compressing margins for many smallholder farmers across import-dependent Asian economies.
- Healthcare system: Operating and distribution costs have increased in energy-intensive hospital services, cold-chain medicines such as oncology drugs, vaccines and insulin, and essential medicine supply chains. In addition, helium shortages can constrain advanced medical imaging capacity.
- Water system: Desalination capacity across parts of Asia and the Middle East is highly sensitive to fuel costs, effectively linking water security to energy volatility.
While conflicts have driven commodity shocks and inflation before, today’s complex and interconnected systems transmit these shocks faster and more broadly, with profound sustainability implications.
When challenges meet opportunities
Among investors surveyed in the 2025 Citi Research Sustainable Investment Survey, 91 per cent of those in the Asia-Pacific identified the energy transition as their top priority theme, followed by climate-resilient infrastructure, which came in at 59 per cent.
Recent events are likely to strengthen investment flows into these themes.
Global investment in the energy transition hit US$2.2 trillion in 2025, with Asia being the largest regional destination for capital deployment, led by China and supported by rapid growth in India.
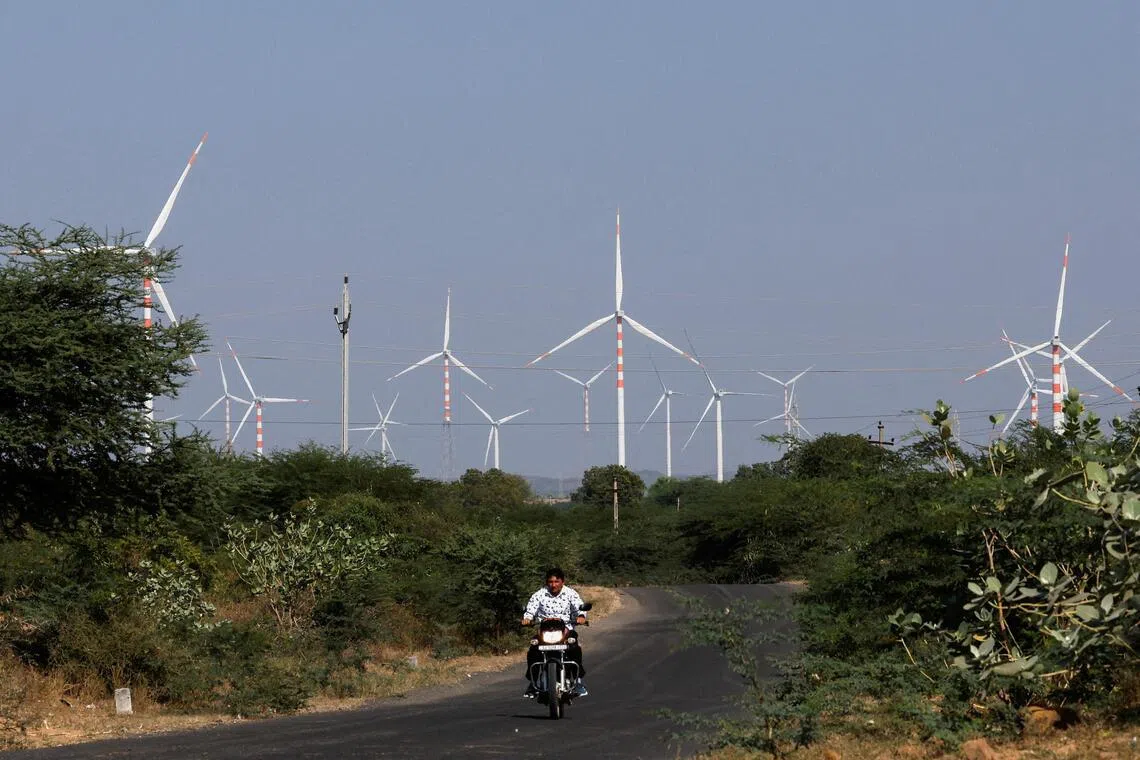
The energy transition is increasingly driven by economics and strategic resilience rather than climate policy alone. In many markets, solar and wind are already cheaper than imported fossil fuels over the long term.
Beyond clean energy generation, opportunities are emerging in grid management and energy efficiency.
These include battery energy storage systems, smart grids and transmission upgrades to handle intermittency, as well as electrification and efficiency innovations, particularly in hard-to-abate sectors such as transport, cement and steel.
AI has introduced a reinforcing loop in the system. While its expansion demands stable power, cooling and water infrastructure, the technology is also deployed to optimise grid balancing, forecast renewable output and reduce industrial wastage.
This dual role expands investment opportunities beyond software applications into core energy, underlying infrastructure and resource systems.
Investors are increasingly viewing climate adaptation not just as a defence against climate risks, but also as an emerging field for investment.
More than 250 priority solutions with various level of commercial viability and impact potential have been identified in the region across critical infrastructure and services, including water, health, natural ecosystems and biodiversity, agriculture and disaster preparedness systems.
Mounting food security risks in Asia, stemming from population growth, climate shocks and resource insecurity, are catalysing investment in technologies that enhance yields while reducing resource dependency.
These include precision agriculture, climate-resilient seeds, controlled-environment farming and water-smart irrigation. Domestic fertiliser and biofertiliser production is also gaining traction to reduce reliance on imports and carbon footprint.
Investing through a system lens
Sustainable investors are recognising that conventional investment approaches that target a single bottleneck often struggle to scale as sustainability risks manifest at the portfolio and system levels.
They are increasingly assessing how capital can change the system around the problem via system mapping, and identifying synergies and leveraging points for diversification.
For example, improving food security requires coordinated investments across reliable energy access, water management, climate adaptation, resilient supply chains and decent labour practices, in addition to enhancing agriculture outputs alone.
Capital structures are evolving in parallel. Sustainable investors are deploying capital across a continuum that spans philanthropy, sustainable investing, impact investing and blended finance.
Some of them use catalytic capital to absorb early-stage risks and build capacity in areas such as mini-grids, last-mile energy access and nature-based climate-resilient infrastructure, while deploying commercial capital to scale proven solutions.
Positioning for Asia’s accelerating risk complexity
Asia sits at the centre of the global transition. The region collectively faces rising energy demand, rapid urbanisation, acute climate exposure and vast infrastructure requirements, while remaining indispensable to global manufacturing and supply chains.
The transition challenge is structural. Sustaining affordability, accessibility and self-reliance is imperative while navigating a constrained decarbonisation pathway.
Recent crises emphasise the need to anticipate and better prepare for a broader set of emerging risks, from extreme weather, biodiversity loss and ecosystem collapse to cyberthreats and misinformation.
Investors have the potential to move beyond reactive capital allocation and focus on strengthening system-level resilience and fostering new innovations to adapt to compounding shocks.
This suggests multi-asset, cross-sector portfolio construction aligned with real-economy system linkages.
The writer is sustainable investing specialist for the Asia-Pacific, Citi Wealth






