Structured solutions provider Marex sees rising demand for notes with capital protection
The recent market upheaval has fanned demand for such products; that appetite looks likely to stay amid continued volatility
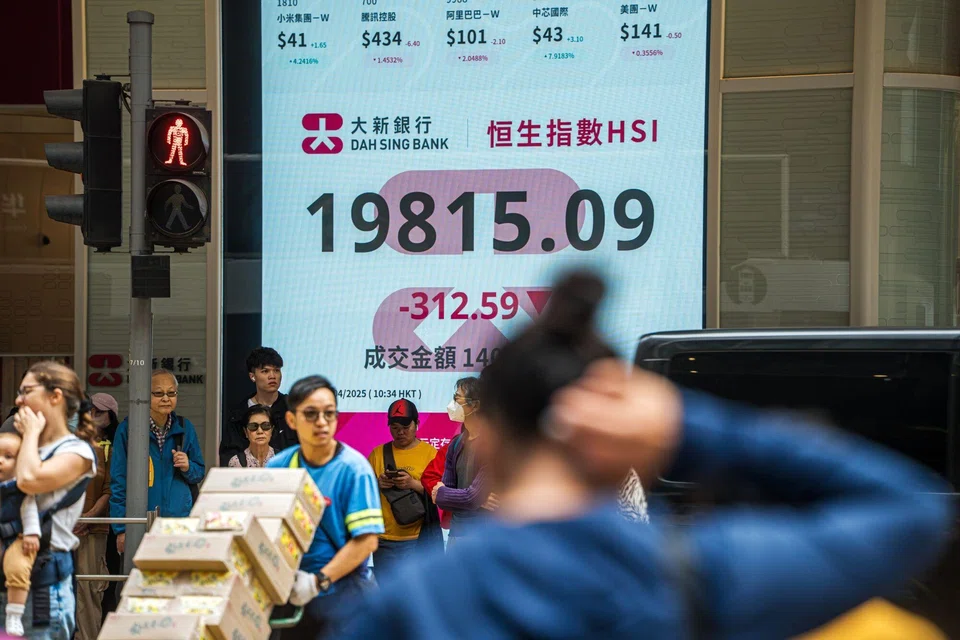
[SINGAPORE] Structured products provider Marex expects market uncertainty and elevated volatility to drive demand for structured notes with capital protection.
This is even as the firm takes steps to help clients, caught out by sharp market volatility, to restructure their existing notes, said Franck Fayard, head of Marex Financial Products for the Asia-Pacific.
Nasdaq-listed Marex is a global financial-services platform providing liquidity, market access and infrastructure services to clients in the energy, commodities and financial markets. Its financial products division has to date structured more than US$30 billion worth of investment notes, comprising over 15,000 products linked to all asset classes.
It was among the first to issue notes linked to iShares Bitcoin Trust Exchange-Traded Fund (ETF), BlackRock’s Bitcoin ETF, when it began trading in January 2024, for instance.
Fayard said the business in Asia is “growing very fast”, thanks to private clients’ familiarity with and penchant for structured products linked to foreign exchange (FX), stocks and equity indices, among others. “Investors in Hong Kong and Singapore are extremely sophisticated when it comes to structured products, especially in FX. Asian investors like to transact; they don’t like complex products. When they are comfortable with the product or strategy, they can take on leverage with full conviction. But they really have to understand the product.”
The recent market upheaval has raised the appetite for structured products with capital protection. Under Singapore regulations, these are called minimum redemption notes (MRNs), consisting of a zero coupon bond and an option.
Ideally, MRNs with upside participation should be created before the storm hits and volatility spikes, said Fayard. “This is because the cost of the option is linked to the implied volatility of the underlying assets, which tends to rise during market downturns. Investors pay significantly more for MRNs created in a market storm than if they had structured them beforehand.”
He said there has been a “notable pickup” in demand for MRNs linked to US equities, Hong Kong equities and precious metals. “Looking ahead, with volatility expected to remain elevated, we anticipate continued strong demand for MRNs. Timing will be key; investors would do well to strike such structures during periods when market volatility temporarily eases.” MRNs have typical tenors of two to three years, but demand is shifting towards those with durations of 12 to 18 months.
He said there is also greater interest in fixed-rate notes, which offer a guaranteed fixed coupon with no exposure to any particular asset.
Meanwhile, he said, the firm is helping clients to restructure their existing notes, particularly those with underlying stocks that were severely affected by the recent volatility. “Clients have responded positively to restructuring proposals which aim to recover losses more quickly by compromising on some other aspects of the investment,” he said.
Restructuring may take various forms, such as extending the note’s tenor, changing the underlying assets, adjusting coupon levels or modifying barriers. The client may also choose to sell the note back to Marex at the prevailing market price, and reinvest the proceeds in a new note with revised terms.
Interest in notes linked to Bitcoin ETFs has dropped, likely due to the drop in Bitcoin price this year. In the year to date, the iShares Bitcoin Trust ETF has generated a minus 9.5 per cent return. Demand for such notes spiked following Donald Trump’s election last year. Fayard said: “The crypto underlying market is liquid. Crypto markets never sleep, so there is no gap risk. Because it trades constantly, traders can constantly monitor the risk associated with the products.”
Still, client activity in crypto-linked notes has not completely stopped. Fayard reckons there may be a shift in investor behaviour, “from pure risk-on/risk-off strategies to a longer-term conviction and a desire for portfolio diversification”. Structured notes, he said, “are one of the few formats that allow precise calibration of risk and return in a single product”.
Marex can customise its structured products according to investors’ risk and return preferences, for a minimum amount of US$50,000.
It established a presence in Asia in 2010 with the opening of its Hong Kong office; it opened an office in Singapore the following year and now employs more than 200 staff in the Asia-Pacific. The structured solutions business under Marex Structured Products started in 2019.
Fayard said automation in the process of manufacturing and distributing structured products has been a “game changer” in Asia, facilitating price transparency, standardisation and access. “Standardisation of the payoffs, visibility and trading through platforms have brought a lot of efficiency and transparency, so there’s no surprise. It then comes down to investors understanding the risk and choosing the right underlying asset.”
He notes that the wealth management structured products markets in Hong Kong and Singapore are among the most automated in the world. Some larger markets like South Korea are yet to “fully embrace automation”. “There is still significant room for growth and innovation in the region,” he said.