

Sheng Siong shares fall 2.1% after Maybank downgrade, target price cut
The counter has pared some losses from a low of S$2.83 in early trade
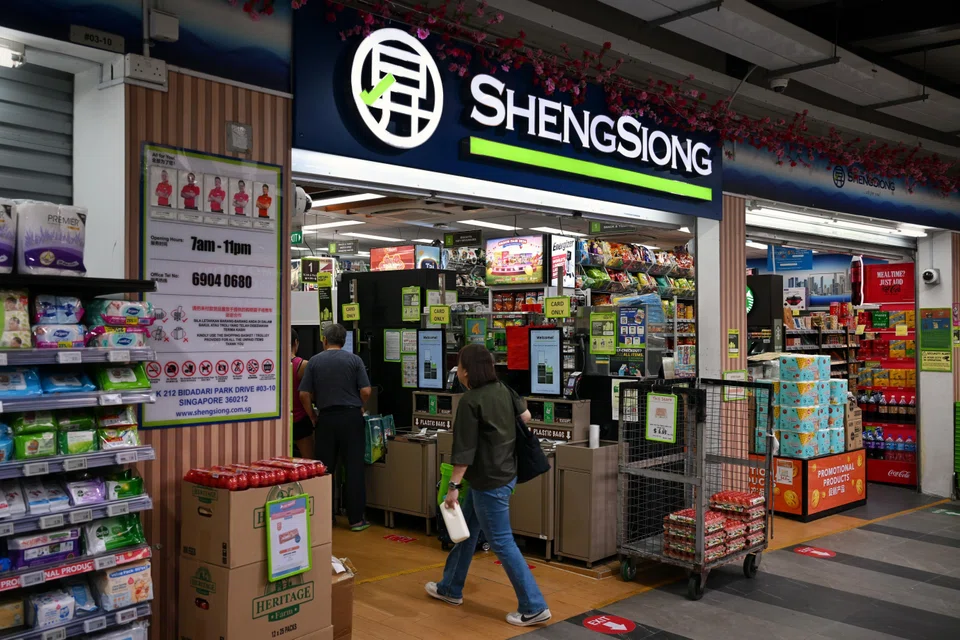
[SINGAPORE] Shares of Sheng Siong fell as much as 3 per cent on Monday (Oct 12) after Maybank downgraded the supermarket chain to “hold” from “buy” and cut its target price.
The counter fell as low as S$2.83 in early trade on Monday, before paring some losses to close 2.1 per cent lower at S$2.86.
The decline followed Maybank cutting Sheng Siong’s target price from S$3.22 to S$3.12 on Friday. This was due to a narrower upside that makes the supermarket chain one of the region’s “most expensive food retailers” at a forward price-to-earnings ratio of 28.4 times.
This is despite a net profit after tax (NPAT) compound annual growth rate (CAGR) of 8 per cent through 2028 and a 2.5 per cent dividend yield.
Maybank analyst Hussaini Saifee said: “Within the consumer space, we prefer Food Empire , supported by its strong NPAT growth (31 per cent CAGR), moderate valuations and 5 per cent dividend yield.”
The research house also lowered its forecast for new Sheng Siong stores in 2028 from five to four and reduced FY2026-to-FY2028 net profit after tax by a range of 1 to 3 per cent.
“Sheng Siong remains a high-quality operator, but its strong share-price rerating now prices in much of it,” said Saifee. “With growth normalising and slight headwinds emerging, we see limited scope for further re-rating.”
Tailwinds turn into headwinds
While Sheng Siong has benefited from “resilient consumption”, market-share gains and targeted vouchers that channelled spending directly to supermarkets, such tailwinds are weakening.
Maybank said that more assistance is being provided through unrestricted GST Vouchers and cash payments.

The S$500 tranche of CDC Vouchers, originally scheduled for January 2027, was brought forward to June 2026, boosting FY2026 demand but raising the comparison base for FY2027.
With supermarket growth already easing to low single digits, the research house expects Sheng Siong’s growth to track underlying income and population trends, rather than benefit from a repeat of the unusually favourable conditions of recent years.
Sheng Siong’s capture of displaced demand from store closures at Giant and Cold Storage has also petered out, as the two competing chains have closed only one store between them.
Cold Storage’s new owner, Macrovalue, which bought both chains from DFI Retail Group in 2025, has “resumed expansion” through its On The Go convenience stores.
It will be rolled out progressively to all 58 Esso petrol stations across Singapore through 2026 and targets more than 100 outlets over time.
Saifee said: “Although the convenience-led format does not directly replicate Sheng Siong’s full-basket proposition, it adds competition for top-up grocery purchases, convenience items and ready-to-eat meals.”
Separately, Johor Bahru-Singapore Rapid Transit System (RTS)-linked cross-border shopping and the gradual evolution of online grocery fulfilment could also pose headwinds for Sheng Siong.
The supermarket chain appears more exposed to northern Singapore catchments than its larger competitors. About 10 per cent of its network – nine stores – is within 5 km of the RTS station, while about 27.5 per cent – 25 stores – is within 15 km.
“While neither appears disruptive enough to reshape the industry in the near term, both point to a less favourable backdrop than in recent years,” said the analyst.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
AI can become superior to humans in certain aspects: TikTok’s Chew Shou Zi
DBS, OCBC, UOB face rate hike reality check
‘The market has spoken’: DBS CEO Tan Su Shan says market is repricing AI financing risks

