The economic shock that’s almost too hot to handle
El Nino deals a new blow to supply chains and prices that central bankers must now reckon with
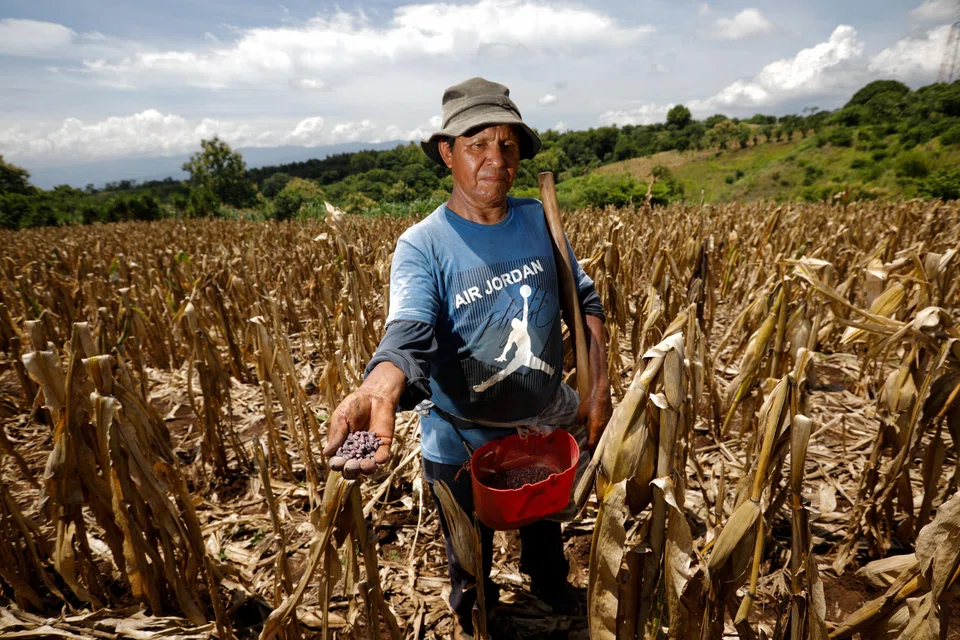
TO SAY that central banks dislike making policy based on extreme weather is an understatement. But they cannot duck the economic reverberations of the powerful El Nino that is roiling Asia.
The dry spell is another shock that the monetary authorities could do without. They spent years getting on top of the inflation surge that followed the post-pandemic economic reopening and Russia’s invasion of Ukraine.
Officials watched with trepidation as the US imposed extensive tariffs, and then had to deal with the spike in energy prices from the Iran war.
Now comes a new blow from climate, and the challenge of responding to the phenomenon one policymaker called a “Godzilla”.
The weather pattern, which has brought drought to South and South-east Asia, is likely to get stronger. Odds are it will surpass all records going back to 1950, US experts have said.
It is disrupting markets for commodities such as rice, contributing to shortages of water and, further afield, slowing traffic in the Panama Canal, forcing up costs for shippers.
The weak monsoon was one factor driving the Reserve Bank of India’s (RBI) rate increase on Oct 7.
Central bankers will endeavour to figure out how much of the impact will be short-lived and what risks becoming entrenched in the decisions of companies and consumers. The problem today is that officials are running out of scope to wait and see.
Bond yields are climbing in Thailand and the Philippines, reflecting renewed inflationary forces. Long-term market rates in India jumped to the highest level in almost three years after the RBI pivoted to a more hawkish stance.
And Manila recently got some bad news: After decelerating for four months, inflation punched through 7 per cent in August, which means additional tightening is on the cards this October.
Credibility is on the line. Policymakers can afford to look through an isolated shock or two. But if they start to stack up and exacerbate each other, the luxury of waiting disappears. Some central banks avoided hiking when the Middle East conflict erupted and are now playing catch up.
The environment and policy
But there is an important distinction between responding to higher inflation which can be caused by bad weather, and developing policy according to climate projections.
Financial institutions, often regulated by central banks, must be sturdy enough to withstand the impact of severe weather. Fires, flooding, the outlook for agriculture and transportation are all important factors in the economic health of nations, too. But the environment is one area where central banks have been accused of overreach.
It is tempting to take on extra responsibilities, especially when legislatures seem unable to deal with weather events effectively or in a timely manner.
But fall down on traditional missions such as price stability or a solid labour market, and other initiatives – however worthy – can lead to backlash.
The subject is particularly sensitive in the US, where the Federal Reserve has backtracked on some of its engagement on climate issues.
Across the Atlantic, however, the work continues. A top official from the European Central Bank said earlier in October that trying to deny the impact of environmental change on the economy is reckless. It is not so much mission creep as recognising reality.
The Fed, despite its independence in setting rates, endeavours to sniff the political wind. Within days of Republicans taking control of the House of Representatives in 2023, then chair Jerome Powell declared that the Fed is not, and does not seek to be, a climate policy shop.
Days before Donald Trump was sworn in for a second term as president, the bank quit a network of central banks and regulators engaged in the study of climate risk.
The Fed would stick to its knitting, Powell insisted, and thus defend its autonomy.
This pushback is not a uniquely American phenomenon. An independent review into the Reserve Bank of Australia found that climate change should be a factor in modelling and forecasting, but that policy should remain the domain of parliament.
The most scathing critique came from a former executive at the Bank for International Settlements, a kind of club for central banks.
Claudio Borio, who led the monetary and economic division, said on Oct 6 that hubris had infected policymaking, and that a dangerous gap had opened between what central banks can deliver and what they are expected to achieve.
Among the major errors is “flirting with objectives which are really far away from the mandate”, such as “the green transition or the idea of inclusive growth”.
Central bankers, on ascending to the top job, often receive mementos from esteemed predecessors such as a coffee mug with encouraging words or a relic of the institution’s history. This generation must wish they had been given a hazmat suit. BLOOMBERG