

Why global equities can continue to rally as bond yields rise
The expected earnings growth following capital deployments in key markets is seen as a driver
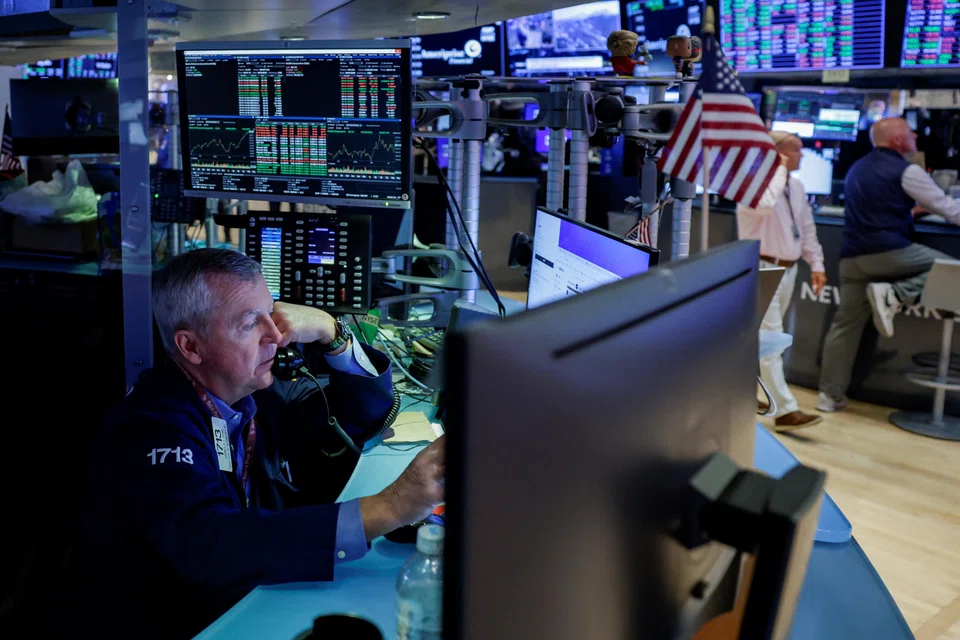
THE year 2026 has seen US and global equities hold strong even as expectations of central bank rate cuts gave way to rate-hike worries and actual rate hikes in Europe and Japan, a war broke out between the US and Iran, the price of a barrel of oil rose to US$100 and above and, more recently, 10-year government bond yields in the US, euro area, the UK and Japan rose to levels last seen prior to the 2008 to 2009 global financial crisis.
The key driver to overcoming these obstacles has been rising earnings growth expectations across Western economies.
The US has seen a doubling in earnings growth expectations since the start of the year, from 12 per cent to 24 per cent. This means investors are paying less – 19.9 times earnings today – versus at the start of the year (22.1 times), despite the 14 per cent gain in the S&P 500 through to mid-August.
In Europe, low-single-digit earnings growth expectations at the start of the year have risen to 15 per cent year-on-year growth through July, despite the economies in the net-energy-importing bloc struggling with higher oil prices.
The improvement in earnings expectations means that despite the 13 per cent rise in MSCI euro area equities through to mid-August, valuations in the single-currency area have remained stable at an admittedly elevated 15 to 16 times earnings throughout 2026.
Asian equities
World-beating Japanese equities – MSCI Japan delivered nearly 50 per cent total US dollar returns since end-2024 – have seen valuations fall in 2026 despite equities rising 24 per cent year to date until mid-August.
Earnings growth expectations accelerated to nearly 32 per cent year on year, benefiting from Japan’s position in the global semiconductor value chain and steepening yield curves in the global economy.
In contrast, Chinese equities have lagged their Western and emerging-market counterparts, with MSCI China forecast to see modest, single-digit earnings expectations for 2026. Unlike the upgrades seen in Europe, Japan and the US throughout the year, earnings expectations have remained relatively stable over the first eight months of the year.
Fortunately, at 10 to 11 times earnings in mid-August, MSCI China valuations sit near post-pandemic lows.
Thus, investors’ concerns in the US, Europe and Japan over high valuations at the start of the year have eased as companies have grown into these valuations, bringing relief to extended fundamentals and strong returns through the first eight months.
Changes in the global economy
A key to the earnings upgrades has been the changes to the global economy brought about by US President Donald Trump’s second-term agenda.
Trump’s “Big Beautiful Bill” passed in 2025 incentivised the capital-spending boom in power and data centre construction following the legislation’s full implementation in early 2026.
That fiscal support has driven 10 per cent year-on-year growth in US power sector construction and more than 45 per cent growth in data centre construction, driving earnings for corporates across those sectors.
That spending has rippled through the global semiconductor value chain, benefiting South Korean, Japanese, Chinese as well as European corporates.
The Trump administration’s hawkish stance on European defence has kicked off, albeit belatedly, a long-awaited European defence-spending cycle led by Germany’s 2025 liberalising of its “debt brake”, allowing it to borrow to fund defence and public infrastructure spending.
Moreover, just as Russia’s 2022 invasion of Ukraine spurred widespread spending on renewable energy on the continent, the US-Iran war has accelerated green energy solutions in Europe adding another capital-spending cycle as a continental tailwind.
While Japan is already positioned within the semiconductor value chain and benefiting from the global uplift in demand, Japanese Prime Minister Sanae Takaichi has outlined a US$2.3 trillion programme over the coming decade to target investment across other strategic industries as well.
This is in addition to the significant spending that previous Japanese governments have committed to national defence as the nation continues to pivot away from its post-World War II pacifist stance.
With these secular drivers in place and momentum looking set to continue through to the end of the year, even if upgrades to earnings expectations begin to wane, investors can take comfort that US equity valuations in absolute terms have moderated.
Also, valuations relative to rising 10-year Treasury yields sit well short of levels which have signalled temporary peaks in the post-pandemic era.
Most investors drawing on their experiences since the turn of the century are used to rising interest rates presenting a headwind for equity markets and falling rates a tailwind. This was true in the era of low and, since 2008, negative real interest rates in the US and much of the Western world.
However, in the late 20th century, when real interest rates were, like today, last positive on a sustained basis on both sides of the Atlantic, the S&P 500 earnings yield (the inverse of its price-to-earnings ratio) and US 10-year yields were often near similar levels.
During that period, only when the S&P 500 earnings yield fell below the 10-year US Treasury yield by more than 100 basis points did the risk-reward of US equities relative to local bonds tilt away from equities.
Currently, the S&P 500 earnings yield and the 10-year US Treasury yield are at 5 per cent and 4.7 per cent, respectively.
Thus, with the current differential sitting at near 30 basis points, we estimate that the S&P 500 can absorb a rise in yields to 50 to 100 basis points above 5 per cent before bond yields might become a meaningful headwind for equity returns.
Alternatively, a 10 to 15 per cent rise in the S&P 500 against current 10-year yields without additional earnings growth would be needed for the benchmark US index to reach overvaluation levels seen in the late 1980s and 1990s peaks.
Elsewhere, Japan has pivoted to positive, inflation-adjusted 10-year yields for the first time since the early days of Abenomics in 2012, while the euro area’s risk-free reference yield, Germany’s 10-year yield, has likewise shifted to a positive real-yield profile for the first time since the onset of the eurozone crisis in 2011.
This suggests that both geographies may be set to replicate the US experience and narrow the gap between earnings yields and nominal bond yields.
Currently, Japanese equities deliver investors an earnings yield of more than 5.8 per cent, compared with Japan’s 10-year bond yields of 2.9 per cent. Eurozone equities offer investors earnings yield of 6.3 per cent against German 10-year bond yields of 3.2 per cent.
Thus, the much larger basis point premium compared with that in the US provides investors an even more meaningful cushion against the prospect of higher global bond yields ahead.
In contrast, Hong Kong-listed Chinese equities require a more encouraging corporate earnings outlook ahead to reverse the moribund performance in the year to date.
Investor angst persists over the path ahead for the Federal Reserve and other global central banks, whether a durable ceasefire can be achieved in the Middle East, or where rising bond yields may find a new equilibrium.
Still, with the long-term capital-spending cycles now under way in the US, Europe, Japan and continuing in China, the key focus for investors looking for the driver of equity returns by the year-end should be the earnings growth benefiting from these capital deployments and the prospect of upside earnings surprises.
Market data is updated as at market close on Aug 14
The writer is group chief strategist at Union Bancaire Privee
TRENDING NOW

LTA proposes combining car COE categories, adding rebate-surcharge system
StarHub to acquire MyRepublic’s mobile business amid ongoing telco consolidation

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

