A Step-by-Step Guide to Financial Planning in Singapore
Updated: 19 Oct 2026
Written bySingSaver team
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
Where should your financial plan start?
What is financial planning?
Financial planning is a comprehensive process of evaluating your current financial health, defining your goals, and crafting a tailored strategy to achieve those goals, considering your unique financial landscape alongside that of Singapore. It’s about making informed decisions about your money to build a secure future.
A financial plan should:
- Give you a clear picture of your overall financial health.
- Help you define and prioritise your financial goals.
- Outline the steps you need to take to reach your goals.
Key 2026 numbers for your financial plan
| Item | 2026 figure | Why it matters |
| CPF monthly salary ceiling | S$8,000 | CPF contributions apply on wages up to this amount |
| Basic Retirement Sum (turning 55 in 2026) | S$110,200 | Est. CPF LIFE payout of about S$950/month from 65 |
| Full Retirement Sum (turning 55 in 2026) | S$220,400 | Est. CPF LIFE payout of about S$1,780/month from 65 |
| Enhanced Retirement Sum | S$440,800 | Est. CPF LIFE payout of about S$3,440/month from 65 |
| SRS contribution cap | S$15,300 (citizens/PRs), S$35,700 (foreigners) | Every dollar contributed reduces your chargeable income |
| CPF cash top-up relief | Up to S$8,000 (self) + S$8,000 (family) | Tax relief for topping up retirement and MediSave accounts |
| Personal income tax relief cap | S$80,000 per Year of Assessment | Applies to all personal reliefs combined, including SRS |
Note: Figures as of 19 Oct 2026. Check CPF and IRAS for the latest.
9 steps in financial planning
1. Set financial goals
Setting clear and achievable financial goals is the foundation of any successful financial plan. It’s easy to get caught up in ambitious targets, but setting realistic goals is key to staying motivated and on track. Instead of aiming for a lofty goal like saving 50% of your salary a year, start with a more manageable target, like 10% to 20%. If you find yourself exceeding your goal, that’s a bonus! The key is to set yourself up for success and build confidence in your ability to manage your finances.
Don’t try to tackle too many goals at once. Focus on one to three primary goals to increase your chances of success. It’s also helpful to categorise your goals into short-term, mid-term, and long-term aspirations. This provides a clearer roadmap for your financial journey and helps you prioritise your efforts. For example, a short-term goal might be paying off a credit card, while a long-term goal could be saving for retirement or your children’s education. Setting deadlines for each goal adds a layer of accountability and helps you stay on track.
2. Monitor your cash flow
To truly understand your financial situation and make informed decisions, you need to have a firm grasp of your cash flow. This means tracking both your income and expenses meticulously. By monitoring where your money is coming from and where it's going, you can identify unnecessary spending habits and find opportunities to trim costs. This might involve cutting back on discretionary expenses like dining out or entertainment, or finding ways to reduce essential costs like your utilities or groceries.
Consider using budgeting tools to simplify the tracking process. Budgeting apps can automatically categorise your expenses and provide insights into your spending patterns. Alternatively, a simple spreadsheet can be an effective tool for manually tracking your income and expenses. Regularly reviewing your bank statements and credit card statements can also help you identify recurring expenses, lifestyle creep, and potential areas for savings.
>> Need further help? Check out the best budgeting apps on the market.
3. Build an emergency fund
Life is full of surprises, and not all of them are pleasant. An emergency fund acts as a financial safety net, providing a financial cushion for unexpected events like recession, medical emergencies, car repairs, or sudden job loss. Aim to have three to six months' worth of living expenses saved in a liquid and easily accessible account. This ensures you can access your funds quickly when needed, without having to resort to high-interest debt or dipping into your long-term savings.
When deciding where to keep your emergency fund, consider factors like liquidity, accessibility, and potential returns. High-yield savings accounts offer higher interest rates than regular savings accounts, helping your money grow faster while still providing easy access to your funds. Fixed deposit accounts offer a fixed interest rate for a set period, providing a guaranteed return, but may have limited accessibility until the maturity date.
>> Need further help? Check out the best low-risk investments to store emergency funds.
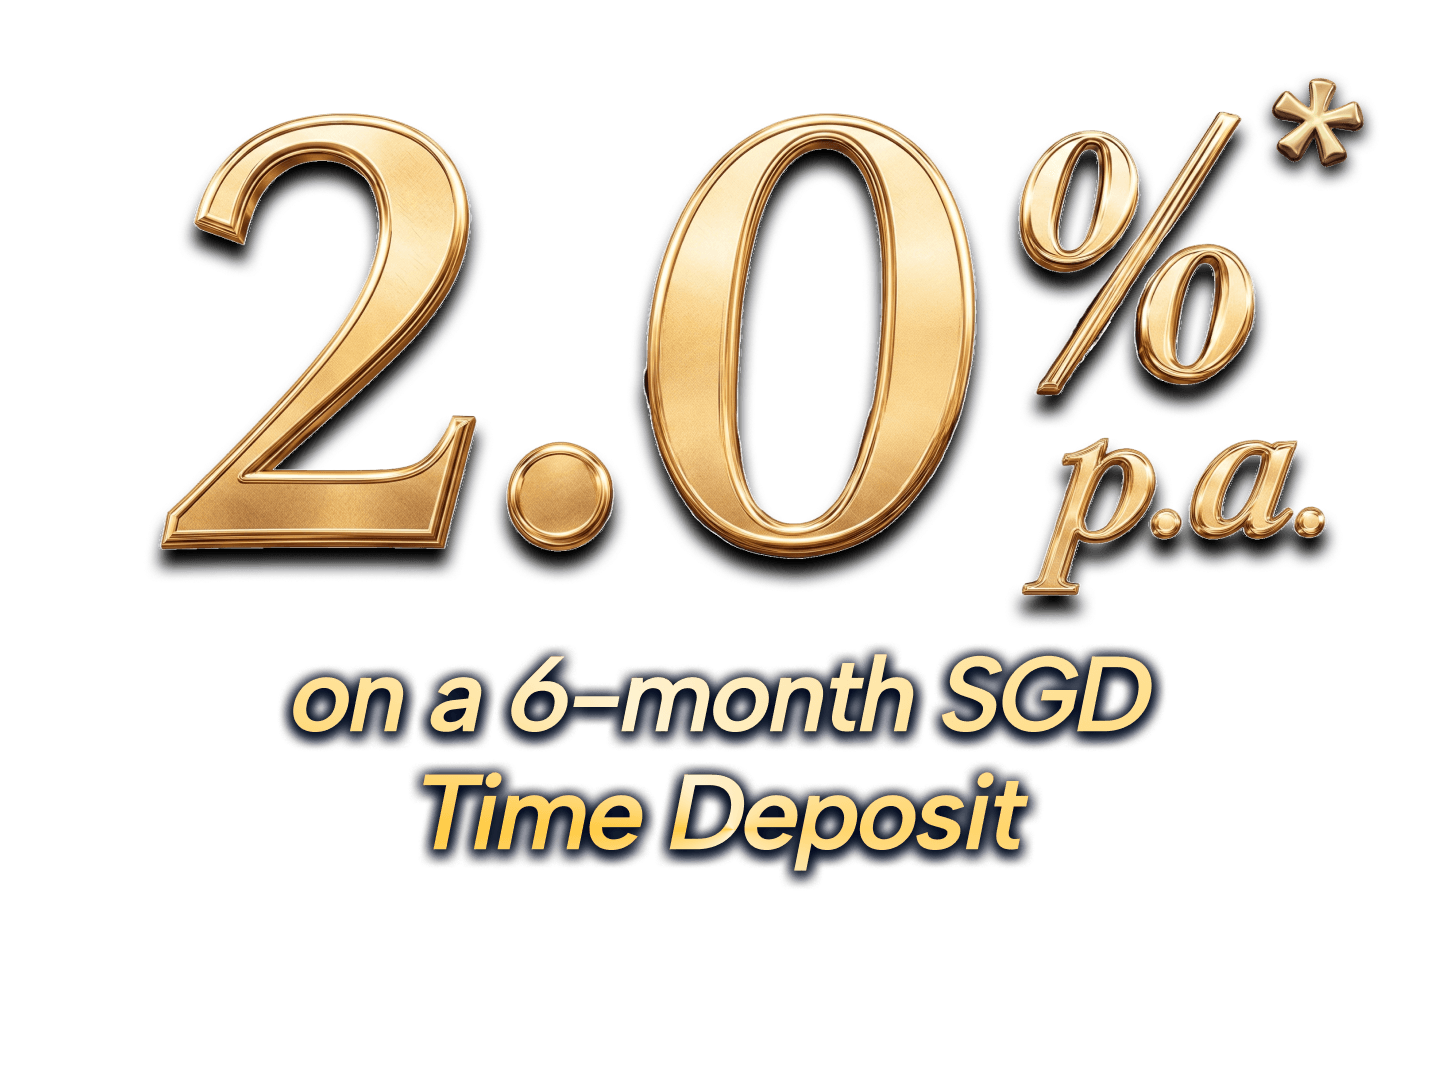
SingSaver x Citigold Exclusive Offer
Enjoy a 2.0% p.a.* preferential rate on a 6-month SGD Time Deposit when you join Citigold. Plus, SingSaver welcome rewards of up to S$1,800 Cash, 75k Miles by Heymax or the latest Apple smartphone. Valid till 30 November 2026. T&Cs apply.
4. Reduce high-interest debt
High-interest debt, such as credit card debt, can be a major obstacle to your financial goals. The interest charges can quickly accumulate, making it difficult to pay down the principal and trapping you in a cycle of debt. Prioritise paying down these debts as quickly as possible to minimise interest costs and free up cash flow for other goals, such as saving for a home or investing for retirement.
Explore strategies like debt consolidation or balance transfers to lower your interest costs and simplify repayment. Debt consolidation combines multiple debts into a single loan with a lower interest rate. A balance transfer moves your credit card balance to a low- or 0%-interest plan for a set period, usually for a one-time processing fee, giving you time to pay down the debt. Make sure you can clear the balance before the promotional period ends.
>> Need further help? Check out the best debt consolidation plans in Singapore.
5. Secure your retirement
Retirement planning is essential, no matter how far off it may seem. In Singapore, the Central Provident Fund (CPF) forms the foundation of your retirement savings. From 1 January 2026, CPF contributions apply on monthly wages up to S$8,000, and contribution rates for workers aged above 55 to 65 have increased, with the extra amount going to their Retirement Account.
At 55, your CPF savings are set aside in your Retirement Account. For members turning 55 in 2026, the Full Retirement Sum (FRS) is S$220,400, which gives an estimated CPF LIFE payout of about S$1,780 a month from age 65. Your retirement sum is fixed by the year you turn 55, so younger members will have higher targets. CPF alone may not support the lifestyle you want in retirement, so it’s worth planning beyond it.
The Supplementary Retirement Scheme (SRS) is a voluntary scheme that lets you contribute up to S$15,300 a year (citizens and PRs) or S$35,700 a year (foreigners). Contributions reduce your taxable income and can be invested in a range of instruments. You can also consider private retirement plans offered by insurers and banks, which come with different risk profiles and payout options.
6. Optimise your tax strategy
Tax planning is an integral part of financial planning in Singapore. Using the tax reliefs available to you can reduce your tax bill and free up more money for savings and investments.
Singapore offers various reliefs, such as reliefs for parents, working mothers and individuals with disabilities, as well as for course fees. Two of the most useful for financial planning are SRS contributions and CPF cash top-ups. Top-ups to your own retirement and MediSave accounts qualify for up to S$8,000 in relief, with another S$8,000 for top-ups to loved ones’ accounts. All personal reliefs combined are capped at S$80,000 per Year of Assessment, so check your total before contributing for tax reasons alone.
>> Need further help? Check out all you need to know about personal income tax in Singapore.
7. Invest to grow your wealth
Investing is essential for beating inflation, growing your wealth, and achieving your long-term financial goals. Singapore offers a diverse range of investment vehicles to cater to different needs and risk appetites. The CPF Investment Scheme (CPFIS) allows you to invest your CPF savings in a variety of instruments, such as unit trusts, bonds, and stocks. Exchange Traded Funds (ETFs) provide a convenient way to gain diversified exposure to the market by tracking a specific index, like the Straits Times Index (STI). Real Estate Investment Trusts (REITs) offer a way to invest in a portfolio of income-generating properties. For those seeking a more hands-off approach, robo-advisors provide automated investment management based on your risk profile and financial goals.
Before you embark on your investment journey, it’s crucial to assess your risk tolerance and develop a long-term investment strategy. Consider your investment timeframe, financial goals, and comfort level with risk when choosing your investment portfolio.
>> Need further help? Check out investment strategies for new investors.
Before You Compare
Set your emergency fund aside first
Keep 3 to 6 months of expenses in cash so you’re never forced to sell investments.
Match the product to your timeframe
Money needed within 3 years suits savings or T-bills, not stocks or CFDs.
Know your risk tolerance
Decide how big a drop you could ride out before choosing stocks, ETFs or robo-advisors.
Compare all-in fees, not just commissions
Check platform, custody, FX and fund fees. Small fees compound over decades.
Check if you’re investing SRS or CPF funds
Only some platforms accept SRS or CPFIS funds, so confirm before opening an account.
8. Manage risk with insurance
Insurance plays a vital role in protecting your financial well-being from unexpected events. Life is unpredictable, and unforeseen circumstances like illness, accidents, or disability can have a significant financial impact. Having adequate insurance coverage can provide a safety net and ensure that you and your loved ones are financially protected in times of need.
Essential insurance policies in Singapore include health insurance, life insurance, disability insurance, and critical illness insurance. Health insurance helps cover medical expenses in case of illness or injury. Life insurance provides a financial payout to your beneficiaries in the event of your death, ensuring their financial security. Disability insurance replaces a portion of your income if you become unable to work due to illness or injury, while critical illness insurance provides a lump sum payment if you are diagnosed with a critical illness. Homeowners should also check out home insurance policies.
>> Need further help? Check out the best insurance plans in Singapore.
9. Plan your legacy
Estate planning is an important but often overlooked part of financial planning. It involves arranging how your assets are distributed and making sure your wishes are carried out after your death. This includes writing a will, setting up trusts, and making a CPF nomination.
A will sets out how your assets should be distributed after your death. However, your CPF savings aren’t covered by your will, so make a separate CPF nomination to decide who receives them. Trusts can be used to manage assets for your beneficiaries with more control and flexibility. A legal professional can help make sure your plans are sound and carried out as you intend.
When to make a financial plan
While it’s always beneficial to have a financial plan, certain life events and milestones often necessitate a closer look at your finances and a reassessment of your financial goals. These key moments include:
- Starting a new job: When you start a new job, it’s crucial to evaluate your employee benefits, including your retirement plan options and any employer contributions. This is also a good time to set up an emergency fund and start planning for future financial goals, such as saving for a home or investing for retirement.
- Parenthood: Becoming a parent brings significant financial responsibilities. You’ll need to plan for childcare costs and education expenses, and ensure you have adequate insurance coverage for your growing family. This is also a good time to review your will and estate plan to ensure your assets are protected and distributed according to your wishes.
- Buying property: Purchasing a property is a major financial decision. You’ll need to develop a budget, secure financing, and consider purchasing homeowner’s insurance to protect your investment. This is also a good opportunity to review your overall financial plan and ensure you’re on track to achieve your long-term goals.
- Increase in wealth: If you experience a sudden increase in wealth, such as an inheritance or a windfall, it’s important to seek professional financial advice to manage your newfound assets effectively. This might involve developing an investment strategy, exploring tax-efficient investment options, and updating your estate plan.
- Serious illness: A serious illness can have a significant financial impact. It’s crucial to review your insurance coverage and ensure you have adequate protection for medical expenses and potential loss of income. This is also a good time to review your estate plan and ensure your affairs are in order.
- Retirement: The official retirement age rose to 64 on 1 July 2026, and the re-employment age to 69. As you approach retirement, plan how you’ll draw down your savings, taking into account your CPF LIFE payouts, investment income and expenses. You might also consider downsizing your home to stretch your retirement funds further.
- Singapore-specific financial milestones: Certain financial milestones in Singapore, such as contributing to your CPF, taking advantage of tax reliefs, and planning for your children’s education, require careful consideration and planning to ensure you’re making the most of available opportunities and benefits.
Comprehensive financial planning and investment advice
- Online financial planning platforms in Singapore: These platforms offer a structured approach to creating a financial plan, with interactive tools and resources to guide you through the process, often incorporating Singapore-specific considerations like CPF and tax planning. Some platforms may also offer access to financial advisors for additional support.
- Financial advisors in Singapore: Working with a financial advisor in Singapore provides a more personalised approach. They can help you create a tailored financial plan that considers your individual circumstances, risk tolerance, and financial goals, including retirement planning with CPF and investing in local markets.
Specialised financial guidance in Singapore
- Financial advisors with specific expertise: If you have complex financial needs in areas like estate planning, tax optimisation, or retirement planning, consider consulting with a financial advisor who specialises in those areas. They can provide in-depth guidance tailored to your specific situation and help you navigate Singapore’s regulatory landscape.
>> Want to connect with financial experts? Check out the best wealth management services available.
Investment management in Singapore
- Robo-advisors: If you’re mainly looking for help with your investments, robo-advisors such as StashAway offer a convenient and cost-effective option. These platforms use algorithms to build and manage a diversified portfolio based on your risk tolerance and goals, and some also accept SRS funds.
>> Need help choosing a robo-advisor? See SingSaver’s list of the best robo-advisors in Singapore.
Why is financial planning important?
Let’s face it, navigating Singapore’s financial landscape can feel like a juggling act. Between rising costs, evolving CPF policies, and a myriad of investment options, it’s easy to feel overwhelmed. That’s where financial planning comes in.
Think of it as your personal roadmap to financial well-being. A well-crafted plan helps you make sense of it all, from maximising your CPF and navigating tax complexities to building a diversified investment portfolio that aligns with your goals. Whether you’re dreaming of homeownership, planning for your children’s future, or securing a comfortable retirement, a solid financial plan empowers you to take control and build a more secure future.
>> Ready to get started? Learn the 5 steps to reaching your financial goals.
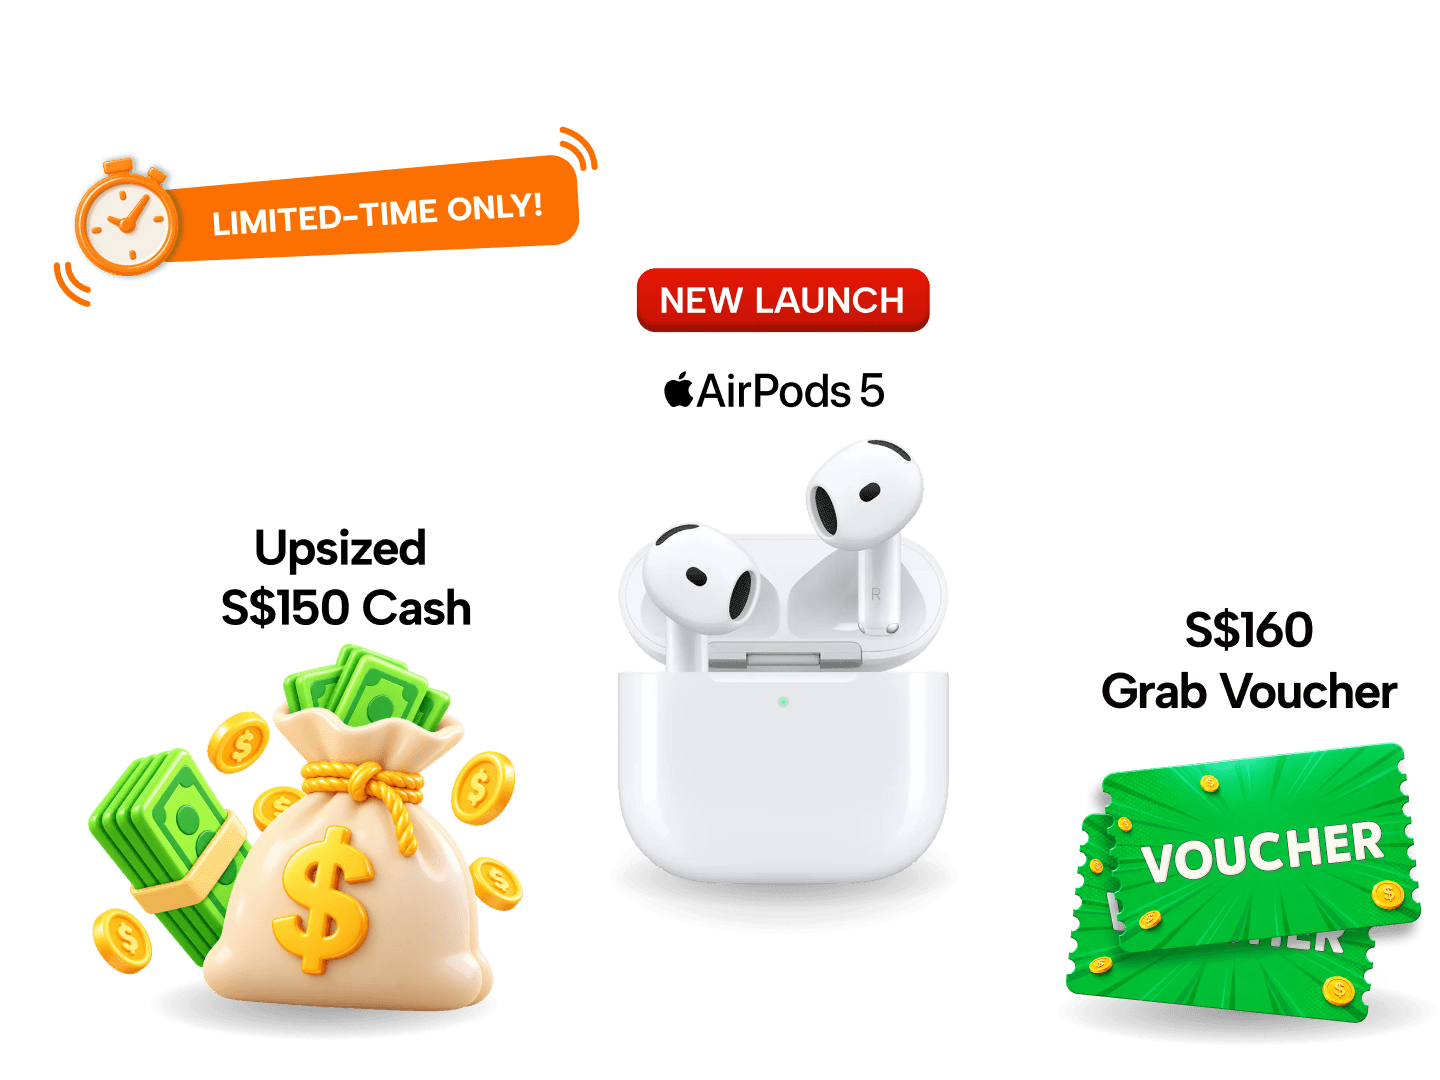
SingSaver x moomoo Exclusive Offer
Open a Moomoo account and fund a minimum of S$2,000 to get S$130 Cash via PayNow, S$140 Grab Vouchers, Apple AirPods Gen 5 or 8,000 Max Miles by HeyMax. Valid till 30 November 2026. T&Cs apply.
About the author
SingSaver team
At SingSaver, we make personal finance accessible with easy to understand personal finance reads, tools and money hacks that simplify all of life’s financial decisions for you.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.