SREITs struggle amid weak sales and declining tourist arrivals in 2H14
But office rents are expected to spike.
Retailers are scratching their heads over weak sales, even as tourist spending growth continues to moderate. The future remains challenging for domestic retail and hospitality REITs, a report by Moody’s Investors Service revealed today.
Moody’s revealed that while a healthy operating environment and manageable refinancing risk continue to support the stable outlook for the Singapore Real Estate Investment Trust sector, certain segments will continue to face headwinds this year.
In the retail segment, for instance, weaker tenant sales and a lack of demand will slow the take-up rate for new retail space, creating a challenging environment for upcoming supply.
Meanwhile, the increasing supply pipeline in the hotel segment in 2014 and 2015, coupled with moderating growth in Singapore's tourist arrivals and tourism spending, will cap growth in average room rates.
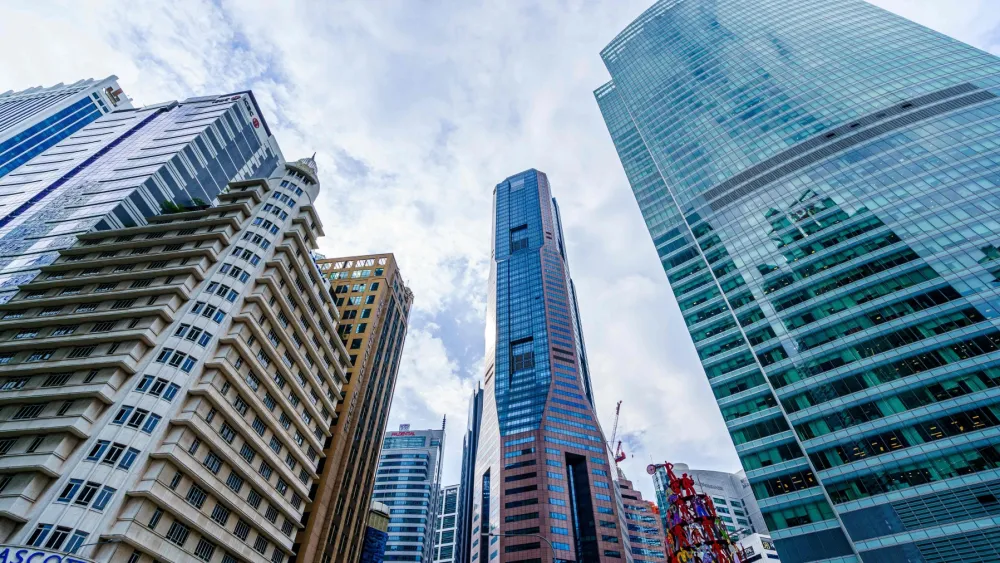
But a rosy outlook awaits developers of office space, as Moody's expects the tight supply of new office
space in the core central business district will improve occupancy rates. The limited supply also provides landlords with greater pricing power, which will likely increase monthly rental rates.
"The outlook reflects our view that the sector's EBITDA will grow by 4% in 2014, supported by a larger asset base and some positive rental revisions," says Jacintha Poh, a Moody's Assistant Vice President and Analyst, speaking at the Property Market Update Seminar 2014.
Here’s more from Moody’s:
Business and science parks will also see sizeable space additions in 2014 and 2015, but Moody's expects rental rates will remain broadly stable, owing to the strong take-up.
Moody's sees potential weakness in the warehousing segment, where a spike in the supply of new warehouse space will pressure occupancy and rental rates. Nevertheless, Moody's estimates at least 60% of upcoming space has been pre-committed by end-users.
Funding costs will increase with the rising interest rate environment, but Moody's notes the rated S-REITs are insulated as more than half of their outstanding debt is tied to fixed interest rates.
Finally, the sector's debt maturity profile is also healthy as majority of debt will be maturing in five calendar years and beyond. Moody's notes that sector's debt maturity profile is now well staggered, such that no more than 30% of debt needs refinancing in any single year.




















 Read Here
 Advertise
 Sign Up