CapitaCommercial Trust distributable income up 11.3% in FY2010
Distributable income came in at $221 million, according to CapitaCommercial Trust Management Limited.
FY 2010 estimated distribution per unit of 7.83 cents is a 10.9% y-o-y increase from FY 2009 DPU of 7.06 cents.
For the financial period 1 October 2010 to 31 December 2010 (4Q 2010), a distributable income of S$54.7 million was achieved. 4Q 2010 estimated DPU of 1.94 cents is 3.2% above 4Q 2009 DPU of 1.88 cents.
The estimated DPU for financial period 1 July 2010 to 31 December 2010 (2H 2010) is 3.93 cents, which is 5.4% above the same period last year. The books closure date is on Friday, 28 January 2011. Unitholders can expect to receive this payout on Monday, 28 February 2011. Based on the closing price of $1.51 per unit on 18 January 2011, CCT’s distribution yield is 5.2%.
An independent valuation records the value of the Trust’s investment properties to be $5,475.4 million as at 31 December 2010. This translates to a S$227.8 million net fair value gain. The valuation has excluded Starhub Centre which was divested on 16 September 2010. The total asset size of the Trust as at end-December 2010 is $6.2 billion. The net asset value per unit after adjusting for the 2H 2010 distributable income to unitholders, is $1.47.
Mr. Richard Hale, Chairman of the Manager, said, “CapitaCommercial Trust’s full-year report card is in line with its past performance, which has been consistently healthy. This year, the Trust delivered a credible growth in distributable income and distribution per unit of 7.83 cents. It has benefited from higher rents and occupancies at its properties, primarily due to proactive leasing. We have also done well in managing the interest cost and operating expenses of the properties. During the year, all the Trust’s refinancing due in 2010 was completed well ahead of maturities.”
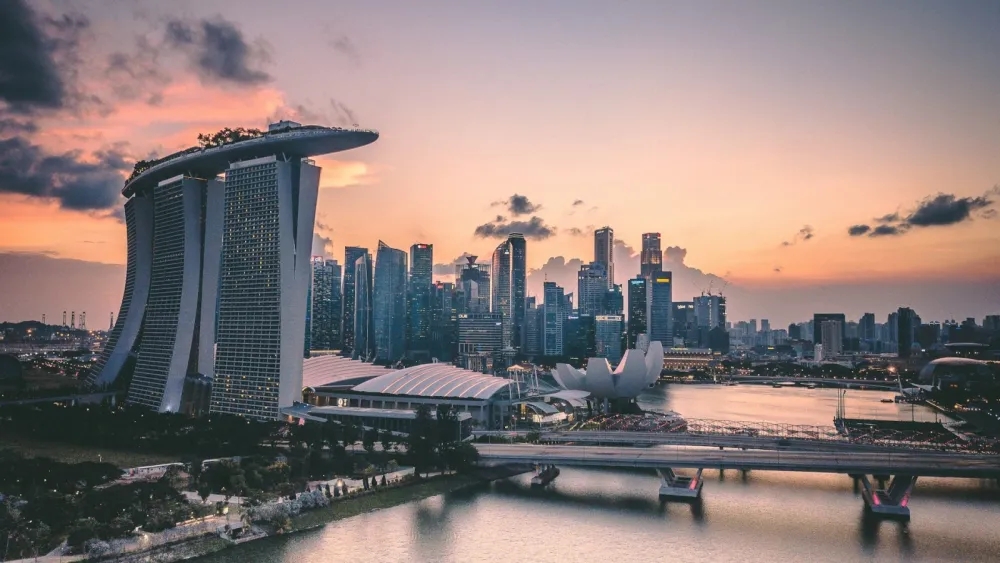
“As part of our portfolio reconstitution strategy to unlock the value of assets that have reached the optimal stage of their life cycles, we divested two non-Grade A office buildings with significant capital gains. Other initiatives included the asset enhancement plan to reposition Six Battery Road, a Grade A office building, to capture the office market recovery. The building is the first operating office building in Singapore to be conferred with a Green Mark Platinum award by the Building and Construction Authority. This is the highest level of ranking for the Green Mark awards in recognition of best practices in environmental design and performance. Additionally, we further strengthened the Trust’s financial flexibility by lowering its gearing ratio to 28.6% from 31.5%. We also prepaid a secured term loan of $142.6 million due in 2012. With a strong balance sheet, we are actively evaluating investment opportunities this year.”
Ms. Lynette Leong, Chief Executive Officer of the Manager, said, “In tandem with the optimistic economic outlook for Singapore and Asia, the resultant office market recovery and our proactive tenant engagement, we continue to experience positive growth in office demand from our tenants. Our portfolio’s occupancy rate is now 99.3% and our Grade A offices are fully occupied, better than the market average occupancy rates of 95.3% and 97.3% respectively for the overall and Grade A office buildings in Singapore’s core Central Business District. Wilkie Edge’s occupancy rate is now 98.4%, up from 78.4% at end-October 2010. In fact, the full occupancy at our Grade A offices often makes it challenging for us to meet our tenants’ office expansion needs. We continue to concentrate our leasing efforts to understand and respond to their needs through pre commitments or proactive negotiations in line with our space availability and current and projected market conditions.”





















 Read Here
 Advertise
 Sign Up