Is the worst over for ComfortDelGro?
Its taxi fleet shrank to 12,627, but the rate of change is slower compared to last year.
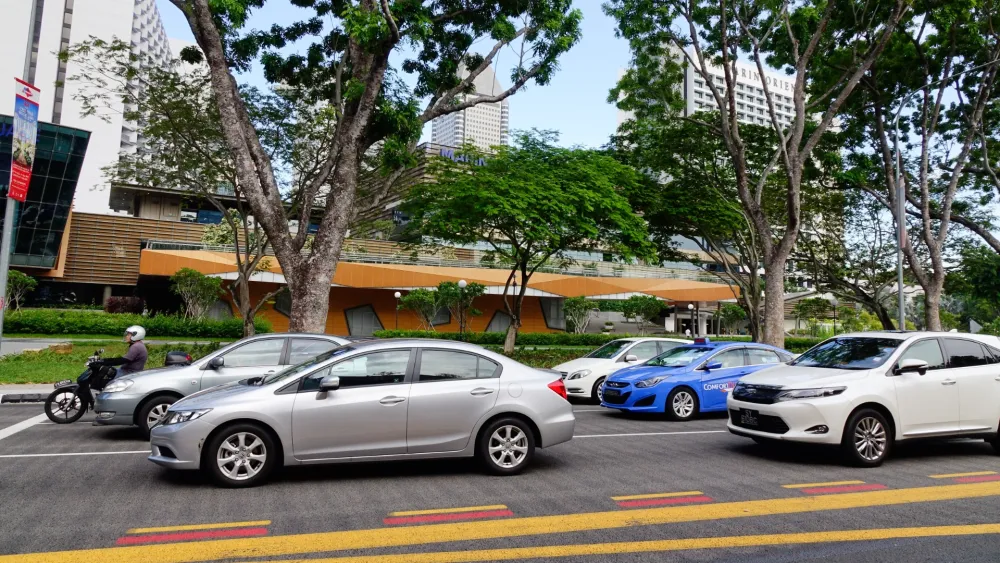
ComfortDelGro’s taxi fleet in April stood at 12,627, indicating a somewhat flat decline from March (12,687). Even if it still down from 15,800 in April 2017, this could show that the worst is already over for the taxi firm, DBS Equity Research said.
DBS Equity Research analyst Andy Sim noted that ComfortDelGro’s taxi fleet could grow back by 13,000 as it said it placed orders for 700 new taxis. Of these, 200 taxis have been delivered whilst 500 others have yet to be awarded, most likely in 2H2018.
Moreover, Grab has reduced drivers’ incentives and marketing promotions, that would result in lower income for Private Hire Car (PHC) drivers, making it less lucrative. There was also a net increase in total number of 388 Taxi Driver’s Vocational Licence (TDVL) holders to 95,895 in April 2018 – a first since December 2016.
“We believe this trend should continue and will bode well for ComfortDelGro’s taxi operations,” Sim said.
The potential entry of Go-Jek should not hurt the taxi firm too much, either, as both companies are speculated to form a partnership with each other. However, here has been no confirmed indications of this.
“That said, we believe that the likelihood of irrational competition is low given Grab's already-dominant position. In fact, Go-Jek has established local companies for Vietnam and Thailand, but we have yet to see its progress in Singapore,” Sim said.
“We believe that in the event Go-Jek eventually starts operating in Singapore and in partnership with ComfortDelGro, this could provide a catalyst for share price as it could be seen as an additional avenue for ComfortDelGro to be within the private car hire space. This could complement its existing taxi business, as well as other ancillary businesses such as automotive engineering, insurance, and vehicle inspection, among others,” the analyst added.
In a forecast, ComfortDelGro’s profits are expected to jump 5% per annum for 2019 to 2020 from a 3% decline in 2018. Sim said DBS Equity Research raised the forecast due to higher taxi fleet assumption and contribution from recent acquisitions.
























 Read Here
 Advertise
 Sign Up