Capital Reduction in Singapore: 2026 Compliance Guide

Quick answer: A Singapore company limited by shares reduces capital by special resolution, either backed by a directors’ solvency statement (sections 78B and 78C) or approved by the court (sections 78G and 78I). On the solvency route, creditors have six weeks to apply to court, then the company files with ACRA between weeks six and eight, and the reduction takes effect once ACRA records it.

Capital reduction in Singapore is the legal process by which a company lowers its paid-up share capital under the Companies Act 1967, Sections 78A through 78K. Two primary methods are available: the solvency-statement route (Sections 78B–78F) and the court-approved route (Sections 78G–78K). Both apply to private and public companies limited by shares, though the procedural requirements differ by company type and transaction structure.

Key procedural elements at a glance:

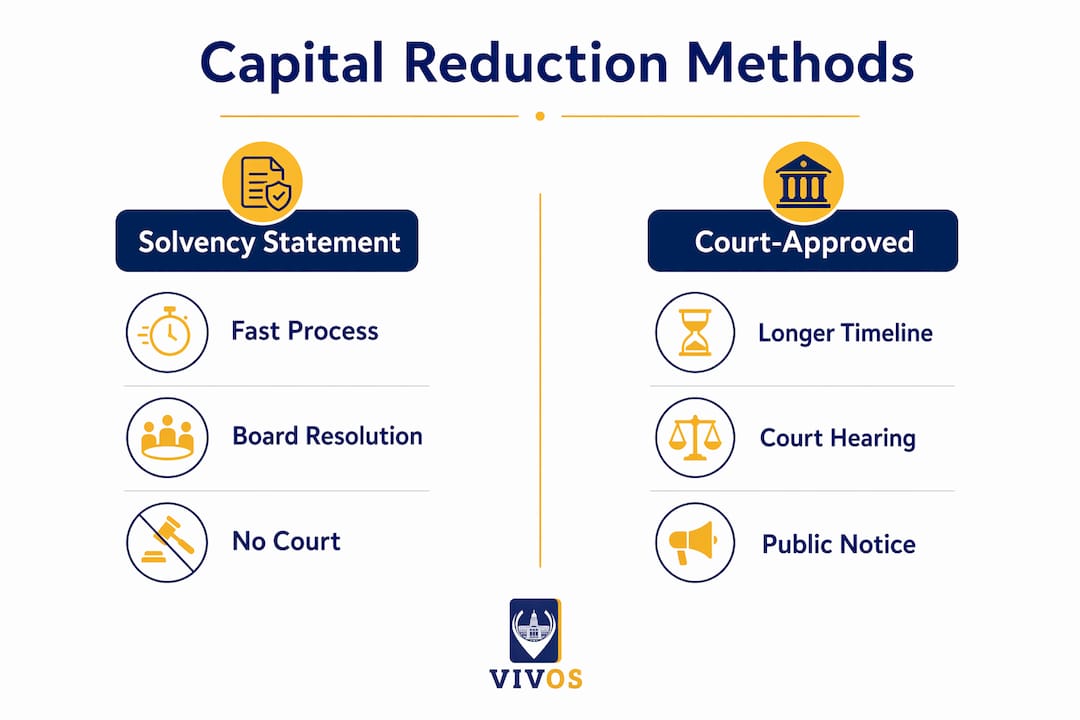
  • Solvency-statement route: Faster, no court involvement; directors make a solvency declaration before the special resolution.
  • Court-approved route: Requires a court order before the reduction takes effect; used when creditor risk is elevated.
  • Special resolution: Required under both methods; must be passed by at least three-fourths of the votes cast by members entitled to vote (section 184).
  • Creditor objection window: Under the solvency-statement route, creditors have six weeks beginning with the resolution date to apply to court to cancel the resolution (section 78D); the court route instead uses a court-settled creditor list (section 78H).
  • ACRA filing: Capital reduction takes effect only once ACRA records the reduction information in the company register.
  • Solvency statement timing: Made within 20 days before the resolution for private companies; within 30 days for public companies.

Table of Contents

Why do Singapore companies reduce their share capital?

Companies pursue share capital reduction for a range of commercial and financial reasons, most of which relate to correcting a mismatch between the capital structure on paper and the actual financial position of the business.

Common motivations include:

  • Returning surplus capital to shareholders: When a company holds more paid-up capital than its operations require, reducing share capital and distributing the excess is a structured way to return value.
  • Canceling lost or unrepresented capital: Under Section 78A, a company may cancel paid-up capital that is no longer backed by available assets, cleaning up the balance sheet after losses.
  • Extinguishing unpaid capital liabilities: Reducing or eliminating the liability on shares where capital has not been called up simplifies the company’s obligations to shareholders.
  • Simplifying the balance sheet post-restructuring: After an asset sale, merger, or group reorganization, excess capital on the books can distort financial ratios and complicate reporting.
  • Facilitating capital restructuring: Adjusting the capital base can be a prerequisite for refinancing, dividend payments, or preparing the company for a new investment round.

The Singapore capital return process is not a shortcut. Each motivation must be weighed against the statutory requirements and creditor protections that apply, particularly where distributions of cash or assets are involved.


Infographic comparing capital reduction methods

How do the two capital reduction methods work, step by step?

Solvency-statement route (Sections 78B–78F)

This is the preferred path for most private companies. It avoids court involvement entirely, provided directors can honestly make the required solvency declaration.

  1. Board solvency declaration: All directors make a solvency statement confirming the company can pay its debts as they fall due within 12 months, and that the value of assets will not fall below liabilities after the reduction. For private companies, this statement must be made within 20 days before the special resolution date. For public companies, the window extends to 30 days.
  2. Pass the special resolution: Shareholders approve the reduction by special resolution (at least three-fourths of the votes cast). The solvency statement must be available for inspection by members at the meeting.
  3. Publish public notice: Within eight days of the resolution date, the company must file a publication for proposed reduction of share capital with ACRA, setting out the special resolution, the resolution date, the amount of share capital reduced and the number of shares cancelled (sections 78B(1)(c) and 78C(1)(c)). It can be filed on the same day as the special resolution.
  4. Creditor inspection period: For six weeks from the resolution date, the solvency statement must be available at the company’s registered office for any creditor to inspect, free of charge.
  5. Wait out the creditor objection window: During the six weeks beginning with the resolution date, a creditor whose debt or claim would be admissible in proof in a winding up may apply to the court to cancel the resolution (section 78D). If no application is made, the company proceeds to filing.
  6. File with ACRA via Bizfile: File the special resolution within 14 days of the resolution date. If no creditor applies to court, file the share capital reduction under section 78E after the six-week window ends and before the end of eight weeks from the resolution date, lodging the solvency statement, a directors’ statement that no cancellation application was made, and the reduction information. The reduction takes effect once ACRA records it.

Statutory callout: The six-week creditor objection period is legally mandatory and cannot be shortened. Under section 78E, the reduction takes effect only if the filing is made after the six-week window ends and before the end of week eight, and only once ACRA records it.

Court-approved route (Sections 78G–78K)

This route is available to all companies limited by shares as an alternative to the solvency-statement method. It is typically used when the reduction involves creditor risk that the solvency-statement route cannot adequately address.

  1. Pass the special resolution: The same special resolution threshold applies (at least three-fourths of the votes cast).
  2. Apply to the court: The company applies for a court order confirming the reduction under Section 78I. The court has discretion to approve unconditionally or impose conditions.
  3. Court safeguards for creditors: Where the reduction reduces liability on unpaid share capital, returns paid-up capital to shareholders, or the court so directs, the court settles a list of qualifying creditors (section 78H). It must not approve the reduction unless each listed creditor has consented, is secured or adequately safeguarded, or needs no security given the company’s assets after the reduction (section 78I(2)).
  4. Lodge court order with ACRA: Once the court issues its order, the company must lodge the court approval with ACRA within 90 days. The reduction does not take effect until ACRA records the information.

Common pitfalls across both routes:

  • Missing the 8-week filing deadline after the creditor objection window closes.
  • Missing the eight-day deadline to file the publication for proposed reduction of share capital with ACRA.
  • Directors signing a solvency statement without adequate financial analysis.
  • Failing to make the solvency statement available for creditor inspection throughout the full six-week period.
  • Filing the section 78E reduction before the six-week creditor window has ended.

What rights do creditors have during a capital reduction?

Creditor protection is built into the statutory framework at multiple points. The six-week objection window is the central mechanism, but it operates alongside several other requirements.

  • Public notice obligation: The company must file a publication for proposed reduction of share capital with ACRA within eight days of the resolution date.
  • Solvency statement availability: Throughout the six-week period following the special resolution, the solvency statement must be available at the company’s registered office for creditor inspection at no charge.
  • Formal objection right: Under the solvency-statement route, a creditor whose debt or claim would be admissible in proof in a winding up may apply to the court to cancel the resolution during the six-week window (section 78D). Under section 78F, the court must cancel the resolution if the creditor’s debt or claim is still outstanding, unsecured and without adequate safeguards, unless security is unnecessary given the company’s assets after the reduction; otherwise it dismisses the application.
  • If objections arise: The company must address the objection through court proceedings. This may involve securing the creditor’s claim, obtaining a court dismissal of the objection, or abandoning the reduction and re-filing after resolving the dispute.

Creditor protection compliance is not optional. If the solvency statement is not made available to members or creditors as required, every officer in default commits an offence, although the breach does not by itself invalidate the resolution (sections 78B(5) and 78C(5)).


What are the ACRA filing and publication requirements?

Filing accuracy and timing determine whether the reduction actually takes effect. The process involves several distinct steps, each with its own deadline.

Publication requirements:

  • File a publication for proposed reduction of share capital with ACRA within eight days of the resolution date (ACRA allows it on the same day as the special resolution).
  • The publication must state the amount of capital being reduced, the number of shares canceled, and the resolution date.

Filing steps via Bizfile:

  1. File the special resolution with ACRA within 14 days of the resolution date.
  2. Lodge the solvency statement together with the resolution copy within 15 days of the resolution date (for public companies under Section 78C).
  3. Wait for the six-week creditor objection period to expire without a valid court application from any creditor.
  4. File the share capital reduction by special resolution (section 78E) on Bizfile between six and eight weeks after the resolution date, provided no creditor has applied to court.
  5. ACRA records the reduction: Capital reduction takes effect at this point. ACRA updates the company’s share capital register accordingly.

For the court-approved route, the additional step is lodging the court order with ACRA within 90 days of the order date. The reduction does not take effect until ACRA records that information.

Key deadlines summary:

Milestone Deadline
File special resolution with ACRA Within 14 days of resolution date
Lodge solvency statement (public companies) Within 15 days of resolution date
Creditor objection window 6 weeks from resolution date
File final capital reduction return After 6 weeks and before the end of 8 weeks from resolution date
Lodge court order (court-approved route) Within 90 days of court order

How does capital reduction differ from a share buyback?

Both mechanisms reduce the amount of capital held by a company, but they operate under different statutory frameworks and serve different purposes.

  • Statutory basis: Capital reduction is governed by Sections 78A–78K of the Companies Act. Share buybacks are regulated separately under Sections 76B to 76G.
  • Shareholder binding: Capital reduction, once approved by special resolution, is binding on all shareholders. A share buyback is optional for individual shareholders; the company makes an offer and shareholders choose whether to participate.
  • Voting threshold: Capital reduction requires a special resolution (at least three-fourths of the votes cast). Market purchases and equal-access off-market buybacks must be authorised in advance in general meeting (sections 76C and 76E), while a selective off-market buyback needs a special resolution (section 76D).
  • Creditor protections: Capital reduction carries mandatory creditor notification and objection rights. Share buybacks do not trigger the same six-week creditor window.
  • Tax treatment: Whether an amount returned in a capital reduction is taxable depends on the facts of the transaction and each shareholder’s position, so confirm the tax treatment with a tax adviser or IRAS before paying out. Share buyback proceeds may be treated differently depending on how the transaction is structured; consulting a tax professional and reviewing Singapore capital gains tax implications is advisable.
  • Strategic use: Share buybacks are often used to manage earnings per share, reward shareholders selectively, or absorb employee share option exercises. Capital reduction is more commonly used for structural balance sheet corrections or returning large surplus capital to all shareholders proportionally.

Understanding which mechanism fits the company’s situation requires analysis of the shareholding structure, financial position, and intended outcome. The two are not interchangeable.


How VIVOS supports companies through the capital reduction process

VIVOS provides end-to-end corporate secretarial services covering every stage of the capital reduction process, from initial structuring through to ACRA filing completion.

  • Route selection advisory: VIVOS assesses the company’s financial position and shareholding structure to recommend the appropriate method, whether solvency-statement or court-approved.
  • Solvency statement preparation: The team assists directors in gathering the financial documentation required to support a valid solvency declaration, reducing the risk of a defective statement.
  • Special resolution drafting and filing: VIVOS prepares and files the special resolution with ACRA within the required 14-day window.
  • Public notice compliance: Filing the publication for proposed reduction of share capital with ACRA within eight days of the resolution.
  • Creditor objection monitoring: VIVOS tracks the six-week objection period and advises on next steps if a creditor files a court application.
  • Bizfile submissions: The section 78E filing is made on Bizfile between weeks six and eight, with verification that ACRA has recorded the reduction.
  • Court-approved route support: Where court approval is required, VIVOS coordinates with legal counsel and manages the lodgment of court orders within the 90-day window.

Pro Tip: Directors should not sign a solvency statement without a current set of management accounts. A statement made without adequate financial analysis exposes directors to personal liability under the Companies Act.

VIVOS also supports post-reduction corporate governance and meeting management, including updating the company’s statutory registers and issuing revised share certificates where applicable.


How long does a capital reduction typically take in Singapore?

The timeline differs materially between the two routes.

Solvency-statement route: The statutory minimum is just over six weeks from the resolution date, because the section 78E filing can be made only after the six-week creditor window ends and must be made before the end of week eight. Preparing management accounts and the solvency statement before the resolution adds time.

Overhead hands reviewing timeline documents

Court-approved route: The court route has no fixed statutory timetable. It depends on the court hearing and any creditor list under section 78H. After the order, the company must file it with ACRA within 90 days of the order date, or within a longer period ACRA allows on application.

Practical factors that extend timelines under either route include a late publication filing, creditor applications requiring court resolution, and errors in Bizfile submissions that require correction before ACRA will record the reduction. Engaging a corporate secretarial firm with direct Bizfile experience reduces the risk of procedural delays.


What happens to company records and shareholder rights after a capital reduction?

Once ACRA records the reduction, the changes take effect immediately and are reflected across the company’s statutory records.

Updates to company records:

  • The company’s share capital register is adjusted to reflect the reduced capital amount and, where applicable, the reduced number of shares.
  • ACRA updates the company’s public profile on Bizfile to show the new paid-up capital figure.
  • Where shares are canceled, the register of members is updated and affected shareholders receive revised documentation.

Effect on shareholder rights:

Under Section 78K of the Companies Act, a member’s liability in respect of any share is capped at the difference between the issue price of the share and the aggregate of the amount paid up plus the amount reduced. Shareholders cannot be called upon to contribute more than that difference, regardless of future company obligations.

Where the reduction involves a return of capital, shareholders receive the distribution as specified in the approved resolution. Its tax treatment depends on the facts, so companies should confirm it with a tax adviser or IRAS, particularly where assets rather than cash are returned.

Post-reduction, the company’s financial accounting and reporting must reflect the adjusted equity position. Directors should also review whether any loan covenants, banking facilities, or contractual arrangements reference minimum capital thresholds, as a reduction may trigger review clauses or require lender consent.


VIVOS handles your capital reduction from start to finish

Capital reduction is procedurally precise. If the section 78E filing window is missed, the reduction does not take effect on that resolution.

VIVOS

VIVOS offers a fully managed capital reduction service for Singapore companies, covering route selection, solvency statement support, resolution drafting, ACRA publication filing, creditor objection monitoring, and all Bizfile filings. Directors get a clear timeline, accurate documentation, and a team that has navigated ACRA’s requirements across multiple transaction types.

For companies weighing whether capital reduction or a share buyback better fits their situation, VIVOS’s corporate advisory team provides a structured analysis before any resolution is passed, avoiding the cost of choosing the wrong mechanism.

Contact VIVOS to discuss your company’s capital structure and get a clear plan for completing the reduction within statutory deadlines.


Key Takeaways

Capital reduction in Singapore requires strict adherence to the Companies Act 1967, with the solvency-statement route taking just over six weeks at the statutory minimum and the court-approved route depending on the court timetable.

Point Details
Two statutory routes Solvency-statement (Sections 78B–78F) and court-approved (Sections 78G–78K) are the only lawful methods.
Mandatory six-week window Under the solvency-statement route, creditors have six weeks after the special resolution to apply to court; this period cannot be shortened.
ACRA filing deadline The section 78E filing must be made on Bizfile after six weeks and before the end of eight weeks from the resolution date.
Solvency statement timing Directors must make the statement within 20 days before the resolution (private) or 30 days (public).
VIVOS end-to-end support VIVOS manages the full capital reduction process, from route selection through to ACRA recording.

FAQ

What is a capital reduction in Singapore?

A capital reduction lowers a company’s share capital under Division 3A of the Companies Act 1967 (sections 78A to 78K). Section 78A lets a company reduce or extinguish liability on unpaid share capital, cancel paid-up capital that is lost or unrepresented by available assets, or return paid-up capital that exceeds its needs. A company may reduce share capital only through a procedure in Division 3A, and its constitution can restrict that power.

What do you file with ACRA for a capital reduction?

On the solvency route, file the special resolution within 14 days and the publication for proposed reduction of share capital within eight days of the resolution date; both can go in on the same day. If no creditor applies to court, file the share capital reduction under section 78E between six and eight weeks after the resolution, with the solvency statement and a directors’ statement. On the court route, file the court order within 90 days of the order date.

What are the two ways to reduce share capital in Singapore?

The first is a special resolution supported, where required, by a solvency statement from all directors, under section 78B for private companies or section 78C for public companies. No court approval is needed, though creditors can apply to court within six weeks to cancel the resolution. The second is a special resolution approved by court order under sections 78G and 78I. Either way, a special resolution needs at least three-fourths of the votes cast by members entitled to vote.

What must a capital reduction solvency statement confirm?

All directors must state that the company can pay its debts as they fall due over the next 12 months (or in full within 12 months of an intended winding up) and that its assets will not be less than its liabilities, including contingent ones, after the reduction (section 7A). It must be made no earlier than 20 days before the resolution, or 30 days for a public company.

How long is the creditor objection period for a capital reduction?

Six weeks beginning with the resolution date. During that time, a creditor whose debt or claim would be admissible in proof in a winding up may apply to the court to cancel the resolution (section 78D), and the solvency statement must be open to creditors free of charge at the registered office. The period cannot be shortened, because the section 78E filing is allowed only after it ends. The court route has no such window and uses the creditor list in section 78H instead.

Is a capital reduction taxable in Singapore?

The Companies Act sets the procedure for a capital reduction, not its tax result. Whether an amount returned to shareholders is taxable depends on the facts of the transaction and each shareholder’s position, so confirm the tax treatment with a tax adviser or IRAS before the company pays out.

Sources

Recents Blogs

新加坡海外收入汇回:2026年公司与个人的纳税规则与免税条件

Ray Tay

海外收入汇回新加坡何时需纳税?本文解析第10(25)条“汇入”定义、第13(8)条三项免税条件、外国税收抵免、第10L条及文件留存要求。

Long-Term Visit Pass for Parents in Singapore: Who Qualifies? (2026)

Ray Tay

Employment Pass holders can bring their parents to Singapore on a Long-Term Visit Pass only if they earn a fixed monthly salary of at least…

新加坡公司银行签字人变更:流程、董事会决议与文件

新加坡公司如何变更银行授权签字人:董事会决议怎么写,银行要哪些文件,与ACRA董事变更怎样衔接,海外董事如何完成签名核验,一文讲清。

VIVOS WeChat contact
Whatsapp
Licensed Singapore Corporate Service Provider (ACRA FA20240323, MOM EA 24S2425) · Rated 5.0 on G2