


新加坡海外收入汇回:2026年公司与个人的纳税规则与免税条件

Ray Tay
海外收入汇回新加坡何时需纳税?本文解析第10(25)条“汇入”定义、第13(8)条三项免税条件、外国税收抵免、第10L条及文件留存要求。
Published: 8 August 2026 · Last reviewed: 16 October 2026 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
Quick answer – best corporate credit cards in Singapore (2026): If you need a real credit line, the strongest options are bank-issued business cards: the American Express Singapore Airlines Business Credit Card for frequent flyers (KrisFlyer miles, lounge access), and the UOB and DBS business cards for cashback or points with credit terms. Popular fintech corporate cards from Aspire, Airwallex and Wise are debit or prepaid cards, not credit cards – they have no credit line but typically charge no annual fee and offer near-interbank FX, which makes them the most common alternative to a business credit card.
Quick answer: There is no single best corporate card; it depends on how your business spends. As of October 2026, Singapore bank cards charge about 3% to 3.25% on foreign-currency spend, so FX-heavy SMEs often pay less with multi-currency debit cards from Airwallex, Wise or Aspire. Bank business cards from DBS, UOB, OCBC or Maybank suit firms that need a credit line.
Shortlist by use case:
Immediate next step: Ask your finance manager or a director to pull three documents now: your ACRA business profile, the most recent Notice of Assessment (or audited accounts) and the director’s NRIC or passport. Most issuers start with these; banks often ask for more, such as two years of Notices of Assessment or audited financials.
For most Singapore SMEs, the right corporate card is determined by FX exposure and expense-control needs, not by headline rewards rates.
| Point | Details |
|---|---|
| Choose category first | Fintech debit for startups and FX-heavy SMEs; bank credit for travel, rewards, or credit-building needs. |
| FX cost dominates for cross-border spend | Bank cards charge about 3% to 3.25% on foreign-currency spend: about S$6,000 to S$6,500 a year on S$200,000 of overseas spend, before any FX rebate. |
| Controls beat marginal reward differences | Virtual cards, MCC locking, and direct accounting integrations save more than a 0.5% cashback differential at typical SME spend levels. |
| Document preparation determines timeline | Fintech accounts open online; bank cards add a credit assessment, so complete documents save the most time. |
| VIVOS supports bank onboarding | VIVOS prepares board resolutions and document sets and makes bank introductions for foreign-founded companies applying for Singapore business cards. |
The table below maps the core dimensions across the main card categories and representative issuers. Use it to narrow to two or three candidates, then read the per-category breakdowns in the next section.
| Card / issuer | Best for | Type | Annual fee (as of Oct 2026) | Foreign-currency fee | Rewards | Key eligibility | Liability |
|---|---|---|---|---|---|---|---|
| DBS World Business Card | Foreign-currency spend on credit | Credit | S$414.20 incl. GST (first year waived) | 3.25% | 2% on foreign-currency spend; 1% local dining, entertainment and travel; 0.3% other | S$80,000 minimum income | Set by the card agreement; DBS offers a full corporate liability version |
| DBS Platinum Business Card | Entry-level bank credit | Credit | S$196.20 incl. GST (first year waived) | 3.25% | See DBS page | Age 21+, S$30,000 minimum income | Company primarily liable under DBS’s joint and several agreement |
| UOB Signature/World Business Card | Mainstream bank credit | Credit | S$183.36 | 3% | 0.3% cash rebate | Documents listed by entity type | Sole corporate or joint and several programmes |
| OCBC Business Credit Card | Locally owned SMEs | Credit | S$194.40 incl. GST | 3.25% | 1% on foreign-currency spend; 0.2% local | At least 30% Singaporean or PR-owned; turnover of S$20 million or less; OCBC business account | Authorised signatories jointly and severally liable |
| Maybank Business Platinum Mastercard | Established local SMEs | Credit | S$196.20 (first two years waived) | Up to 3.25% | 1 TREATS point per S$1 | 2+ years operating; S$200,000+ turnover; at least one local director | Per card agreement |
| HSBC Commercial Cards | Larger companies needing controls | Corporate programme | Programme-based | Per programme terms | Programme-based | Assessed per programme (no published threshold) | Corporate; fraud protection and liability waiver insurance |
| Amex Singapore Airlines Business Credit Card | Singapore Airlines and Scoot travel | Credit | S$400 incl. GST | 3.25% (card terms) | HighFlyer points, convertible 1:1 to KrisFlyer miles | See Amex page | Business and basic card member jointly and severally liable |
| Aspire | Startups; ad and SaaS spend | Debit (fintech) | No monthly fee on Basic; extra physical card S$15 | None on SGD or USD; other currencies Visa rate plus a fee from 0.22% | 1% cashback on ad and SaaS (Basic) | Singapore-registered business | Company (spends own balance) |
| Airwallex | FX-heavy, cross-border | Debit (fintech) | S$0 on the Explore plan | None from a matching balance; 1% auto-conversion otherwise | None | Singapore-registered business | Company (spends own balance) |
| Wise Business | Multi-currency payments | Debit (fintech) | S$99 one-time setup (includes first card) | Mid-market rate plus a fee from 0.19% | None | Wise Business account | Company (spends own balance) |
Fees and rates are taken from each issuer’s own pages as of October 2026 and change often, so confirm them at the point of application.
How to weigh the columns for your profile:
Pick-by-use-case badges:
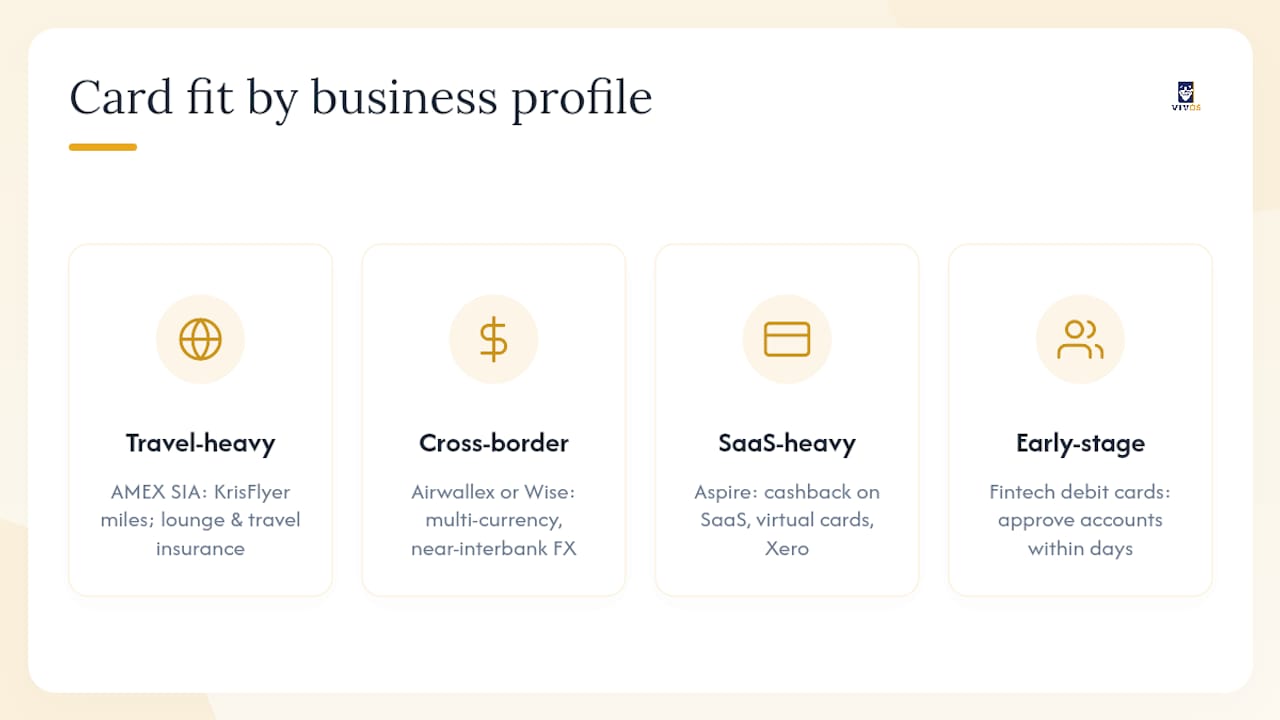
Travel-heavy SME (frequent flights, client entertainment)
The American Express Singapore Airlines Business Credit Card is the clearest fit for firms that fly Singapore Airlines or Scoot. It earns HighFlyer points (up to 8 per S$1 on Singapore Airlines and Scoot bookings and 1.2 on other spend) that convert 1:1 to KrisFlyer miles, capped at 150,000 miles a year. Lounge access is not a card benefit: it comes with KrisFlyer Elite Gold, which goes to the first person in a business to spend S$15,000 or more on Singapore Airlines and Scoot bookings within 12 months. The annual fee is S$400 including GST as of October 2026, so the card rewards consistent travel spend.
Cross-border supplier business (paying overseas vendors, FX invoices)
Airwallex or Wise Business. Both hold balances in multiple currencies, which avoids the roughly 3% to 3.25% FX fee that bank cards charge. Airwallex publishes a markup of 0.40% above interbank for major currencies, and Wise converts at the mid-market rate plus a fee from 0.19%. Neither earns traditional rewards points, so you give up cashback in exchange for FX savings. For businesses with significant overseas payables, the FX saving usually exceeds any cashback foregone.
Digital-marketing or SaaS-heavy SME
Aspire. Its Basic plan pays 1% cashback on ad and SaaS spend (Premium, at S$15 a month, pays 1.2% on eligible spend), issues virtual cards and syncs transactions with Xero. There is no monthly fee on the Basic plan. Spending draws on your account balance, although Aspire also advertises an advance limit.
Early-stage startup with minimal revenue
Fintech debit cards (Aspire, Airwallex, Wise) are the practical first step. Bank cards set their own thresholds: the DBS Platinum Business Card asks for S$30,000 minimum income, while Maybank requires two years of operation and S$200,000 turnover. Fintech accounts are opened online with business registration and director details. Once the business has two years of filed accounts, a bank card for credit and travel benefits becomes easier to get.
A structured checklist prevents the most common mistake: picking a card based on headline rewards while ignoring the fees and friction that accumulate over 12 months.
Step-by-step evaluation checklist:
Red flags to watch for in T&Cs:
Pro Tip: Ask the card provider specifically whether their expense feed uses a direct API connection to your accounting software or a manual CSV export. A direct API connection means transactions post automatically with merchant names and amounts; a CSV export means someone on your team uploads a file each month. That distinction typically saves 3–5 hours of bookkeeping per month at scale.
DBS World Business Card / DBS Platinum Business Card
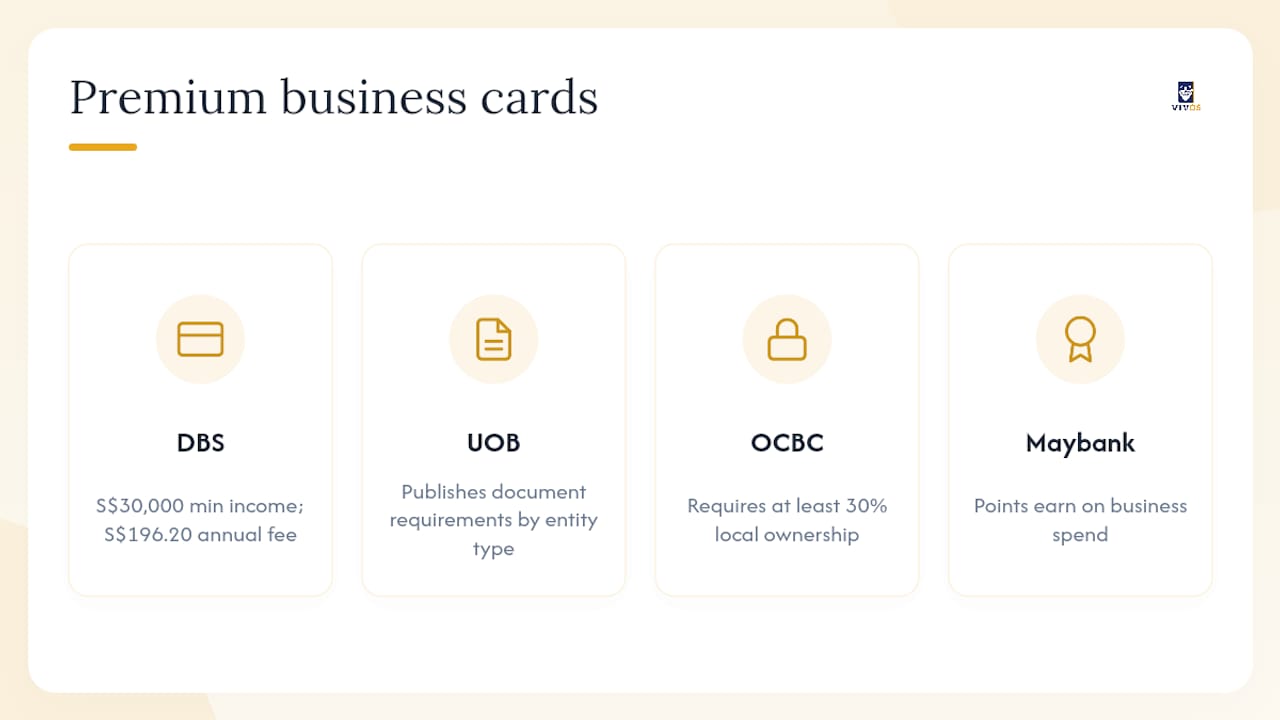
As of October 2026, the DBS Platinum Business Card costs S$196.20 a year including GST (first year waived) and requires S$30,000 minimum income. The DBS World Business Card costs S$414.20 including GST, requires S$80,000 minimum income and pays 2% back on foreign-currency spend, 1% on local dining, entertainment and travel and 0.3% on other spend. DBS charges 3.25% on foreign-currency transactions (1% card network plus 2.25% DBS). On liability, DBS’s Platinum Business agreement makes the company primarily liable, and the World Business Card has a full corporate liability version.
UOB Signature / World Business / Regal Business Metal
UOB sells the business card range as one product, the Signature/World Business Card, at S$183.36 a year with a 0.3% cash rebate; the Regal Business Metal and Empire World Business cards are by invitation. UOB’s business card agreement sets a 3% fee on foreign-currency transactions. UOB publishes document requirements by entity type on its product pages, and offers both sole corporate liability and joint and several liability programmes.
OCBC Business Credit Card
The OCBC Business Credit Card pays 1% on foreign-currency spend and 0.2% on local spend, with an annual fee of S$194.40 including GST. The company must be incorporated in Singapore, at least 30% owned by Singaporeans or PRs, with turnover of S$20 million or less and an OCBC business account; the applicant must be 21 or older with at least S$30,000 income. The ownership rule excludes many foreign-owned companies.
Maybank Business Platinum Mastercard
The Maybank Business Platinum Mastercard costs S$196.20 a year (first two years waived), earns 1 TREATS point per S$1 and charges up to 3.25% on foreign-currency spend. The company must be ACRA-registered with at least one Singapore citizen or PR director, have operated for two years or more and have turnover of at least S$200,000.
HSBC Commercial Cards (including Virtual Card and World Corporate Mastercard)
HSBC’s Commercial Cards Programme is positioned as an expense-management platform rather than a simple payment card. In Singapore it covers the World Corporate Mastercard, the Corporate Card for Purchases, the Central Travel Account, a Virtual Card and a USD Corporate Card. The cards carry fraud protection and liability waiver insurance, and HSBC’s virtual card is designed for companies that bear sole liability. HSBC does not publish a revenue threshold; eligibility is assessed per programme.
Citi Corporate Card (discontinued in Singapore)
Citi discontinued the commercial credit cards issued by Citibank Singapore Limited, which could not be used after 30 June 2026 (Citi notice). Commercial cards from Citibank N.A. continue only as an institutional offering, so most SMEs should compare the other options here.
American Express Singapore Airlines Business Credit Card
The American Express Singapore Airlines Business Credit Card is a credit card, not a charge card. It earns HighFlyer points that convert 1:1 to KrisFlyer miles, capped at 150,000 miles a year. Lounge access is not a card benefit. As of October 2026 the annual fee is S$400 including GST, and the card terms set a 3.25% foreign-currency fee. The business and the basic card member are jointly and severally liable.
Aspire Corporate Card
No monthly fee on the Basic plan (Premium is S$15 a month, excluding GST); each user gets one free physical card, with extra physical cards at S$15. Cashback is 1% on ad and SaaS spend on Basic, or 1.2% on eligible spend on Premium. There is no FX fee on SGD or USD card spend; other currencies convert at Visa’s rate plus an Aspire FX fee that Aspire says starts from 0.22%. Transactions sync with Xero. On regulation, Aspire FT Pte. Ltd. provides its payment services under a temporary exemption from licensing under the Payment Services Act and received in-principle approval for a Major Payment Institution licence in October 2024 (Aspire licences).
Airwallex Corporate Card
Airwallex (Singapore) Pte. Ltd. holds a Major Payment Institution licence from MAS (MAS directory) and issues the cards. There is no card fee on the free Explore plan; paid plans start at S$79 a month. Card spend from a matching currency balance has no foreign transaction fee, conversions carry a published markup of 0.40% above interbank for major currencies (0.60% for others), and card spend in a currency you don’t hold is auto-converted with a 1% fee. Best suited to businesses with material overseas payables or receivables in several currencies.
Wise Business Card
Wise converts at the mid-market rate plus a fee from 0.19%, varying by currency. Opening a business account costs a one-time S$99, which includes the first card; there is no annual card fee and extra cards cost S$4. The card cannot be used at ATMs in Singapore. Wise Asia-Pacific Pte. Ltd. is a Major Payment Institution licensed by MAS (MAS directory). Wise offers fewer accounting integrations than Aspire or Airwallex, but its FX pricing is among the clearest in this category.
Representative fee and eligibility summary:
| Card / issuer | Annual fee | Foreign-currency fee | Eligibility | Liability |
|---|---|---|---|---|
| DBS Platinum Business Card | S$196.20 incl. GST | 3.25% | S$30,000 minimum income | Company primarily liable (joint and several agreement) |
| DBS World Business Card | S$414.20 incl. GST | 3.25% (2% rebate on foreign-currency spend) | S$80,000 minimum income | Full corporate liability version available |
| UOB Signature/World Business Card | S$183.36 | 3% | Documents by entity type | Sole corporate or joint and several |
| OCBC Business Credit Card | S$194.40 incl. GST | 3.25% (1% rebate on foreign-currency spend) | 30% Singaporean/PR ownership; turnover ≤ S$20 million | Signatories jointly and severally liable |
| Maybank Business Platinum Mastercard | S$196.20 (2 years waived) | Up to 3.25% | 2+ years; S$200,000 turnover; local director | Per card agreement |
| HSBC Commercial Cards | Programme-based | Per programme | Assessed per programme | Corporate |
| Aspire | S$0 monthly on Basic | None on SGD/USD; from 0.22% otherwise | Singapore-registered business | Company (debit) |
| Airwallex | S$0 on Explore | None from a matching balance; 1% auto-conversion | Singapore-registered business | Company (debit) |
| Wise Business | S$99 one-time setup | Mid-market plus from 0.19% | Wise Business account | Company (debit) |
Sole proprietor / self-employed:
LLP or general partnership:
Private limited company (Pte Ltd):
For board resolutions and specimen signature forms, a corporate secretary can prepare compliant documents that match each bank’s specific format requirements — a step that frequently causes delays when handled ad hoc.
Issuers don’t publish fixed approval times. Fintech accounts are opened online and usually move fastest; bank cards add a credit assessment, and programmes for larger companies go through a relationship manager. Complete, consistent documents are the main thing you control.
The framing of corporate card selection as a “rewards race” misses where the real value sits for most SMEs. HSBC’s Commercial Cards Programme positions its card suite explicitly as an expense-management platform: merchant category controls, virtual card issuance, automated expense reporting, and direct accounting integrations are the headline features, not the points earn rate.
The practical implication: a 0.5% difference in cashback rate between two cards is worth roughly S$500 per year on S$100,000 of spend. A single month of undetected unauthorized spend, or a manual reconciliation process that takes a finance manager four hours per month, costs far more. Virtual cards with per-transaction limits and merchant category locking prevent the first problem; direct accounting integrations solve the second.
Key control and integration features to verify before choosing:
Regulatory status is a two-minute check. Look up the provider in the MAS Financial Institutions Directory for licensed payment institutions, and on MAS’s separate lists for entities operating under a temporary exemption. Fintech wallet balances are not bank deposits.
The most common mistake is optimizing for the rewards brochure rather than the fee schedule and control architecture. A card that earns 1.5% cashback but applies a 2.8% FX markup on overseas spend is a net cost for any business with meaningful cross-border payments. The math is straightforward, yet most SME owners never run it before signing.
The second blind spot is liability. Many founders assume their business credit card carries company liability, but many SME business cards make directors or cardholders liable alongside the company. Read the liability clause before issuing cards to employees. Corporate liability options exist, for example HSBC’s commercial cards and some DBS and UOB business cards.
A corporate-services partner is worth considering specifically at the bank onboarding stage. Foreign-founded companies without an established local banking relationship often face longer review timelines and additional document requests. A partner with existing bank relationships can facilitate introductions, prepare documents in the format each bank expects, and flag eligibility issues before the application is submitted rather than after a rejection.
Selecting the right card is one step. Getting the application approved, especially for foreign-founded or newly incorporated companies, is where the process often stalls. VIVOS provides banking and finance support that covers the full onboarding process: bank introductions, document preparation, board resolution drafting, and compliance paperwork aligned to each issuer’s requirements.
Specific support VIVOS provides:
Foreign founders and international entrepreneurs establishing operations in Singapore can contact VIVOS for a quick eligibility check and bank introduction through the corporate secretarial services page.
Match the card to how your business spends. For foreign-currency spend, multi-currency debit cards usually cost less than bank cards, which charge about 3% to 3.25% on foreign transactions. As of October 2026, Airwallex charges no foreign transaction fee when you spend from a matching currency balance, and Wise converts at the mid-market rate plus a fee from 0.19%. If you need a credit line or rewards, bank business cards from DBS, UOB, OCBC and Maybank offer credit but carry annual fees and stricter eligibility.
There is no single winner, so compare fees, rewards and eligibility. As of October 2026, the DBS World Business Card pays 2% back on foreign-currency spend (S$414.20 fee, S$80,000 minimum income); the OCBC Business Credit Card pays 1% on foreign-currency spend (S$194.40 fee); the UOB Signature/World Business Card pays 0.3% (S$183.36 fee); and the Amex Singapore Airlines Business Credit Card earns points convertible to KrisFlyer miles (S$400 fee). Bank FX fees of about 3% to 3.25% still apply.
Requirements vary by bank. As of October 2026, the DBS Platinum Business Card requires S$30,000 minimum income. The OCBC Business Credit Card needs a Singapore-incorporated business, an OCBC business account, turnover of S$20 million or less and an applicant earning at least S$30,000. Maybank requires two years of operation and S$200,000 turnover. On liability, OCBC makes the company’s authorised signatories jointly and severally liable for charges, while DBS and UOB offer corporate-liability versions of some business cards.
The labels overlap in Singapore, so read the liability clause rather than the product name. Business credit cards target SMEs and often make individuals liable alongside the company: American Express, for example, makes the business and the basic card member jointly and severally liable for all charges. Corporate card programmes usually offer a sole corporate liability option, spend controls and sometimes liability waiver insurance against employee misuse, as HSBC’s and UOB’s corporate cards do.
It depends on the issuer. As of October 2026, the OCBC Business Credit Card requires at least 30% Singaporean or PR ownership, and the Maybank Business Platinum Mastercard requires at least one Singapore citizen or PR director. DBS’s Platinum Business Card page lists age and income criteria but no ownership rule. Multi-currency providers such as Aspire, Airwallex and Wise collect director and shareholder details but state no nationality restriction. Confirm eligibility with the issuer before applying.
Yes. Banks issue debit cards linked to a business current account; the UOB Business World Debit Card, for example, requires a UOB business account and, as of October 2026, has a S$36.67 annual fee waived for three years. Multi-currency debit cards from Airwallex, Wise and Aspire spend from wallet balances instead. Debit cards draw on your own funds rather than a credit line.
Before applying, verify current fees, eligibility thresholds, and T&Cs directly with each issuer. Tariffs and promotional terms change; the figures in this guide reflect published information and should be confirmed at the point of application.
Check the MAS Financial Institutions Directory before onboarding any fintech card provider. Disclosure: DBS, OCBC, Aspire and Airwallex are in VIVOS’s partner network; this comparison uses each issuer’s published terms and treats every issuer the same way.
This article provides general information only and does not constitute financial or legal advice. Confirm current fees, eligibility rules, and regulatory status directly with each issuer and with MAS before applying.

 2 January, 2025
 2 January, 2025

海外收入汇回新加坡何时需纳税?本文解析第10(25)条“汇入”定义、第13(8)条三项免税条件、外国税收抵免、第10L条及文件留存要求。

Employment Pass holders can bring their parents to Singapore on a Long-Term Visit Pass only if they earn a fixed monthly salary of at least…


