


新加坡海外收入汇回:2026年公司与个人的纳税规则与免税条件

Ray Tay
海外收入汇回新加坡何时需纳税?本文解析第10(25)条“汇入”定义、第13(8)条三项免税条件、外国税收抵免、第10L条及文件留存要求。
Published: 22 July 2026 · Last reviewed: 16 October 2026 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
Quick answer: Many venture capital firms invest from Singapore. At early stage, from pre-Series A to Series B, examples include Golden Gate Ventures, Monk’s Hill Ventures, Qualgro and Vertex Ventures Southeast Asia and India. Jungle Ventures and East Ventures invest from seed to growth stage, while Vertex Growth and B Capital run growth funds. Government co-investment flows through Startup SG Equity.
Singapore-based companies raised S$5.9 billion across 472 venture deals in 2025, down 34% in value from 2024, according to EY-Parthenon and Enterprise Singapore (Enterprise Singapore). The firms below are described by what they publish about their own stage, sector and geography.
Leading firms by specialization and market presence:
EDB’s list of GIP-select funds is one objective filter. Managers need at least S$1 billion in assets under management, at least three funds raised and a general partner with 10 years of track record, and Global Investor Programme Option B applicants (individuals applying for Singapore PR) invest S$25 million into these funds. EDB’s August 2026 list names B Capital, East Ventures, Granite Asia, HHLR (Hillhouse), Insignia Ventures Partners, Jungle Ventures and Vertex Venture Management; EDB notes that selection is not an endorsement.
Each firm occupies a distinct niche. The table maps the key dimensions that matter most to founders and investors evaluating their options.
| Firm | Stage | Sectors | Geography | Verified fact |
|---|---|---|---|---|
| Jungle Ventures | Seed to Series C | Consumer, B2B, software | Southeast Asia and India | EDB GIP-select fund manager |
| Golden Gate Ventures | Early stage | Consumer-driven technology, B2B SaaS | Asia and the Middle East | Founded 2011, headquartered in Singapore |
| Monk’s Hill Ventures | Pre-Series A and Series A | Technology | Southeast Asia | Founded 2014 |
| Wavemaker Partners | Early stage; growth fund for Series B and later | Enterprise, deep tech, sustainability | Southeast Asia | Growth fund first close in November 2024 |
| Spiral Ventures | Early stage | AI, blockchain, fintech, greentech and others | India, Japan, Southeast Asia | First check about US$1 million (firm) |
| Tin Men Capital | Series A | B2B technology | Southeast Asia | Singapore-based |
| TRIVE | Pre-seed to Series A | Technology, Web3, AI | Southeast Asia | Founded 2015 |
| Vickers Venture Partners | Early stage | Deep tech | Global | Founded 2005, headquartered in Singapore |
| Qualgro Partners | Series A and B | B2B, data and AI, software | Southeast Asia | Singapore office |
| B Capital | Early to late stage | Technology, healthcare, energy and resilience | Global | EDB GIP-select fund manager; Singapore regional HQ |
| East Ventures | Seed to growth | Sector-agnostic | Southeast Asia and Japan | EDB GIP-select fund manager; founded 2009 |
| Investigate VC | Seed to Series B | Tech platforms, AI and data, fintech, climate, deep tech | Global | Singapore-based |
| Vertex Ventures SEA and India | Seed to Series B | Sector-agnostic | Southeast Asia and India | Fund V of US$541 million (2023) |
Stage, sector and geography are as each firm describes itself on its own website, checked on 16 October 2026. VIVOS is not a venture capital firm and is not part of this comparison.
Jungle Ventures backs founders from seed through Series C, with initial checks of US$500,000 to US$20 million according to the firm. Monk’s Hill Ventures invests at pre-Series A and Series A. Beyond capital, the most useful firms bring networks, introductions and operating experience.
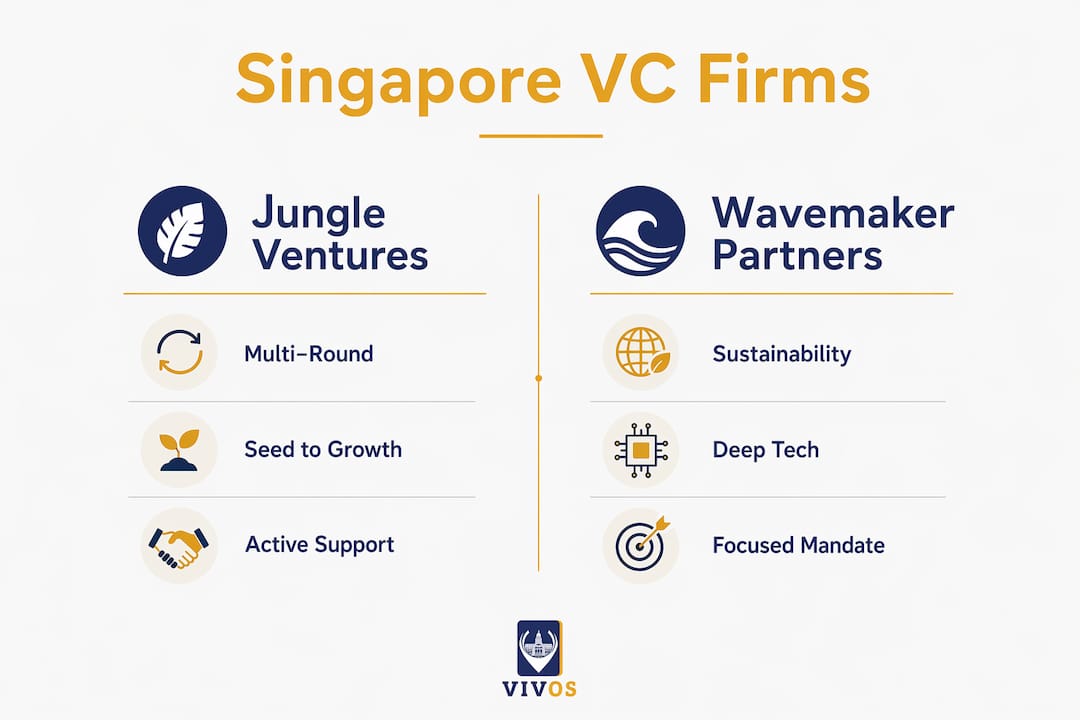
Wavemaker Partners invests in enterprise, deep tech and sustainability, and added a growth fund for Series B and later rounds in 2024. Spiral Ventures invests across India, Japan and Southeast Asia, with a first check of about US$1 million.
VIVOS is not a venture capital firm. For founders who need corporate infrastructure alongside fundraising, VIVOS covers incorporation, compliance, fundraising preparation and banking support across Singapore, Malaysia, Hong Kong and the UAE.
Generally yes. Fund management is a regulated activity under the Securities and Futures Act, and MAS has offered a simplified regime for venture capital fund managers (VCFMs) since 20 October 2017. Under it, each fund the manager runs must:
VCFMs have no minimum base capital under MAS’s VCFM compliance toolkit, but MAS’s other licensing and anti-money laundering requirements still apply. Founders can check any manager’s status in the MAS Financial Institutions Directory before signing a term sheet.
Selecting the right VC partner depends on more than fund size. Stage alignment, sector expertise, and the quality of post-investment support all determine whether a partnership creates value or friction.
Key selection criteria:
Questions to ask during due diligence:
Pro Tip: Request a reference call with a founder the VC backed through a difficult period, not just a success story. How a firm behaves when a portfolio company struggles reveals far more than its pitch deck.
Alignment of interests between investor goals and startup vision is the single most important factor in avoiding conflicts during volatile phases.
Securing VC funding is one milestone. Building the corporate infrastructure to receive, deploy, and account for that capital is a separate discipline entirely.
Core services startups and investors need:
Corporate governance and board engagement are critical to protecting investment value. Weak controls reduce company valuation at exit, regardless of product quality. This is not a compliance checkbox; it is a commercial priority.
VIVOS provides fundraising preparation advisory that covers investor-ready documentation, due diligence support, and corporate records management. For international founders, VIVOS also handles company incorporation and banking setup, removing the administrative friction that delays funding rounds.
Singapore VC firms operate across a broad spectrum of stages, from pre-seed to late growth. VC firms manage pooled capital from institutional investors and deploy it in exchange for equity, not as fee-for-service lenders.
Published data is a better guide than rules of thumb. In the first half of 2026, median Southeast Asian deal sizes were about US$0.9 million at pre-seed, US$3.7 million at seed and US$8 million at Series A, according to Kickstart Ventures and DealStreetAsia (TNGlobal). Singapore’s median deal value across all stages was US$4.5 million in 2025, per EY-Parthenon and Enterprise Singapore. Firm-stated ranges:
Minimum viable traction expectations vary by stage. Seed-stage investors typically want a working product and early user data. Series A investors expect demonstrated revenue growth and a clear path to unit economics.
The funding process from first contact to capital in the bank typically spans three to six months, though complex rounds or cross-border structures can extend that timeline.
Typical process stages:
Founders who arrive with organized corporate records and clean compliance histories close faster. Gaps in statutory filings or unresolved cap table issues are the most common causes of deal delays in Singapore.
Singapore’s VC activity concentrates in sectors where the city-state holds structural advantages: regulatory clarity, talent density, and proximity to high-growth Southeast Asian markets.
Top sectors by VC activity:
Government co-investment runs mainly through Startup SG Equity, run by Enterprise Singapore and EDB, which co-invests alongside independent third-party investors. Budget 2026 added S$1 billion for early- and growth-stage deep tech, including direct growth-stage investments by SG Growth Capital, formed in April 2025 from EDBI and SEEDS Capital. GIP-select funds must also invest at least half of the GIP money they receive (or S$50 million if lower) in Singapore-based companies in EDB-promoted sectors.
Before taking corporate money, ask what the parent expects in return, such as commercial pilots, information rights or a right of first refusal.
Most founders approaching Singapore’s VC ecosystem focus entirely on the pitch. The corporate infrastructure behind the pitch, including the company structure, compliance records, banking relationships, and tax position, often gets addressed too late.
VIVOS handles the full corporate setup for international entrepreneurs and startups preparing for VC investment in Singapore. Services cover company incorporation, corporate secretarial, banking support, accounting, tax filing, and fundraising advisory, all under one provider. For founders who need to move fast without building an internal admin team, VIVOS provides the governance foundation that investors expect to see before they write a check.
Singapore’s VC ecosystem rewards founders who combine the right firm selection with clean corporate infrastructure from day one.
| Point | Details |
|---|---|
| Stage alignment matters most | Match your funding stage to the firm’s mandate before any outreach; misaligned pitches waste months. |
| Governance drives valuation | Weak corporate controls reduce exit price regardless of product quality; build compliance early. |
| AI leads the money | AI drew about 30% of Singapore’s 2025 venture funding: over S$1.8 billion of S$5.9 billion. |
| Funding timelines run 3–6 months | Clean cap tables and organized statutory records are the fastest way to shorten due diligence. |
| VIVOS covers the corporate layer | VIVOS is not a VC; it provides incorporation, compliance, banking and fundraising preparation for founders entering Singapore’s VC market. |
Singapore-based venture funds cover every stage. Golden Gate Ventures, Monk’s Hill Ventures and Qualgro invest at early stage, from pre-Series A to Series B. Jungle Ventures and East Ventures invest from seed to growth, and Vertex Growth and B Capital run growth-stage funds. In 2025, Singapore-based companies raised S$5.9 billion across 472 venture deals, according to EY-Parthenon and Enterprise Singapore.
One objective filter is EDB’s list of GIP-select funds. To qualify, a manager needs at least S$1 billion in assets under management, at least three funds raised and a general partner with 10 years of investment track record. EDB’s August 2026 list names B Capital, East Ventures, Granite Asia, HHLR (Hillhouse), Insignia Ventures Partners, Jungle Ventures and Vertex Venture Management. EDB notes that selection is not an endorsement.
Examples include Singtel Innov8, which launched a US$250 million AI Growth Fund in 2026; UOB Venture Management, a wholly owned UOB subsidiary that has financed private companies since 1992; Standard Chartered’s SC Ventures; ST Engineering Ventures; and Saison Capital, the venture arm of Credit Saison. Before signing, ask what the parent expects in return, such as commercial pilots, information rights or a right of first refusal.
East Ventures, founded in 2009, describes itself as sector-agnostic and invests from seed to growth across Southeast Asia. Vertex Ventures Southeast Asia and India calls itself a sector-agnostic VC and invests at seed, Series A and Series B. BEENEXT describes itself as industry-agnostic. Sector-agnostic does not mean thesis-free: in February 2026, East Ventures said it would focus on AI-first, healthtech, consumer tech and climate tech.
Vertex Growth, founded in 2019, reports US$760 million under management. B Capital has a Singapore regional headquarters and runs growth-to-late-stage funds. Wavemaker Partners’ growth fund targets Series B and later rounds. SG Growth Capital, formed in April 2025 from EDBI and SEEDS Capital, invests directly in growth-stage deep tech startups under the expanded Startup SG Equity scheme. Jungle Ventures invests up to Series C.
Generally yes. Fund management is a regulated activity under the Securities and Futures Act. Since 20 October 2017, MAS has offered a simplified venture capital fund manager (VCFM) route. Each fund must invest at least 80% of committed capital in unlisted businesses incorporated no more than 10 years before the first investment, be closed to new subscriptions after fundraising, be redeemable only at the end of its life, and be offered only to accredited or institutional investors. VCFMs have no minimum base capital.
Official and primary pages used for this guide, checked on 16 October 2026. Firm details come from each firm’s own website, linked above.
This article is general information, not investment, legal or financial advice.

 2 January, 2025
 2 January, 2025

海外收入汇回新加坡何时需纳税?本文解析第10(25)条“汇入”定义、第13(8)条三项免税条件、外国税收抵免、第10L条及文件留存要求。

Employment Pass holders can bring their parents to Singapore on a Long-Term Visit Pass only if they earn a fixed monthly salary of at least…


