


Three quarters in, domestic disquiet could prove costly for S-E Asia’s growth drivers
Front-loading begins to cool, while political turnovers and corruption scandals rattle confidence
[SINGAPORE] While a front-loading rush in the first half of the year saw South-east Asia’s growth rates hold steady in the face of US tariffs, the region’s mixed third quarter has offered hints at what could come in 2026.
Analysts noted that the region’s resilience has been noteworthy, with a number of South-east Asian countries beating market consensus estimates for gross domestic product growth in the third quarter of the year – Singapore, Indonesia, Malaysia and Vietnam.
Strong front-loading shipment activity had taken place ahead of US tariffs coming into effect in August, driving growth within the region in the first half of the year.
“Electronics exports have proven particularly resilient, on the back of artificial intelligence-related capital expenditure demand,” noted Ang Kai Wei, Asean economist at the Bank of America.
But analysts believe that this growth support could begin to cool, while US trade policy begins to take a toll.
“The staggered implementation of tariffs has allowed businesses to cope through front-loading global shipments before gradually easing into slower activity in the later half of the year,” said Cameron Systermans, head of multi-assets at Mercer Asia.
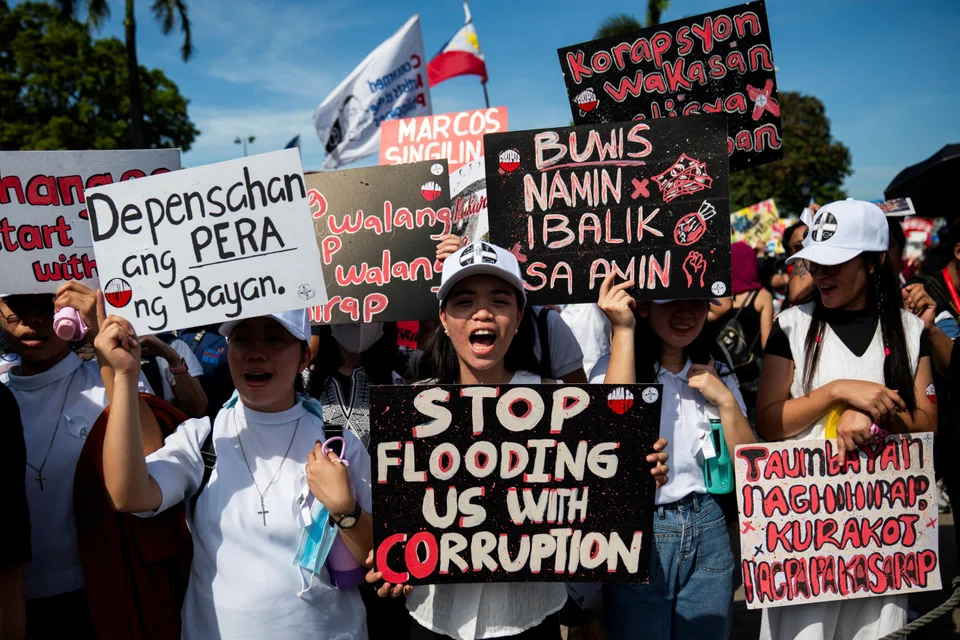
Simultaneously, domestic troubles have been costly, as political turmoil in Thailand, Indonesia and the Philippines has made visible marks on Q3 growth rates.
Two of these countries – the Philippines and Thailand – underperformed against market estimates in the quarter.
What’s next for Asean’s economies?
The continued impact of US tariffs is likely to worsen in the coming quarters, believes Jamus Lim, associate professor of economics at Essec Business School.
“It would not surprise me if Asean economies face a tougher time ahead,” said Prof Lim. “The region has been slapped with baseline tariffs, after negotiations, that are close to 20 per cent, which is around three times higher than pre-Liberation Day.”
Broad-based resilience across the region could continue to slow in the second half of the year as front-loading shipments ease, noted Systermans of Mercer.
Deepali Bhargava, chief economist for Asia-Pacific at ING, said that further diversification of export destinations would likely remain a significant priority for the region’s governments and businesses.
Prof Lim echoed the idea: “In terms of addressing the external environment, Asean will need to rediscover its regional linkages and emphasise intra-bloc economic solidarity.”
“This will be far more effective than its current reliance on bilateral negotiations with the Trump administration, since each country is unlikely to have sufficient economic leverage,” he noted.
Meanwhile, low inflation prints across the region are likely to maintain policy space for the region’s central banks to ease rates, should economic activity slow, said Mercer’s Systermans.
“Additionally, central banks are increasingly proactive in addressing currency volatility, recognising that excessive depreciation can undermine market confidence,” said Chong Wee Khoon, Asia-Pacific macro strategist at BNY. (*see amendment note)
Here’s how Asean’s top six economies performed in the third quarter – and what’s next for them.
Vietnam – Asean’s fastest grower
Grade: A
With the strongest growth rate in South-east Asia, Vietnam’s 8.23 per cent GDP growth year on year saw the country continue its forward momentum from the second quarter, as hopes rise about a trade deal agreement with the US.
Robust consumption, investment and export activities drove the country to one of its fastest third-quarter expansions since 2011, but rising inflation and a weak dong against the greenback could impact confidence.
“We expect the demand for computer and electronics to remain strong for the rest of 2025 as the tech upcycle still has some more room to run,” said ANZ’s economists Khoon Goh and Kausani Basak in an Oct 30 report, noting that these are among products exempted from the existing 20 per cent tariff that the US has imposed on Vietnamese imports.
“This will continue to drive the overall export growth in 2025,” they said, while raising the bank’s 2026 growth forecast to 6.8 per cent.
Malaysia – Cautiously resilient
Grade: B
Malaysia’s 5.2 per cent GDP growth in the third quarter of 2025 raced forward as the country beat a Bloomberg consensus forecast of 4.2 per cent.
This comes after analysts had expected that the country’s second-half growth would slow, following a strong showing in the previous two halves – as the impact of US tariffs would begin to show.
But stronger net exports and sustained domestic demand has kept the country on track to achieve growth of 4 to 4.8 per cent for the full year, Malaysia’s central bank governor Abdul Rasheed Ghaffour had noted in a media briefing on Nov 14.
“Malaysia’s focus on developing data centres and revitalising economic sentiment through joint economic zones has effectively bolstered global investor confidence and attracted significant foreign investment,” said BNY’s Chong.
However, the country’s semiconductor sector continues to await US tariff policy decisions targeting the industry – which could weigh on business sentiment and growth, noted Mercer’s Systermans.
Singapore – Surprising momentum
Grade: B
A stronger-than-expected showing in the year’s Q3 results saw the Republic beat estimates, recording a 2.9 per cent year-on-year print compared to the median forecast of 2 per cent that economists polled by Bloomberg had projected.
This reinforces the city-state’s above-trend momentum of 3.9 per cent growth over the first to third quarters, pointed out Bhargava of ING.
“Singapore continues to demonstrate robust growth, underpinned by strong advances in financial services, digital innovation, and a booming real estate market,” noted BNY’s Chong.
This stronger-than-expected performance has prompted some economists to revise their full-year growth projections upwards – DBS, for instance, has raised full-year growth forecasts to 3.5 per cent from 2 per cent previously.
While the country’s pharmaceuticals sector remains at risk of heavy tariffs, the initial feared impact of these tariffs have eased significantly, Bhargava said.
This is because much of Singapore’s pharmaceutical exports consist of generic drugs not targeted by the proposed US tariffs on branded products, she added.
Indonesia – Fiscal worries
Grade: C
While beating expectations with a 5.04 per cent year-on-year growth rate in the third quarter, Indonesia’s economic performance cooled slightly from the previous quarter’s 5.12 per cent growth rate.
“While avoiding a slowdown is to be admired, it’s far short of President Prabowo Subianto’s goal of reaching 8 per cent by the end of his term,” said Tamara Henderson, senior economist at Bloomberg Economics in a report on Nov 6.
Analysts remain cautious about the country’s fragile place among external trade dynamics as momentum slows amid domestic political uncertainty, after protests erupted due to discontent over Prabowo’s ambitious fiscal plans.
“We expect a further slowdown in the coming quarters, weighed down by weaker sentiment as US tariffs bite harder and investor worries about less prudent fiscal policy,” Henderson said.
A 24.44 trillion rupiah (S$1.9 billion) stimulus package is under way, as Prabowo’s administration seeks to jump-start domestic growth, which is expected to fuel the country’s growth momentum into Q4.
“However, effects (of the stimulus measures) may take some time before showing up,” noted Bank of America’s Ang.
The Philippines – Sink or swim
Grade: D
One of the two South-east Asian economies to miss consensus estimates in Q3, the Philippine economy faces an uphill battle as a corruption scandal weighs on confidence.
Allegations that public infrastructure projects, particularly flawed flood-control facilities, had been used to divert billions of dollars to lawmakers and contractors have rattled investors and delayed public expenditure.
“The short-run hit to growth from the ongoing graft scandal is significant, given earlier signs of a sharp drop in fiscal spending,” said Nomura’s Asean economists Euben Paracuelles and Chen Yiru in a Nov 10 report.
The country’s momentum slowed considerably, recording a 4 per cent growth in the quarter, year on year. This print was more than a percentage point below estimates of 5.2 per cent and down from 5.5 per cent growth in the second quarter.
“Soft government spending could become a longer-term drag, weighing not only on fiscal outlays but also on business and private sector sentiment,” said ING’s Bhargava.
Thailand – domestic setbacks continue
Grade: D
Shaken by a political turnover and border conflicts with Cambodia, Thailand and its new prime minister Anutin Charnvirakul face a weighty challenge in lifting its economy, after recording its slowest third quarter growth in four years.
Recording a 1.2 per cent growth in GDP from a year earlier, Thailand’s economy missed consensus estimates of 1.6 per cent, while slowing from the 2.8 per cent recorded in the second quarter.
ANZ’s Asia economist Krystal Tan noted in a Nov 17 report that the Thai economy had been dragged down by weak government spending and services exports. “The Thai economy continues to grapple with structural constraints that will hinder growth, particularly Thailand’s persistently high household debt,” added Tan.
Domestic struggles and a protracted election cycle have weighed on the country’s investment and household sentiment, noted ING’s Bhargava, while its critical tourism sector has faced year-round struggles.
“Thailand’s tourism-reliant economy has been hit hard by weak visitor numbers, which could also be related to these governance challenges,” said Prof Lim of Essec Business School.
While a 44 billion baht (S$1.7 billion) consumer subsidy programme aims to lift economic growth above 2.2 per cent this year, Anutin’s government faces a race against time as he plans to dissolve parliament by the end of January for a general election to be held in March or early April.
Amendment note: An earlier version of this article incorrectly stated Chong Khoon Wee’s last name as “Wee” instead of “Chong”. The article has been revised to reflect his correct name.






