

Keppel DC Reit’s Tokyo drift: The easy yen trade is over
There is a risk trailing every data centre valuation today: the threat of quickly becoming outdated
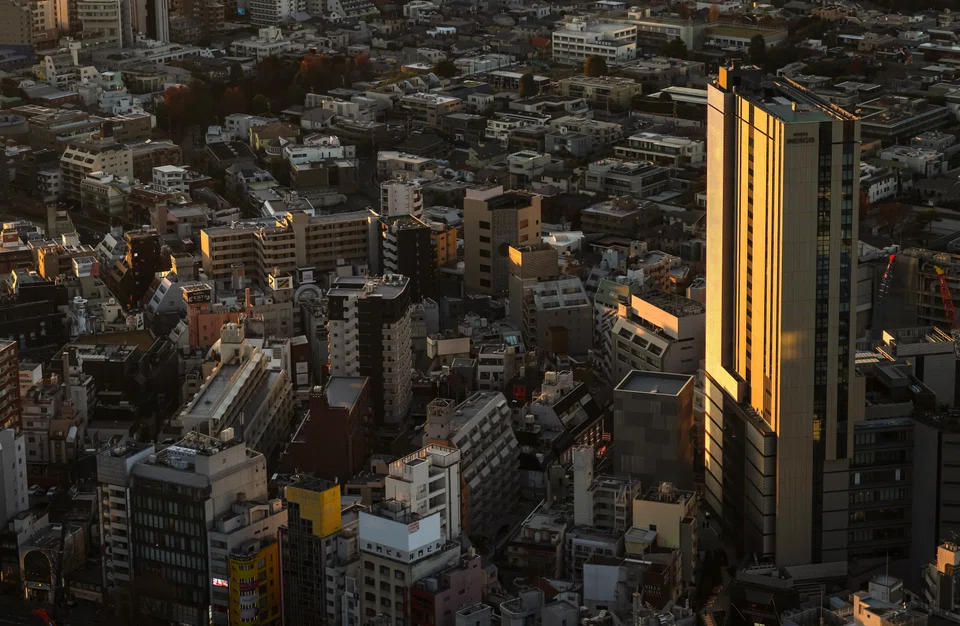
[SINGAPORE] Keppel DC Real Estate Investment Trust’s (Reit) S$1.4 billion purchase of two Tokyo data centres hits all the right corporate notes: an 88.6 per cent stake in two freehold assets at a 2.1 per cent discount to valuation, immediate accretion to distribution and net asset value, and an upsized S$625 million placement to help pay for it.
All of which reads well. But the real story is buried in the debt.
According to Maybank analyst Krishna Guha, the yen debt funding this purchase carries an interest rate of about 2.9 per cent. That is not a massive number, but it is a painful reminder of what is gone.
For years, a Singapore-listed Reit – or S-Reit – buying Japanese property was essentially running a funding trade. Borrow yen at near-zero rates, buy an asset yielding a few points higher, and book the spread.
But the Bank of Japan has taken away that free lunch.
At 2.9 per cent, Keppel DC Reit’s interest rate for the latest acquisition costs more than the 2.7 per cent average cost of debt for its portfolio on a pro forma basis.
The accretion here is no longer manufactured by cheap money; the buildings actually have to earn their keep. Fortunately, they might.
The two data centres in Inzai City are fully occupied by investment-grade clients, carry 2.8 per cent annual rent escalations, and sit on in-place rents roughly 30 per cent below market rates.
Inzai is on a tight market; supply is scarce. Analysts naturally love this set-up.
Morningstar’s Xavier Lee and Maybank’s Guha both bumped up their targets, citing the rental reversion upside.
But there is a catch – time. The weighted average lease expiry is 4.5 years at one asset, and a hefty 10.6 years at the other.
Guha expects positive reversion to kick in only from 2029. This means that buyers today are paying for a 2029 story, hoping the rental escalators tide them over.
This makes the deal less of a yield play and more of a structural fix.
The real win for Keppel DC Reit – whose results briefings have often kicked off with questions about tenant concentration – could be diversification.
Three of the four Tokyo clients are new to the portfolio. The top client’s income share falls from 43.5 per cent to 38.2 per cent. And Japan’s contribution jumps to 23 per cent from 9 per cent, leaving Singapore as the 60 per cent anchor.
But none of this structural improvement comes free.
Pro forma leverage creeps up four percentage points to 38 per cent. Existing unitholders pay for their share of the accretion via dilution, given the placement was priced at a 4.4 per cent discount to the volume-weighted average price.
Guha also noted that the joint venture set-up “may be introducing some mark ups”. Even so, the market lapped it up.
The equity raise was 3.4 times covered at the upsized amount, mostly by long-only institutions. In a sector where many S-Reits cannot raise a single cent without sharp discounts, Keppel DC Reit walked away with more than it asked for.
Yet, units of Keppel DC Reit – which Lee describes as undervalued – dipped S$0.01 or 0.5 per cent to close at S$2.19 on Wednesday (Sep 2).
Perhaps they are undervalued. But there is a risk trailing every data centre valuation today: the threat of quickly becoming outdated.
The prevailing AI narrative demands liquid cooling and massive rack densities that simply did not exist when older colocation assets were built. Upgrading them requires serious capital.
That is the tension in buying colocation assets during an AI boom. The Tokyo assets are fully fitted, entirely leased and cash-generating. That makes them financeable, but it also means they are not the frontier of AI infrastructure.
The placement order book proves that investors are eager to fund the AI theme. But on these numbers, they are not buying a cutting-edge AI play. They are buying a reliable Japanese landlord with a rent review due in 2029.
That is a perfectly fine thing to own, provided you know exactly what you are buying.
TRENDING NOW
LTA proposes combining car COE categories, adding rebate-surcharge system
StarHub to acquire MyRepublic’s mobile business amid ongoing telco consolidation

DBS, OCBC, UOB rout lops billions off STI as inflation, rate concerns spook investors

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

