

Malls and offices stay full but investors shun S-REITs over rate fears: DBS
S-REITs yield 6.2% yet trade below book value as Fed concerns dominate.
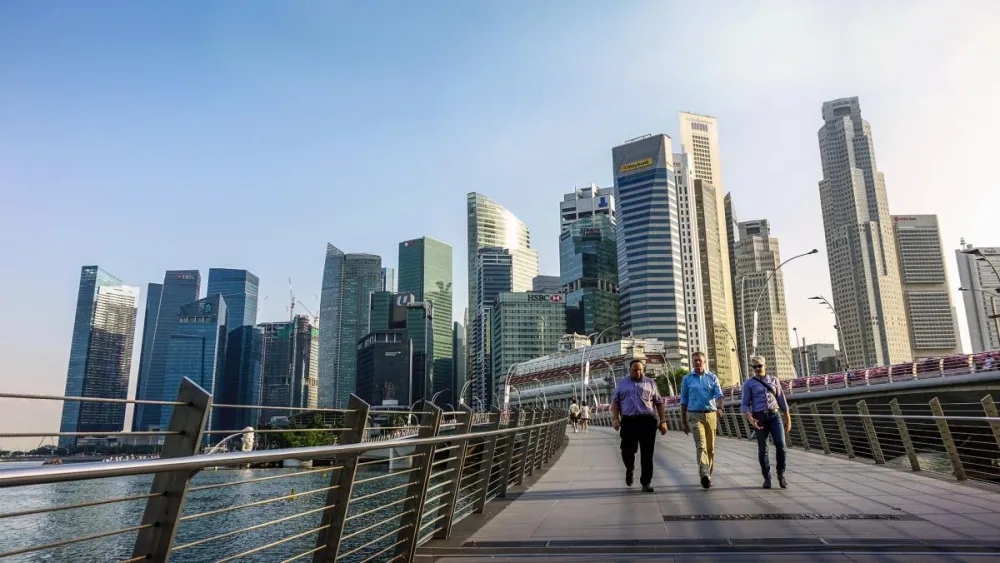
Singapore real estate investment trusts (S-REITs) remain resilient despite cautious investor sentiment, with market concerns centred more on interest rates than underlying real estate fundamentals, DBS said.
Recent visits to office, retail, and industrial properties showed healthy leasing demand, stable occupancy trends and continued operational strength.
Prime retail destinations including VivoCity, ION Orchard and Paragon Shopping Centre continue to record resilient shopper traffic and tenant engagement, whiles industrial properties continue to benefit from healthy leasing activity.
“The disconnect between listed valuations and physical real estate continues to be driven primarily by interest rate concerns rather than asset-level weakness,” DBS said.
Whilst investors broadly acknowledge that S-REIT valuations remain compelling—trading at approximately 0.9x price-to-book value with FY26F yields of around 6.2% and a yield spread of about 4.2 percentage points over the 10-year Singapore government bond—market discussions continue to be dominated by macroeconomic concerns.
The primary focus amongst investors has been the outlook for interest rates following the Federal Reserve’s hawkish June commentary, with concerns centred on whether rates could remain elevated for longer.
Key questions include the sustainability of distributions amid higher funding costs, as well as the potential impact of prolonged higher rates on property valuations and balance sheet strength.
Sectors such as purpose-built worker accommodation, co-living and flexible workspaces continue to attract interest, supported by structural growth drivers including urbanisation, housing affordability challenges and changing workplace preferences, the report noted.
Market participants also noted continued momentum amongst property disruptors, with co-living operator Coliwoo and flexible workspace provider JustCo reporting strong demand for their offerings.
An earlier assessment by UOB Kay Hian in June also pointed to resilience in the sector, maintaining an overweight view on S-REITs on the back of stable cash flows, attractive yields, lower domestic interest rates, and limited new supply across retail, office, and data centre segments.
The brokerage noted that 11 of the 17 large-cap S-REITs under its coverage met expectations in 1Q26, with Frasers Centrepoint Trust, Frasers Logistics & Commercial Trust, Keppel DC REIT, and Suntec REIT exceeding expectations.


























 Read Here
 Advertise
 Sign Up









