MAS chief economist links monetary easing to AI productivity gains
AI investment could raise asset valuations and financial stability risks.
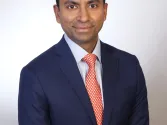
Monetary policy may become more accommodative as artificial intelligence (AI) productivity gains take hold, but should remain appropriately restrictive during the investment-led demand boom, said Monetary Authority of Singapore (MAS) Deputy Managing Director for Economic Policy and Chief Economist Edward Robinson.
"Monetary policy should be appropriately restrictive in the initial stages of the boom, whilst demand effects dominate," he said at the 2026 Beijing Financial Street Forum on 20 October. "It may then turn more accommodative as productivity gains demonstrably take hold, and the “stars” shift."
The AI boom is helping sustain global demand and offset trade tensions and higher energy costs in several Asian economies. AI-driven electronics account for more than 70% of Asia’s export growth in 2026, whilst the region, including China, is advancing in AI technologies, from advanced chips to large language models.
However, growth in AI-producing industries has so far largely reflected capital accumulation and greater use of equipment, rather than broad-based improvements in total factor productivity, said Robinson.
New data centres are being built and advanced equipment is being used more intensively, raising output without necessarily delivering sustained efficiency gains.
“On the AI-using side, AI is diffusing across the wider economy faster than the personal computer and the internet did,” said Robinson. “While early evidence points to efficiency gains in specific applications, it remains too soon to identify a decisive economy-wide step-up in productivity”
He said that broader gains will depend on widespread adoption, investment in skills and infrastructure, and organisational redesign.
With sufficiently broad adoption and appropriate investment, AI could raise annual total factor productivity growth by up to 0.6 percentage points, according to Organisation for Economic Co-operation and Development estimates.
“This could meaningfully offset the negative effects from demographic ageing and other structural headwinds in Asia,” Robinson said.
AI adoption in domestic services could also narrow productivity gaps between tradable and non-tradable sectors. By enabling more workers to perform higher-value tasks previously reserved for specialists, AI could lower the cost of healthcare, education, and legal advice and spread productivity gains more widely.
Robinson said central banks must balance AI's potential as a favourable long-term supply shock against its immediate impact on demand. “Investment in data centres and energy networks is surging, while higher asset valuations are raising demand through wealth effects, even as the productivity dividend remains unclear.”
Expectations of substantial future productivity gains could become embedded in asset valuations. If investors become overly optimistic, leverage could rise and valuations could overshoot. A subsequent reassessment could trigger reversals in asset prices, credit conditions and investment.
Policymakers should not assume AI has already shifted the benchmarks guiding monetary policy: potential output, the natural unemployment rate and the neutral interest rate.
Singapore must also consider its neutral exchange rate path, said Robinson. Strong economic activity may still reflect cyclical demand rather than a lasting increase in productive capacity.
Sustained productivity growth could eventually raise potential output and the natural interest rate through higher expected investment returns. However, unevenly distributed AI gains could cause labour displacement and income uncertainty, encouraging precautionary saving and putting downward pressure on the natural interest rate. The net effect remains uncertain.
Monetary policy may become more accommodative when productivity gains demonstrably take hold and the underlying policy benchmarks shift. Robinson called for gradual, data-dependent adjustments to reduce the risk of policy miscalibration.
Macroprudential measures should guard against excessive leverage based on uncertain future AI revenues. Budgetary, regulatory and structural policies should support adoption through digital infrastructure, skills training and applications that complement workers, whilst anticipating risks and establishing safeguards to maintain trust in AI.
Robinson said AI's long-term promise extends beyond higher productivity to broadening human creativity by enabling more people to innovate, create and exercise judgment in their daily work.
However, he cautioned that history contains repeated episodes in which expectations ran ahead of productivity and valuations ran ahead of fundamentals. .”We cannot assume that this time is different.”
Robinson said the challenge is to manage the transition as the demand and supply effects of AI converge. “Sound macro-policy cannot eliminate uncertainty but can promote price and financial stability as the necessary conditions for the long-run promise of AI.”






















 Read Here
 Advertise
 Sign Up