Why easing property curbs won't stop prices from crashing
Vacancy ratios, slower pace of immigration, and weak labour market to weigh on prices.
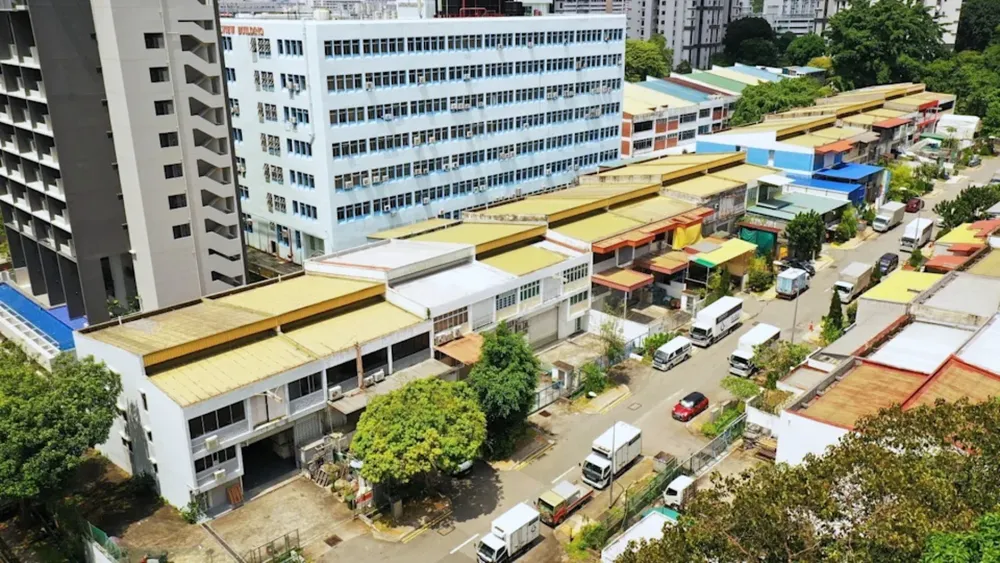
House prices are likely to continue falling amidst oversupply and increasing interest rates, stated Fitch Ratings.
According to Fitch, Singapore's efforts to curb property speculation in an environment of low global interest rates have been effective. Speculative purchases have declined as, from 2009, restrictions on mortgage lending were made progressively tighter and stamp duties were raised.
"House prices have now fallen in each of the last three years and housing loan growth has slowed steadily since 2011. The impact contrasts with Hong Kong, where macro-prudential tightening began around the same as in Singapore, but prices have continued to rise and mortgage growth has shown no clear downward trend," noted Fitch.
Singapore's regulators should have room to lean against price declines by reversing macro-prudential tightening, if needed. Fitch said the modest move in that direction was made with the lowering of sellers' stamp duty and holding period during which it applies.
"We expect further gradual loosening over the coming years, as the authorities balance supporting the market with guarding against risks. Regulators in Hong Kong, Australia, and New Zealand are still some way off loosening property market restrictions," it explained.
Fitch furthered, "The latest changes are unlikely to have a significant impact on Singapore's housing market. Macro-prudential settings are still tight, whilst high vacancy ratios, a slower pace of immigration, subdued economic conditions, and a weakening labour market are all likely to continue weighing on prices. Local interest rates are also set to rise from their current low levels, as the US Federal Reserve tightens policy. House prices are still likely to fall by another 2%-5% over the next two years."
Should property prices drop sharply, Singapore banks are expected to be well-positioned to withstand it as a result of macro-prudential tightening.
"Average loan-to-value ratios are low, loan-loss coverage is adequate, and capital and liquidity buffers are strong. Households also have healthy balance sheets and well-diversified assets," said Fitch.






















 Read Here
 Advertise
 Sign Up