Lian Beng long-term prospects remain solid: Maybank
Look past its flailing short-term revenues to find a healthy construction orderbook.
Recurring income is also growing, which according to Maybank Kim Eng, as proceeds from its industrial and residiental projects begin to "contribute substantially" to future earnings.
Here's more from Maybank Kim Eng:
Revenue down on lack of one-off gain. Lian Beng reported a 16.5% YoY drop in revenue to SGD113.4m for 1QFY5/13. Stripping out the SGD7.9m one-off gain from the sale of an investment property in 1QFY5/12, bottomline contracted by 7.4% YoY to SGD10.6m. The lower-than-expected results could also be attributed to lower sales recognition from the property development division.
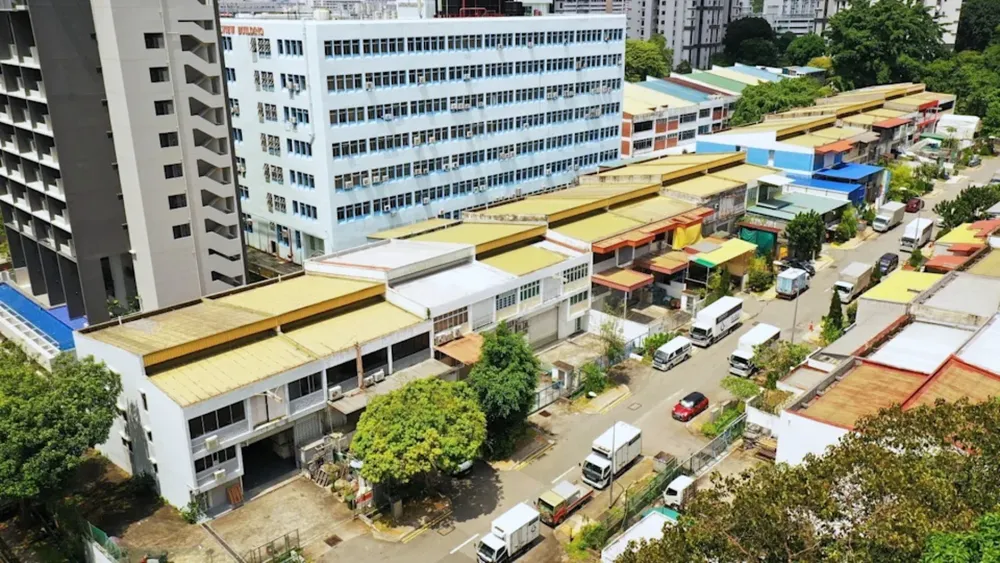
Margins shrank on lower property sales recognition. Lian Beng’s gross and net margins fell by, respectively, 1.1ppt YoY and 4.9ppt YoY, following lower sales recognition of property development projects. The proceeds from its industrial project, M-Space, are expected to be fully recognised in 1HFY5/14F. Separately, Spottiswoode Suites, previously Dragon Mansion, is slated for launch by year-end. Based on estimated breakeven price of SGD1,575 psf, we expect the project’s ASP to be SGD2,000 psf. The 50%-owned Hougang Plaza will also be ready by year-end. We believe these two projects will contribute substantially to FY5/14F earnings.
In net debt position. From net cash position, Lian Beng’s total borrowing has risen by SGD96.6m QoQ to SGD197.2m on the back of higher financing costs for the development of Spottiswoode Suites and Hougang Plaza, as well as increased working capital for its other residential stakes and reclassification of the development cost for its remaining vacant plot in Mandai Estate.
But strong cash-churning machines will provide support. Lian Beng’s construction business and recurring income from precast concrete products are expected to help shore up the group’s dividend payout of SG2cts for FY5/12, which translates to a yield of 5.1%. Its construction orderbook currently stands at SGD650m.






















 Read Here
 Advertise
 Sign Up