Big 3 banks’ stock prices drop up to 10% on bond yield concerns
There is a growing sense that the sector may be overvalued, a Julius Baer analyst said.
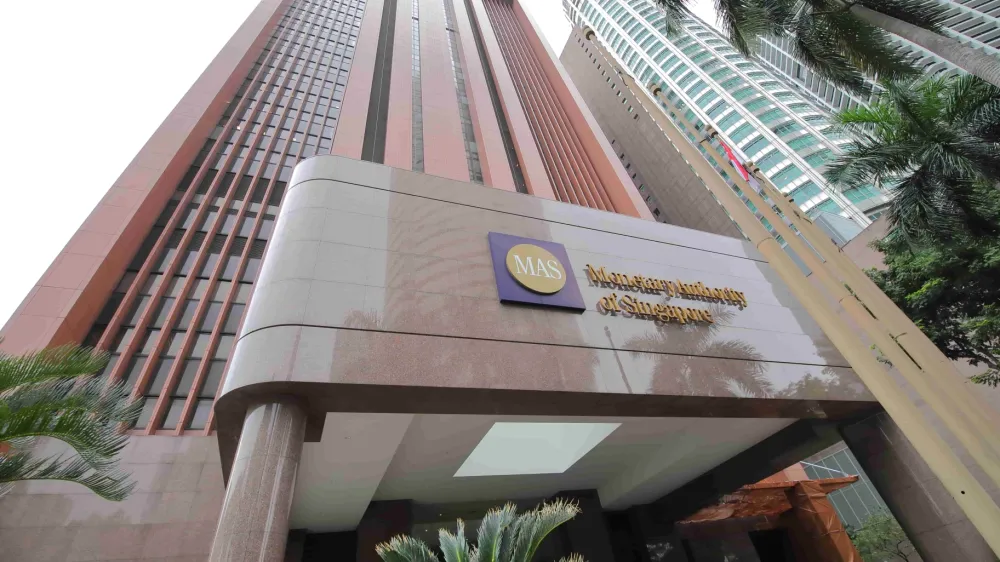
Investor aversion for Singapore bank stocks has “increased materially”, with prices correcting 6% to 10% in the first week of October 2026, according to Julius Baer.
OCBC led, falling 9.9%, followed by UOB declining 7.9% and DBS with a 6% decrease. This correction was sparked by a broker downgrade and sell-side concerns regarding the risks of higher long bond yields for bank earnings, Julius Baer said in an analysis published on 9 October 2026.
“There is a growing sense that the sector may be overvalued following its strong and rapid rally over the past two years,” said Jen-Ai Chua, equity research analyst for Asia at Julius Baer.
Fundamentals for the three banks have not materially changed, Chua said.
“Critically, there are still no overtly concerning signs of bad debt, which tend to characterise bear markets for the banks, while loan growth is relatively healthy,” Chua said.
Chua advised investors to wait for the release of Q3 2026 results and management commentary.
“Concrete data and more colour on outlook should provide much needed certainty on whether their earnings quality and wealth businesses continue to justify the premium ascribed to valuations,” Chua said.
Singapore banks are not the only ones to “take a beating,” said Chua. Japanese megabanks are down 2.2% to 3.4% on 8 October, whilst large Hong Kong banks fell between 4.8% to 5.2% during the same day, she noted.
Chua said that higher bond yields are likely making their effects felt on equity markets, with banks amongst the more sensitive to such shifts.
“Whether the market has overshot in terms of their expectations of Fed rate hikes or is correct in expecting a structural upward shift in interest rates will determine if the current weakness represents just a knee jerk to higher bond yields or a more permanent resetting of expectations,” Chua said.
Chua said to expect more price volatility.





















 Read Here
 Advertise
 Sign Up