

All systems go: FCT clears CCP acquisition hurdles
It’s time to jump into the investment bandwagon.
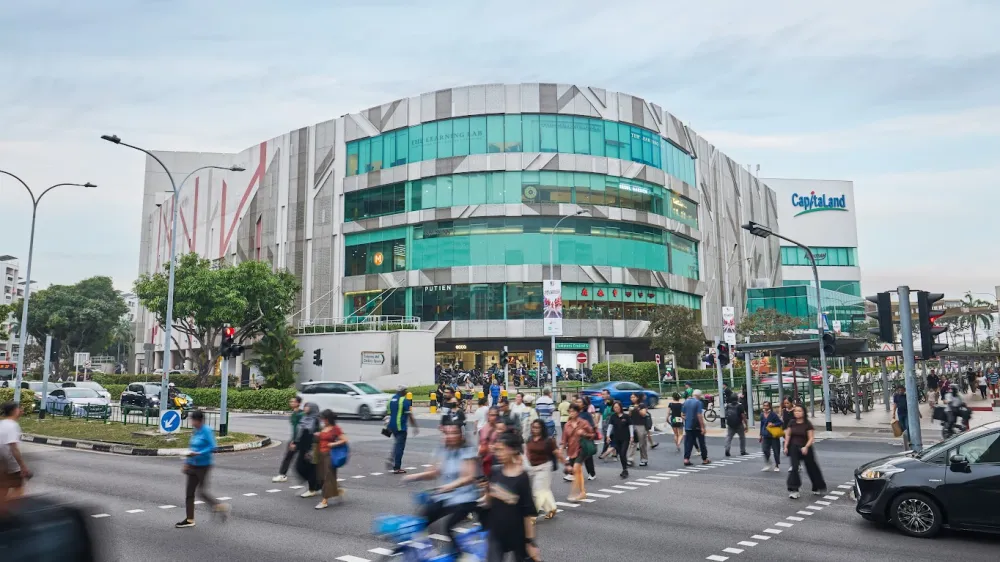
The excited hubbub is dying away after Frasers Centerpoint Trust’s successful acquisition of Changi City Point last week. According to DBS, now is the time for potential investors to splurge on the company.
DBS noted that CCP is poised to propel FCT’s earnings in the years ahead, and the company’s offers are at highly attractive at present.
“At current levels, FCT offers an attractive FY14-16F yield of 6.0-6.8%, which is higher than Singapore-focused retail S-REITs, which are trading at yields of 5.5-6.6%. We have marginally increased
our FY14F earnings estimates to account for revised funding assumptions, no change to our TP. FCT offers investors a 24-25% total return for FY14/15,” noted DBS.
Here’s more from DBS:
Earlier this month, FCT announced that it had issued 88m shares at S$1.835/share (S$161.5m total) in a private placement to partially fund its S$305m acquisition of Changi City Point (CCP), which was completed on 16 June’14.
This issuance was well subscribed, accounting for c.52% of acquisition price, which is on the higher end of our initial assumptions of 40-45%, which was based on a gearing cap of 35% (vs 31% post-acquisition/placement).
As CCP is still in its first rent cycle and c.60% of leases are up for renewal in FY14/15, the Manager is uniquely poised to deliver earnings growth by refreshing the mall’s tenant mix to better cater to its growing catchment population.
While there are no plans to increase the relative proportion of F&B tenants from the existing c.44% level, we understand that the Manager is looking to bring in F&B tenants that better cater to the preferences of students at the upcoming Singapore University of Technology and Design (SUTD) by 2015 and workers at Changi Business Park.
Furthermore, for its retail tenants, the Manager is looking to offer a better complementary shopping experience for the weekend expo crowds. Through these initiatives, we forecast FCT to deliver 2-year earnings CAGR of 6% for FY15-16.

























 Read Here
 Advertise
 Sign Up








