How much will renters pay at SPH's new mall?
DMG makes an estimate on the average passing rent for the newly awarded Sengkang site.
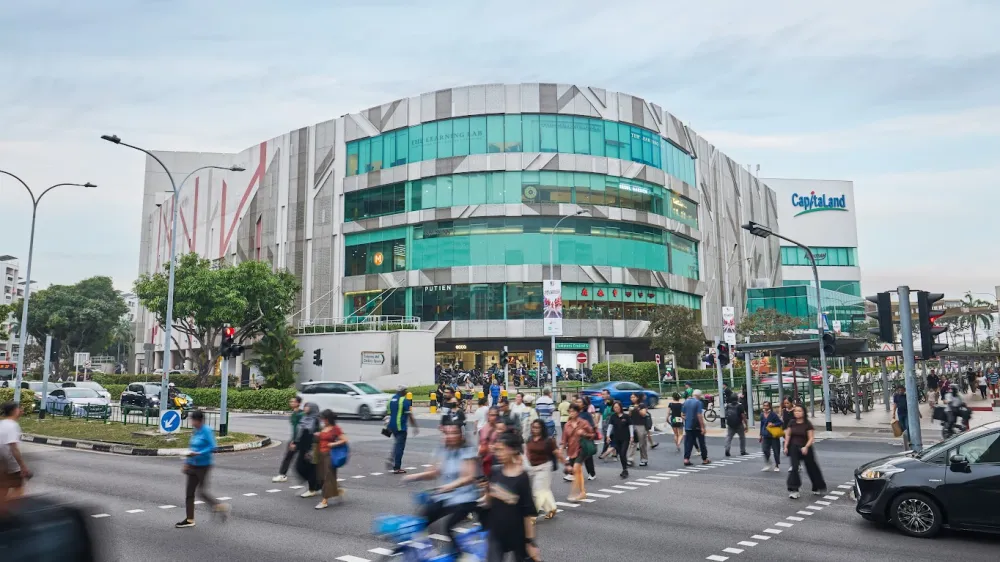
Given a peg project cost of S$1950/sqft for constructing the retail space, DMG predicts an average passing rent of S$12.80/sqft.
If the estimate holds up, this will make the prospective SPH mall just S$0.80/sqft more expensive than other Singapore malls like JCube and Causeway Point.
It is also expected to formally open in 2015 at the earliest.
Here's more from DMG:
Fair value for Sengkang site by our estimates. SPH has been awarded the tender for a Sengkang site. We think SPH paid a fair price, as we estimate SPH’s share of site and construction costs at ~S$291m, in-line with our in-house valuation of SPH’s stake in the prospective retail mall. We estimate the mall to cost S$1,950/sqft. This implies an average passing rent of S$12.80/sqft which is in line with other suburban malls such as JCube (S$12/sqft) and Causeway Point (S$12/sqft). We value the prospective mall based on a cap rate of 5.5%. We leave our earnings estimates and valuation for SPH unchanged as we await further details. The mall is also estimated to become operational only from 2015 onwards.
A JV between SPH and United Engineers. Earth Holdings, a JV between SPH (70%) and United Engineers (30%) was awarded the tender for the commercial site in Sengkang area. Its top bid of S$328m was 20% higher than the next highest bidder.
Cost of project in line with our valuations. We value the prospective mall at S$1,950/sqft based on an average passing rent assumption of S$12.80/sqft (in-line with JCube and Causeway Point rates), a cap rate of 5.5%, and NLA based on an efficiency rate of 75% of GFA. We assume net property income (NPI) margins of 70%, and construction costs at S$307/sqft.
SOTP-derived TP of S$3.91. We value the core media segment based on 11x FY12 P/E, Paragon (S$2.4b) with assumption of a 5% revaluation gain, Clementi Mall (S$266m) with assumption of average passing rent of S$15/sqft, cap rate of 5.5%, M1 and Starhub at DMG TP and investments as at Nov 11. We have not included the new Sengkang project as details are still unclear. Maintain NEUTRAL on SPH with attractive dividend yield of 6.6% for FY12.

























 Read Here
 Advertise
 Sign Up