3 core businesses will sustain ComfortDelGro till 2016
Combined profit contribution exceeds 50%.
ComfortDelGro will rely heavily on its Singapore taxi, Australia bus and UK/Ireland bus businesses to keep its earnings stable over the next three years, according to Maybank Kim Eng, with the latter two especially promising given some possible acquisitions on the horizon.
Here's more from Maybank Kim Eng;
Focusing on the business units that matter. Despite the diversity of CDG’s businesses, three major business units (Singapore Taxi: 23%, Australia Bus: 22%, UK/Ireland Bus: 12%) would collectively account for more than 56% of the group’s FY15E operating profits. While certain business units will experience near term challenges, these three core profit contributors will sustain the group’s earnings over the next 3 years.
UK & Australia bus to lead profit growth. Driven by a series of acquisitions, we forecast annual EBIT growth of 7% and 4% for CDG’s UK and Australia bus businesses over the next 3 years. Leveraging on their growing scale of operation, successful bids for new routes wouldprovide further upside to our forecasts.
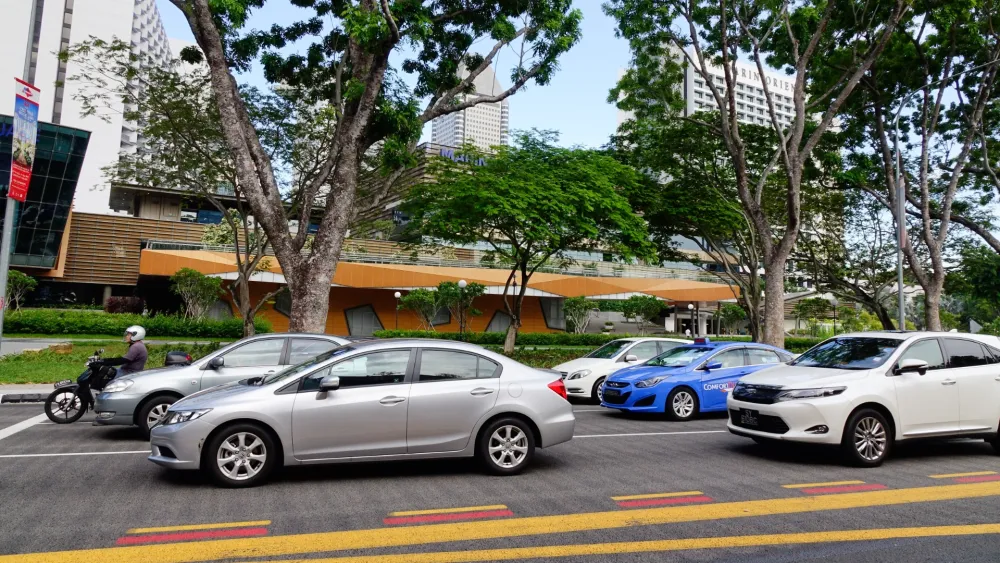
Singapore Taxi remains a key profit contributor. Despite conceding market share over the past 5 years (FY12: 58% vs FY07: 64%), management had demonstrated a strong profit focus at its Taxi operations in Singapore. While its fleet grew by merely 2% p.a. between FY08 to FY12, EBIT increased at a CAGR of 16% from SGD52mn to SGD93mn over the same period of time. We attribute the strong profitability of CDG’s operation to two key factors: 1) prudent fleet expansion at a time of high COE prices and 2) leveraging on its scale to grow an alternative income stream.
Limited exposure to negatives at Singapore’s fare based business. Profitability of Singapore’s rail and bus operators had been under pressure. While we have a negative near term view on Singapore’s fare based businesses, we argue that CDG’s diversification efforts have reduced their dependency on them. With CDG’s exposure to Singapore’s fare based at merely 8% of its market capitalization, we believe that their exposure is limited.
Valuation. CDG offers a unique defensive stock exposure with diversified earnings and geographical exposure. With continued weakness on the economic front, we expect sustained preference for defensive stocks in the year ahead. We value CDG using a FY14E P/E of 18X and derive a TP of SGD2.33. Upgrade to Buy.






















 Read Here
 Advertise
 Sign Up