Competitive intensity to decline for taxi industry: analyst
After years of disruption from ride-hailing apps, things may be about to finally settle for Singapore's taxis.
The competitive intensity in Singapore taxi industry could decline in the coming year amidst several developments in some companies, according to an analysis by RHB Bank.
Amongst the reasons cited is the recent news surrounding the talks on the proposed merger between Grab and Gojek, with reports suggesting that the companies have made substantial progress in working out a deal.
“This merger, if confirmed, should reduce the competitive intensity in Singapore’s taxi and private-hire car landscape, which has already witnessed a decline in demand this year due to the pandemic,” RHB analyst Shekhar Jaiswal said.
However, the reports noted that the talks are still fluid and may not result in a transaction, as the deal would need regulatory approval and governments may have antitrust concerns about the unification of the region’s two leading ride-hailing companies.
Also read: Grab, Gojek make progress on merger terms
The recent winning of the full digital bank licence by the consortium of Grab and telecommunications giant Singtel would also mean that Grab will be busy building its financial services businesses over the next two years as it plans to launch the digital bank in early 2022.
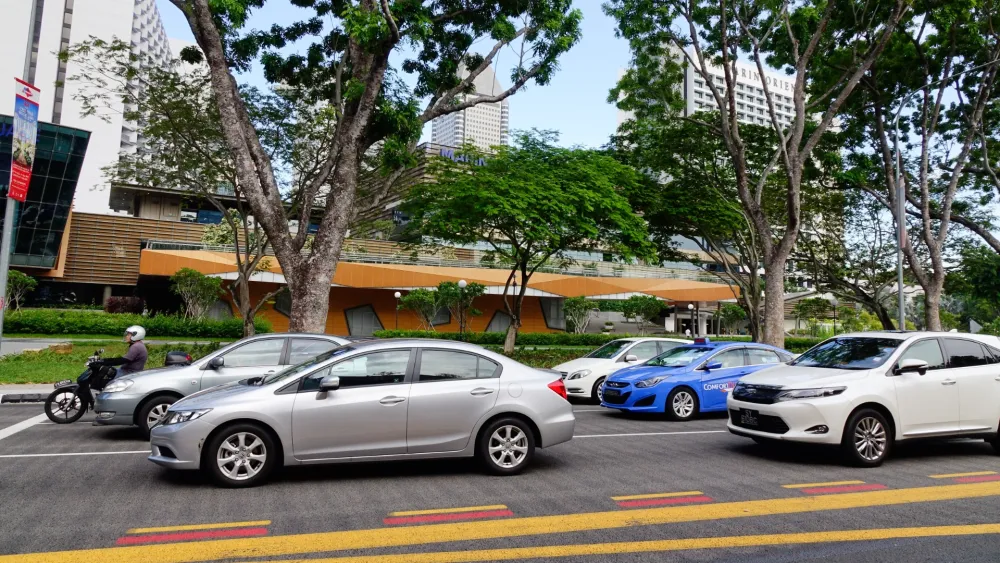
RHB believes that with the decline of demand for transport services, receipt of a full digital bank licence, and growing contributions from food delivery services, Grab could realign its focus away from the transport business in Singapore. This development could be positive for ComfortDelGro’s (CDG) taxi business.
RHB has maintained its "buy" recommendation for CDG, whilst raising its target price to $1.90. It has also raised CDG’s earning estimates for 2021 to 2022 by 3% to 4%, respectively to account for a slightly higher utilisation rate for CDG’s taxi fleet.
Jaiswal said the target price implies 19 times 2021F price-to-earnings (P/E) ratio, slightly higher than CDG's 10-year average P/E of 16 times. "The stock is also trading at a record low price-to-book value of 1.4 times, which does not capture the improvement in return on equity.”
“We maintain that gradual normalisation of business activities in Singapore and the company’s other key overseas markets should support an improvement in public transport ridership and a stabilisation of the taxi business during 2021,” he added.
Also Read: ComfortDelGro recover in 2021 likely: analyst
Amidst the impact of COVID-19, HDT Singapore has also announced the closure of its taxi business for good. The Land Transport Authority has previously accepted HDT’s application to exit the industry.
According to RHB, HDT ran the smallest fleet of 117 taxis over the industry size of 16,012 taxis as of the end of October.


















 Read Here
 Advertise
 Sign Up