RHB lifts SGX target to $16
The updated valuation is based on FY26 earnings and a higher price-to-earnings multiple of 23.5 times.
RHB has raised its target price for Singapore Exchange (SGX) to $16 from $14.10, reflecting a 5.5% potential upside from its current price of $15.20.
The updated valuation is based on FY26 earnings and a higher price-to-earnings multiple of 23.5 times, up from 22 times previously. This figure includes a 4% ESG premium, signaling investor confidence in SGX’s sustainable practices and long-term growth prospects.
RHB maintains a Neutral rating, noting that much of the near-term optimism may already be factored into the price.
The upgrade comes as SGX posted strong securities trading volumes in April 2025, with daily average value hitting $1.9b—the highest since March 2020.
However, trading activity has slowed in recent months, with May and June seeing lower SDAVs of $1.3b and an estimated $1.2b, respectively. Whilst full-year FY25 SDAV is still expected to grow 26% YoY, the recent pullback led RHB to trim its FY25 turnover forecast and reduce its profit estimate by 1%.
Despite the short-term dip, structural drivers remain intact. SGX is set to benefit from the Monetary Authority of Singapore’s $5b Equity Market Development Programme, which aims to boost investor participation beyond the benchmark STI stocks.
This initiative, along with increased share buybacks and Singapore’s appeal as a financial safe haven, supports the exchange’s medium-term growth trajectory.
Financially, SGX continues to show solid fundamentals. Recurring net profit is projected to rise 18.3% in FY25 to $631m, with further growth expected into FY26 and FY27.
Dividend yields are forecast to inch up gradually from 2.4% in FY25 to 2.6% in FY27, whilst capital expenditure is expected to remain at the lower end of guidance due to disciplined cost management and ongoing technology upgrades.
On the ESG front, SGX maintains a strong performance with an overall score of 3.3 out of 4. The exchange is committed to a 42% reduction in Scope 2 emissions by FY31 and continues to lead in sustainable finance initiatives.
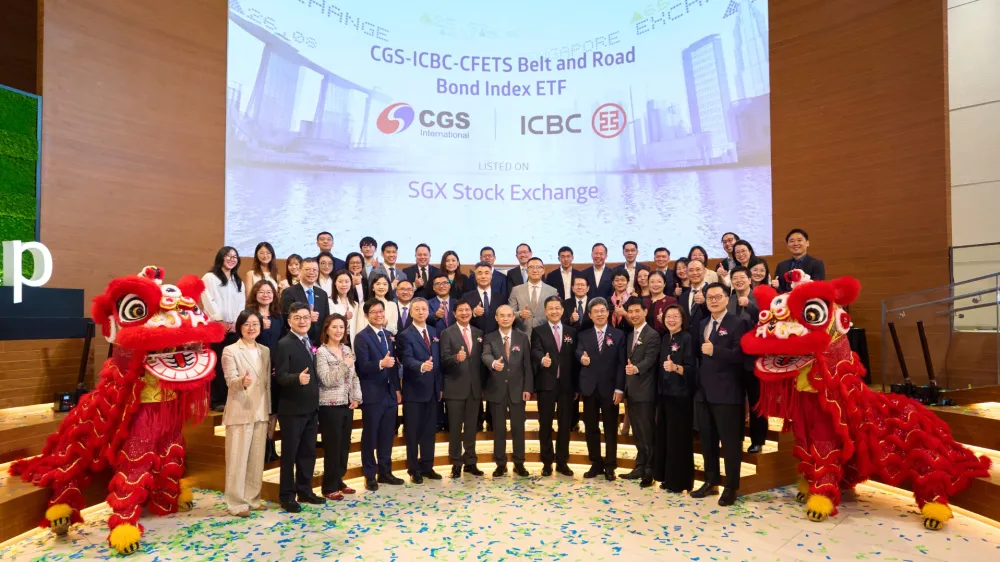
As of June 2024, sustainability-themed ETFs listed on SGX had a combined AUM of $927m, and 15% of new FY24 listings were green or sustainability-linked bonds. SGX also continues to enhance transparency and carbon reporting through new systems and climate transition plans.
Overall, whilst near-term trading momentum has moderated, SGX’s strategic positioning, ESG leadership, and long-term growth outlook justify the upgraded valuation.
RHB believes the exchange remains a stable play in a volatile global market, though it stops short of issuing a buy call due to already strong share price gains.





















 Read Here
 Advertise
 Sign Up