Regulatory gaps still block scale for live stablecoins
International accounting rules treat them as investments rather than cash, according to Societe Generale-FORGE.
Regulated stablecoins are operational and finding use cases, but a range of unresolved regulatory questions is preventing them from scaling.
Societe Generale-FORGE, a subsidiary of Societe Generale dedicated to digital assets, has been working on digital assets for six years, issuing tokenised bonds from 2019. For the past two years, it has issued two stablecoins: a euro and a US dollar stablecoin, both called coinvertible and regulated under MiCA.
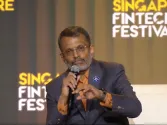
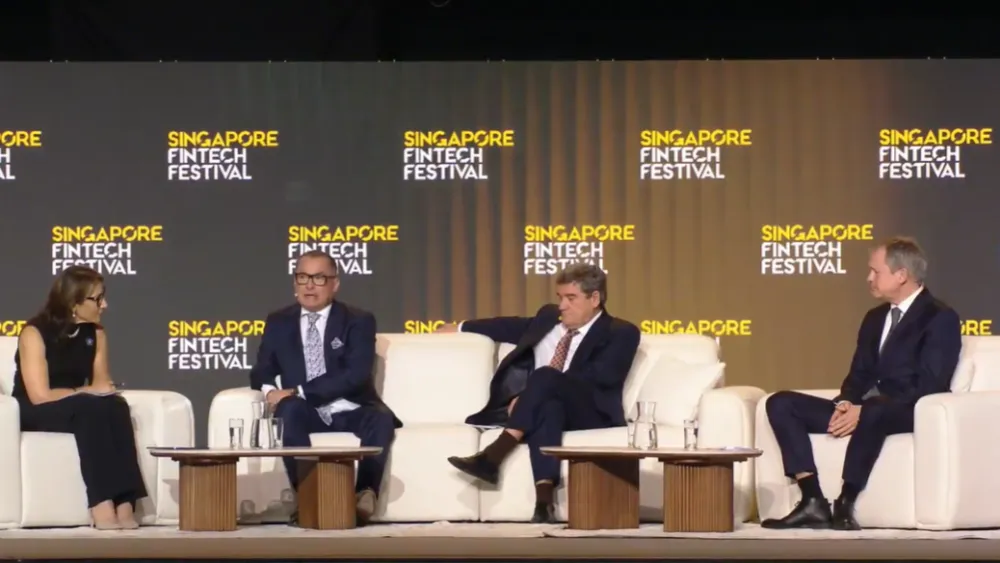
Speaking at the Singapore FinTech Festival, Chief Strategy and Global Policy Officer Stephanie Cabossioras said the firm was amongst the first major banking entities in the world to issue stablecoins. It was also the first to receive a MiCA licence in Europe for stablecoin issuance, in July 2024.
“Every time we want to develop a use case, there’s always a legal blocker somewhere,” she said.
The blockers are concrete and varied. For international companies, regulated stablecoins are not treated as cash equivalents under IFRS but as investment products, adding accounting friction for corporates that want to hold them. France has updated its accounting norms to treat MiCA-regulated stablecoins as cash equivalents, but that change applies only under French norms and has not been adopted under IFRS for large international companies.
Investment funds present a separate obstacle. Tokenised investment fund shares are emerging, but buyers cannot use stablecoins to purchase them without the fund off-ramping to fiat intraday, meaning the fund cannot hold stablecoins as a settlement asset.
For central counterparties, stablecoins could address a specific need. Using them for margin calls and collateral management would allow collateral to move instantly, reducing the amount immobilised as guarantee whilst awaiting settlement. CCP regulation in Europe, however, makes no mention of blockchain, creating legal uncertainty that is only beginning to be addressed.
Stablecoins are also not recognised as high-quality liquid assets for prudential purposes, adding further friction for institutions.
“We don’t believe that this new technology will change fundamentally the business drivers, but it will change the infrastructure, the technology,” Cabossioras said. “It’s really a challenge for incumbents, for financial institutions, for big banks to accompany this change, to offer that to our clients.”
On the central bank side, wholesale CBDC infrastructure is already moving. Dr. Alexandra Hachmeister, director general Digital Euro at Deutsche Bundesbank, said the euro system has been running a full production environment for wholesale CBDC transactions since end of September, with market participants already testing different transaction types including large issuances.
She said the next step is for the asset side to truly tokenise at scale.
Cabossioras said the firm is working on several fronts. Use cases include crypto market infrastructure, bringing regulated assets into refinancing, repo, and collateral management, and cross-border payments, including a corridor with Asia.
The firm has developed partnerships with central securities depositories including Clearstream and Euroclear, as well as SWIFT, with the aim of integrating stablecoins as a cash leg for securities settlement. That work is not yet live, and regulatory frameworks still need to evolve to support it.
Cabossioras said the underlying belief driving the firm’s work is structural.
“The banking infrastructure layer, post-market payment infrastructure will progressively move to DLT, decentralised infrastructure, blockchain infrastructures, just for one reason, because it allows instant transfer of value all around the world,” she said.
She said the most urgent near-term need from the industry is for all financial institutions to build wallet infrastructure for clients. Wallets, she said, are “the fundamental brick on which we can build all the use cases,” and until they are universally available, the new products cannot scale.

















 Read Here
 Advertise
 Sign Up